
Bank of America points to improved Q4 results – BAC stock forecast following Q3 2026 report
Bank of America increased net interest income, but a regulatory charge and rapidly rising expenses reduced profit. Management expects an improvement as early as Q4, while a break above the 52.60 USD resistance level will be a key signal for BAC shares.
Bank of America Corporation (NYSE: BAC) ended Q3 2026 with revenue up 3%, but profit fell. A one-off regulatory charge of 1.2 billion USD significantly weighed on the bottom line.
The bank’s traditional interest-earning business provided the main support, with income increasing due to strong loan portfolio growth and higher asset yields. At the same time, lower fee income from investment banking and a decline in trading revenue from financial markets noticeably constrained overall revenue growth. Combined with rising costs, this heightened investor concerns about the bank’s ability to deliver consistent profit growth even if demand for its services remains strong.
Management expects the relationship between revenue and expenses to improve as early as the next quarter, alongside further growth in the interest-earning business in 2027. Under current conditions, the future performance of BAC shares will depend directly on whether these forecasts materialise. Meeting management’s expectations would restore market confidence and support a solid recovery in the share price.
This article analyses Bank of America shares following the Q3 2026 report, examining the bank’s main sources of revenue and key business metrics. It also provides a fundamental analysis of BAC and assesses key technical levels, which form the basis for a Bank of America stock forecast for 2026.
About Bank of America Corporation
Bank of America Corporation is one of the world’s largest financial institutions, offering a broad range of banking and related services. Amadeo Giannini founded the bank in 1904 in San Francisco, US, under the name Bank of Italy, which was rebranded as Bank of America in 1930. The modern corporation emerged in 1998 following a merger with NationsBank.
Bank of America offers a broad range of services, including retail and corporate banking, investment and insurance products, asset management, and mortgage and lending services. Its headquarters are in Charlotte, North Carolina, US.
The bank’s IPO occurred in 1957 when its shares began trading on the New York Stock Exchange under the ticker BAC. Bank of America is among the largest banks in the US and worldwide, serving clients in more than 35 countries and managing assets exceeding 3.4 trillion USD.
Bank of America Corporation’s main sources of revenue
Bank of America’s main areas of financial activity that generate revenue span a range of businesses, including retail, corporate, and investment services. They can be divided into the following categories:
Net interest income: generated from the difference between the interest received on loans and the interest paid to customers on deposits and other sources of funding. Bank of America offers a wide range of financial products, including mortgages, commercial and auto loans, as well as credit cards.
Fee income: revenue from fees charged for servicing client transactions. This includes account servicing, payments and transfers, as well as asset management fees.
Investment banking revenue: fees for mergers and acquisitions advisory services, income from equity and bond offerings, as well as trading in financial instruments, including securities, currencies, and derivatives.
Asset management and investment services: fees for managing the assets of private and institutional clients, brokerage services, and other investment services.
Trading and market activities: income from transactions involving securities, currencies, and derivatives.
Other sources of revenue: safe deposit box fees, investments in sustainability and infrastructure projects, and income from holdings of government and corporate bonds.
These business areas diversify the bank’s revenue streams and make them more resilient to economic downturns, allowing Bank of America to compete effectively in the global market.
Bank of America Corporation’s strengths and weaknesses
Bank of America’s strengths include:
Diversified revenue streams: the bank offers a broad range of financial services, including retail banking, investment services, asset management, corporate banking, and insurance. This diversity strengthens Bank of America’s resilience to market fluctuations across multiple segments, allowing it to generate revenue from various sources.
Digital innovation: the bank is actively implementing digital technologies, including mobile apps and the virtual assistant Erica. These innovations enhance service quality, improve operational efficiency, and help attract new clients.
Strong position in investment banking and asset management: the bank’s competitive advantages in investment and private banking, combined with effective asset management, ensure its leadership in both the US and internationally. As a result, it can offer high-quality services to high-net-worth clients and large international corporations worldwide.
Wide network and global presence: with representative offices in more than 35 countries, the bank can serve clients regardless of location. The bank holds a leading position in both domestic and international markets.
Substantial capital and liquidity reserves: with extensive financial resources and highly liquid assets, the bank is well-equipped to manage risks and maintain stability during economic downturns effectively.
Bank of America’s weaknesses include:
Dependence on interest rates: the bank’s primary revenue stream is derived from the spread between interest earned on loans and interest paid on deposits. This makes it sensitive to changes in financial regulators’ monetary policy and fluctuations in interest rates. During periods of low rates, profitability typically declines.
High operating costs: despite the scale of the corporation and its elevated level of digitalisation, the bank incurs more substantial costs compared to its competitors, including JPMorgan Chase (NYSE: JPM) and Wells Fargo (NYSE: WFC). These costs affect the overall profitability of the transactions.
Weakness in certain retail banking segments: although the bank holds a significant market share in the US, it lags behind competitors such as JPMorgan Chase and Wells Fargo in the retail banking and credit card segments. These banks have a larger client base and more developed service networks.
Overall, Bank of America is a strong player in the financial market thanks to its diversification and innovation. However, it faces challenges, including sensitivity to macroeconomic factors and elevated operating expenses.
Bank of America Corporation Q3 2024 financial results
In October, Bank of America published its Q3 2024 financial results for the quarter ended 30 September. The key data from the report is outlined below:
Revenue: 25.30 billion USD (+1%)
Net income: 6.90 billion USD (–12%)
Earnings per share: 0.81 USD (–10%)
Net Interest income: 14.0 billion USD (–3%)
Revenue by segment:
Consumer Banking: 10.40 billion USD (–1%)
Global Wealth and Investment Management: 5.80 billion USD (+8%)
Global Banking: 5.83 billion USD (–6%)
Global Markets: 5.60 billion USD (+14%)
Net income by segment:
Consumer Banking: 2.70 billion USD (–6%)
Global Wealth and Investment Management: 1.10 billion USD (+1%)
Global Banking: 1.90 billion USD (–27%)
Global Markets: 1.50 billion USD (+25%)
Shareholders received nearly 5.60 billion USD, including 2.00 billion in dividends and 3.50 billion through share buybacks.
Despite a 1% increase in total revenue, the bank’s net income declined by 12%, with profits from banking operations in both the global and US consumer markets falling. However, as in the previous quarter, the investment segment continued to show positive momentum, helping to offset the negative impact of the banking services sector.
Bank of America Corporation Q4 2024 financial results
Bank of America Corporation released its Q4 2024 financial results on 16 January 2025. The key report highlights, compared to the corresponding period of 2023, are outlined below:
Revenue: 25.3 billion USD (+15%)
Net income: 6.7 billion USD (+112%)
Earnings per share: 0.82 USD (+134%)
Net interest income: 14.4 billion USD (+3%)
Revenue by segment:
Consumer Banking: 10.6 billion USD (+3%)
Global Wealth and Investment Management: 6.0 billion USD (+15%)
Global Banking: 6.1 billion USD (+3%)
Global Markets: 4.8 billion USD (+20%)
Net income by segment:
Consumer Banking: 2.8 billion USD (+2%)
Global Wealth and Investment Management: 1.2 billion USD (+14%)
Global Banking: 2.1 billion USD (–13%)
Global Markets: 941 million USD (+27%)
In the Q4 2024 earnings report, Bank of America’s management expressed optimism about the company’s performance and outlook. It was noted that each business line contributed more to revenue, and there was a noticeable increase in deposits and loans granted, surpassing the industry average. Net interest income was projected to range between 14.5 and 14.6 billion USD in Q1 2025, with steady growth expected to bring it to approximately 15.5-15.7 billion USD by Q4 2025. The second half of 2025 was expected to exhibit stronger growth than the first, thereby maintaining an operational advantage throughout the year.
Bank of America Corporation Q1 2025 financial results
On 15 April, Bank of America published its Q1 2025 financial results for the quarter ended 31 March. The key figures are as follows:
Revenue: 27.37 billion USD (+6%)
Net income: 7.40 billion USD (+11%)
Earnings per share: 0.90 USD (+18%)
Net Interest income: 14.44 billion USD (+3%)
Revenue by segment:
Consumer Banking: 10.49 billion USD (+3%)
Global Wealth and Investment Management: 6.02 billion USD (+7%)
Global Banking: 5.97 billion USD (0%)
Global Markets: 6.58 billion USD (+12%)
Net income by segment:
Consumer Banking: 2.53 billion USD (–4%)
Global Wealth and Investment Management: 1.00 billion USD (0%)
Global Banking: 1.91 billion USD (–3%)
Global Markets: 1.94 billion USD (+13%)
Bank of America delivered strong Q1 2025 results that exceeded Wall Street expectations and prompted cautious optimism among investors. Trading revenue made the main contribution to profit growth, particularly in equities, where revenue increased 17%, amid a broader surge in market activity among leading US banks.
In Q1 2025, Bank of America increased its provisions for potential credit losses from 1.3 billion USD to 1.5 billion USD. The increase reflected the bank’s cautious approach to credit risks amid economic uncertainty.
Bank of America management did not provide specific guidance for Q2 2025. However, the bank expected net interest income to grow by 6–7% in 2025, reaching between 15.5 billion USD and 15.7 billion USD by Q4 2025, thereby reaffirming the guidance provided in its Q4 2024 financial results commentary. The consumer business was identified as the main driver of net interest income growth.
Bank of America Corporation Q2 2025 financial results
On 16 July, Bank of America published its Q2 2025 financial results for the quarter ended 30 June. The key figures compared with the same period a year earlier are as follows:
Revenue: 27.51 billion USD (+4%)
Net income: 7.11 billion USD (+3%)
Earnings per share: 0.89 USD (+7%)
Net Interest Income: 14.67 billion USD (+7%)
Revenue by segment:
Consumer Banking: 10.81 billion USD (+6%)
Global Wealth and Investment Management: 5.93 billion USD (+7%)
Global Banking: 5.69 billion USD (–7%)
Global Markets: 6.01 billion USD (+10%)
Net income by segment:
Consumer Banking: 2.97 billion USD (+14%)
Global Wealth and Investment Management: 0.99 billion USD (–3%)
Global Banking: 1.70 billion USD (–19%)
Global Markets: 1.56 billion USD (+10%)
Bank of America delivered strong Q2 2025 results, with net income rising to 7.1 billion USD, or 0.89 USD per share, 3% higher year-on-year and above analysts’ expectations, although revenue came in slightly below forecasts. The main growth drivers were the record net interest income of 14.7 billion USD (+7%) and a sharp increase in trading revenue to 5.3 billion USD (+14%) amid market volatility and geopolitical uncertainty.
The CFO emphasised that net interest income would continue to grow and could reach 15.5–15.7 billion USD by Q4. The bank also expected loan growth in the mid-single digits, at around 4–6%, and expenses to remain stable or even decline through the end of 2025. Trading revenue was also expected to continue growing at a mid-single-digit rate, extending its current run of positive growth to 13 consecutive quarters. Investment banking remained the weak spot, with fees falling around 9% year-on-year, although management expected deal activity to pick up towards the end of the year.
Bank of America Corporation Q3 2025 financial results
On 15 October, Bank of America published its Q3 2025 financial results for the quarter ended 30 September. The key figures compared with the same period a year earlier are as follows:
Revenue: 28.08 billion USD (+11%)
Net income: 8.46 billion USD (+23%)
Earnings per share: 1.06 USD (+31%)
Net Interest Income: 15.23 billion USD (+9%)
Revenue by segment:
Consumer Banking: 11.16 billion USD (+7%)
Global Wealth and Investment Management: 6.31 billion USD (+10%)
Global Banking: 6.26 billion USD (+7%)
Global Markets: 6.22 billion USD (+10%)
Net income by segment:
Consumer Banking: 3.44 billion USD (+28%)
Global Wealth and Investment Management: 1.27 billion USD (+20%)
Global Banking: 2.13 billion USD (+11%)
Global Markets: 1.65 billion USD (+4%)
Bank of America delivered better-than-expected Q3 2025 results. Revenue reached 28.1 billion USD, net income was 8.5 billion USD, and earnings per share came in at 1.06 USD. Return on equity reached 15.4%, exceeding analysts’ expectations. The main drivers were record net interest income and a notable recovery in investment banking fees.
The bank’s performance improved compared with Q2 2025. Provisions for potential credit losses fell to 1.3 billion USD from 1.6 billion USD, while loan charge-offs fell about 10%, suggesting credit quality was stabilising.
Results also improved significantly year-on-year: revenue increased 11%, while earnings per share rose from 0.81 USD to 1.06 USD. Net interest income reached 15.2 billion USD (+9%), supported by growth in loan and deposit volumes. Investment banking fees increased 43% to 2.0 billion USD, while trading revenue rose 9%. Client card spending increased 6%, indicating that consumers remained in good financial health.
Management expected net interest income to reach 15.6–15.7 billion USD in Q4 2025, up 8% year-on-year. The bank planned to keep expenses under control and continue returning capital to shareholders while maintaining strong capitalisation.
Bank of America Corporation Q4 2025 financial results
On 14 January 2026, Bank of America published its Q4 2025 financial results for the quarter ended 31 December. The key figures compared with the same period a year earlier are as follows:
Revenue: 28.39 billion USD (+7%)
Net income: 7.60 billion USD (+12%)
Earnings per share: 0.98 USD (+18%)
Net Interest Income: 15.89 billion USD (+9%)
Revenue by segment:
Consumer Banking: 12.53 billion USD (+7%)
Global Wealth and Investment Management: 6.73 billion USD (+9%)
Global Banking: 6.18 billion USD (+7%)
Global Markets: 5.64 billion USD (+8%)
Net income by segment:
Consumer Banking: 3.24 billion USD (+14%)
Global Wealth and Investment Management: 1.49 billion USD (+20%)
Global Banking: 2.00 billion USD (+5%)
Global Markets: 1.33 billion USD (+9%)
Bank of America delivered strong Q4 2025 results, exceeding market expectations for both revenue and earnings. Revenue reached 28.4 billion USD, slightly above analysts’ consensus forecast of 27.5–27.8 billion USD, while net income came in at 7.6 billion USD, up 12% year-on-year. Earnings per share were 0.98 USD, also above the 0.96 USD forecast. Strong net interest income was the main growth driver, rising 9% to 15.89 billion USD and demonstrating the bank’s ability to generate earnings in a high-interest-rate environment.
Markets and trading activities were also important contributors to earnings. The investment and trading businesses delivered solid growth, with strong growth in revenue from securities and currency trading, while higher fee income and asset management revenue provided additional resilience to the results.
Client credit quality remained stable despite the economic slowdown and high interest rates. Average loans grew 8%, indicating continued demand for credit from both individual and business customers.
Management raised its 2026 net interest income outlook, expecting growth of 5–7%. High interest rates were expected to continue supporting performance in this area, although a potential economic slowdown and rising expenses could constrain earnings over the longer term. The outlook for the coming quarters remained moderately positive, with the bank planning to keep expenses under control while continuing to support shareholder distributions, including dividends and share buybacks.
Bank of America Corporation Q1 2026 financial results
On 15 April 2026, Bank of America published its Q1 2026 financial results for the quarter ended 31 March. The key figures compared with the same period a year earlier are as follows:
Revenue: 30.27 billion USD (+7%)
Net income: 8.58 billion USD (+17%)
Earnings per share: 1.11 USD (+25%)
Net Interest Income: 15.75 billion USD (+9%)
Revenue by segment:
Consumer Banking: 11.05 billion USD (+5%)
Global Wealth and Investment Management: 6.71 billion USD (+12%)
Global Banking: 6.29 billion USD (+5%)
Global Markets: 7.11 billion USD (+8%)
Net income by segment:
Consumer Banking: 3.06 billion USD (+21%)
Global Wealth and Investment Management: 1.33 billion USD (+32%)
Global Banking: 2.09 billion USD (+8%)
Global Markets: 2.01 billion USD (+3%)
Bank of America delivered strong Q1 2026 results and exceeded market expectations for earnings. Revenue rose to 30.3 billion USD, net income reached 8.6 billion USD, and earnings per share came in at 1.11 USD, up from 0.89 USD a year earlier.
Credit quality remained resilient. The provision for credit losses declined to 1.3 billion USD from 1.5 billion USD a year earlier. Net charge-offs also declined slightly year-on-year, though they rose from the previous quarter due to credit card seasonality. Average loans and leases increased 9% to 1.19 trillion USD, average deposits rose 3% to 2.02 trillion USD, and client card spending increased 7% to 245 billion USD. These figures indicated stable demand for banking products and consumer activity.
Bank of America did not provide guidance for Q2 2026 revenue, earnings, or EPS in its published materials. However, management had previously expected net interest income to grow by at least 7% in Q1 2026 and was targeting growth of 5–7% for full-year 2026. The actual Q1 result exceeded even these expectations.
Bank of America Corporation Q2 2026 financial results
On 14 July 2026, Bank of America published its Q2 2026 financial results for the quarter ended 30 June. The key figures compared with the same period a year earlier are as follows:
Revenue: 31.56 billion USD (+15%)
Net income: 9.07 billion USD (+27%)
Earnings per share: 1.21 USD (+34%)
Net Interest Income: 15.99 billion USD (+9%)
Revenue by segment:
Consumer Banking: 11.34 billion USD (+5%)
Global Wealth and Investment Management: 6.87 billion USD (+16%)
Global Banking: 6.24 billion USD (+10%)
Global Markets: 8.02 billion USD (+34%)
Net income by segment:
Consumer Banking: 3.28 billion USD (+10%)
Global Wealth and Investment Management: 1.41 billion USD (+42%)
Global Banking: 2.05 billion USD (+21%)
Global Markets: 2.63 billion USD (+72%)
Bank of America maintained the positive momentum seen in the previous quarter in Q2 2026. The bank again increased revenue, net income, and earnings per share versus the same period a year earlier, while EPS beat market expectations, with analysts forecasting around 1.13 USD per share.
Markets and investment banking activities were the main drivers of the quarter. Consumer Banking maintained moderate growth, supported by higher net interest income, increased client card spending, and a stable deposit base. Global Wealth and Investment Management also improved its performance, driven by higher asset management fees and increased client balances.
Credit quality remained resilient. The provision for credit losses was 1.4 billion USD, compared with 1.6 billion USD a year earlier. Net charge-offs were virtually unchanged from the previous quarter, while the credit card net charge-off rate declined.
The 2026 net interest income outlook improved slightly. The bank’s CFO noted that NII growth for the year could come in at the upper end of the previously indicated 6–8% range. This suggested Bank of America expected lending, its deposit base, and asset repricing to continue supporting NII.
Bank of America Corporation Q3 2026 financial results
On 14 October 2026, Bank of America published its Q3 2026 financial results for the quarter ended 30 September. The key figures compared with the same period a year earlier are as follows:
Revenue: 29.96 billion USD (+3%)
Net Income: 6.93 billion USD (–17%)
Earnings Per Share: 0.91 USD (–13%)
Net Interest Income: 16.45 billion USD (+8%)
Revenue by segment:
Consumer Banking: 11.57 billion USD (+4%)
Global Wealth and Investment Management: 7.12 billion USD (+13%)
Global Banking: 6.21 billion USD (+0.3%)
Global Markets: 5.87 billion USD (–6%)
Net Income by segment:
Consumer Banking: 3.52 billion USD (+2%)
Global Wealth and Investment Management: 1.54 billion USD (+22%)
Global Banking: 1.99 billion USD (–5%)
Global Markets: 1.24 billion USD (–25%)
Bank of America’s Q3 2026 results showed that the bank continued to increase revenue from lending and client services, although profitability came under pressure. Revenue rose 3% to 29.96 billion USD, while net income fell 17% to 6.93 billion USD. The main driver of the profit decline was a 1.2 billion USD regulatory charge related to the settlement of claims by FinCEN and the US Office of the Comptroller of the Currency (OCC). Excluding the cost of the regulatory settlements, net income would have been around 8.1 billion USD, slightly below 8.3 billion USD a year earlier.
Net interest income provided the main support to the business, rising 8% to 16.45 billion USD. Average loans increased 6%, while deposits rose 2%. The gradual repricing of fixed-rate assets provided additional support: as older loans and bonds mature, the bank can reinvest funds at higher yields. This process could support revenue for several quarters.
Consumer Banking delivered steady, albeit moderate, growth. The bank added more than 200,000 consumer checking accounts, while client credit and debit card spending increased 8%. At the same time, the segment’s average loan and deposit balances were virtually unchanged.
Global Wealth and Investment Management, which includes Merrill and Private Bank, delivered the strongest results. Net asset inflows were around 20 billion USD. Rising client portfolio values and new investments increased the bank’s fee income. This is an attractive source of recurring revenue, although its performance depends on financial market conditions.
Trading activities were one of the quarter’s main disappointments. Sales and trading revenue declined 5% to 5.1 billion USD, although the bank had previously expected a result roughly in line with the previous year. Revenue from fixed income, currencies, and commodities declined particularly sharply. Investment banking fees across the group fell 11% to 1.8 billion USD.
Expense control also warrants particular attention. Excluding the regulatory charge, expenses rose almost 7% to 18.5 billion USD, compared with a 3% increase in revenue. This means that additional revenue is not yet translating into profit quickly enough. The bank is investing in technology, artificial intelligence, client acquisition, and business development. These investments could improve efficiency in the future, but weighed on results in the current quarter. Management expects revenue growth to outpace expense growth again as early as Q4.
The bank continued to return capital to shareholders, allocating 8.3 billion USD to dividends and share buybacks during the quarter. At the same time, the CET1 capital ratio declined to 10.9% from 11.2% in the previous quarter.
Management’s outlook points to continued growth in net interest income: around 8% for full-year 2026 and 8% or more in 2027. The assumptions underlying the outlook include moderate loan and deposit growth, asset repricing, and three 0.25-percentage-point Fed rate increases by June 2027. For the Bank of America stock forecast, a key factor will be the bank’s ability to deliver the expected growth in net interest income while restoring positive operating leverage, with revenue growing faster than expenses.
Fundamental analysis of BAC and key drivers of Bank of America Corporation shares
To assess the outlook for BAC shares, it is important to monitor how revenue growth translates into profit. The focus is on the bank’s ability to offset declining investment banking fees and trading revenue while keeping expenses under control. Four metrics help assess this relationship.
Investment Banking Fees
Sales & Trading Revenue
Efficiency Ratio
Net Interest Income
Investment Banking Fees represent fees earned from arranging equity and bond offerings, advising on mergers and acquisitions, and providing other services to corporate clients. For the shares, a recovery in deal activity and BAC’s ability to win new mandates are important: higher fees increase the potential for profit growth.
Sales & Trading Revenue reflects revenue from facilitating client transactions in equities, bonds, currencies, and other financial instruments. In Q3, it declined 5%. A return to sustained growth in this metric could support earnings expectations.
Efficiency Ratio shows the proportion of revenue used to cover operating expenses: the lower the ratio, the more revenue remains before provisions and taxes. In Q3, the ratio reached 65.8%, or around 62.0% excluding the one-off regulatory settlement, compared with 59.7% a year earlier. Even excluding the one-off charge, expenses rose 7%, while revenue increased 3%. Slower expense growth relative to revenue growth would be a positive signal for the shares.
Net Interest Income is the difference between interest earned on loans and securities and interest paid on deposits and other sources of funding. In Q3, it rose 8% to 16.45 billion USD.
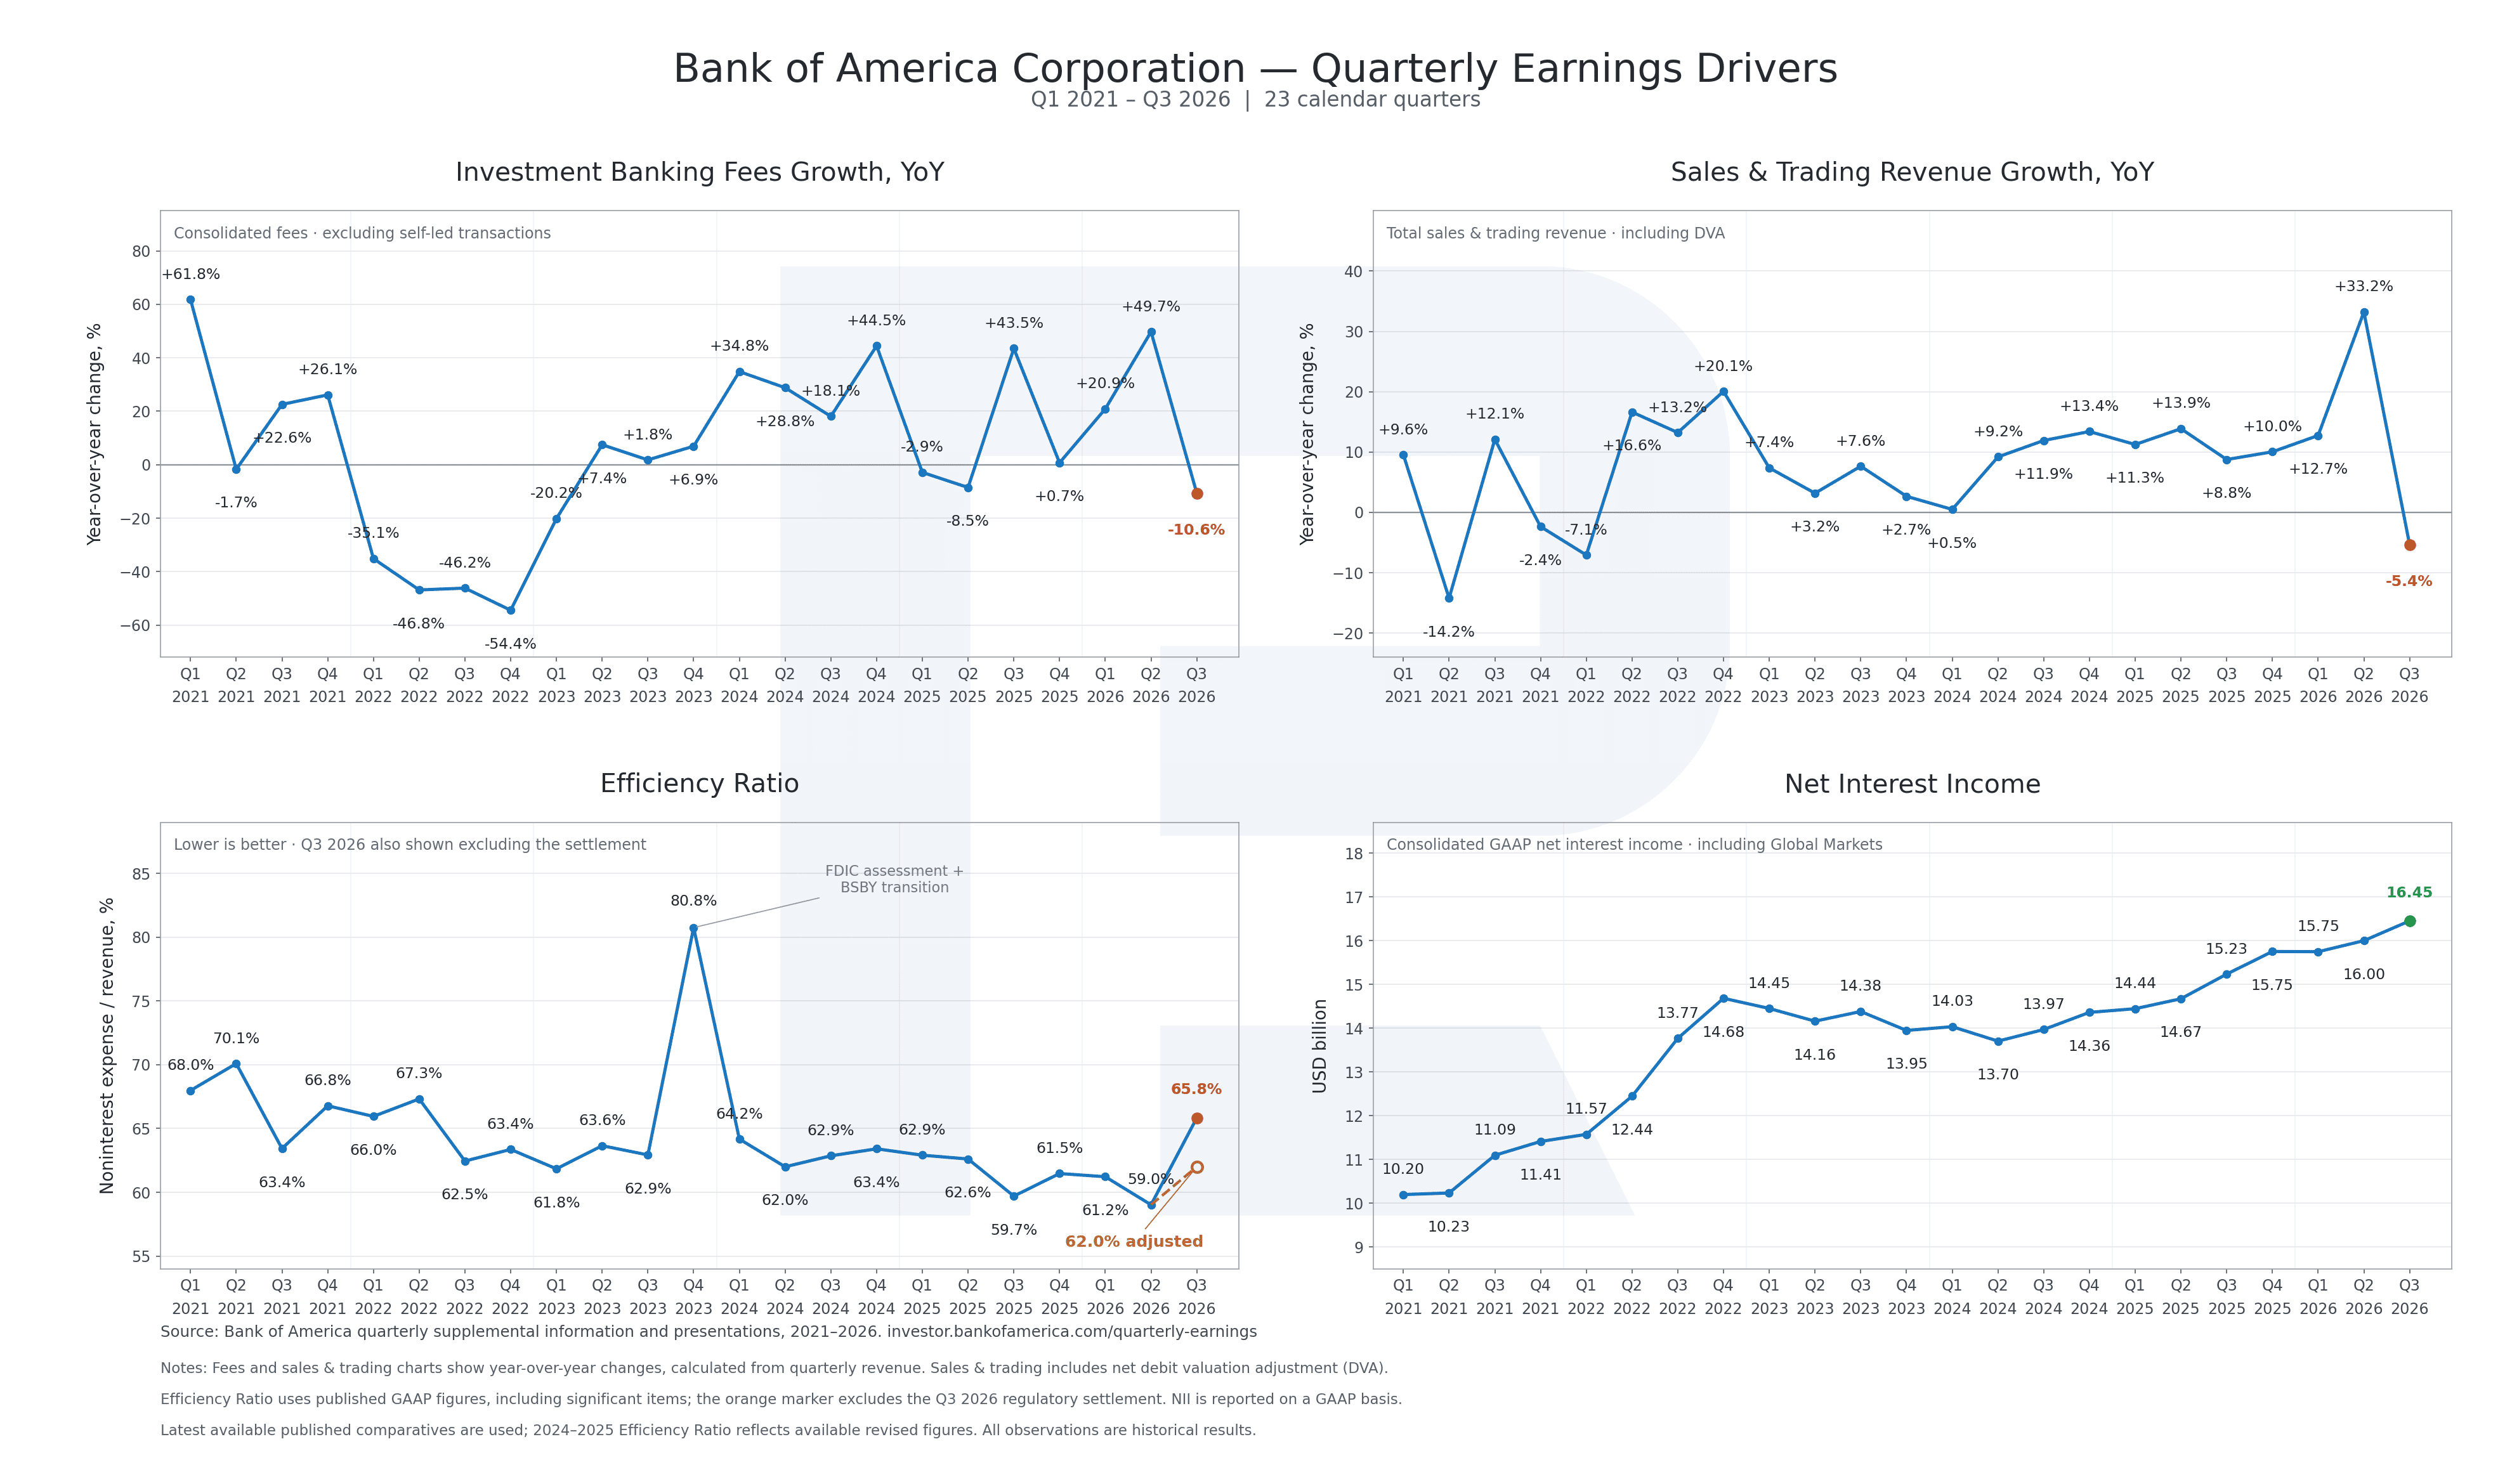
The fundamental analysis of BAC shows that pressure on business profitability is becoming the bank’s main challenge. Following a strong first half of the year, investment banking fees and trading revenue began to decline year-on-year.
Net interest income growth continues to support the bank’s results, but expenses are absorbing much of the improvement. Even excluding the one-off regulatory charge, expenses rose 7% while revenue increased 3%. The deterioration in the Efficiency Ratio therefore cannot be attributed solely to the charge: the bank is spending more to generate each dollar of revenue. This indicates a reduced ability to translate business expansion into additional profit.
Management’s outlook points to an improvement as early as the next quarter. The bank expects revenue growth to once again outpace expense growth in Q4. At the same time, BAC maintained its forecast for net interest income growth of 8% in 2026 and expects growth of 8% or more in 2027. This creates the potential for profit growth to recover, provided higher costs don’t absorb the additional revenue.
Confirmation of the outlook in the Q4 report could be the next catalyst for BAC shares. If revenue begins to grow faster than expenses, the Q3 deterioration could be seen as a temporary pause in the improvement in results. A recovery in investment banking fees and trading revenue would further strengthen this scenario.
Expert forecasts for Bank of America Corp stock in 2026
The analyst forecasts below cover a 12-month horizon, with the upper and lower bounds representing BAC share price targets over this period:
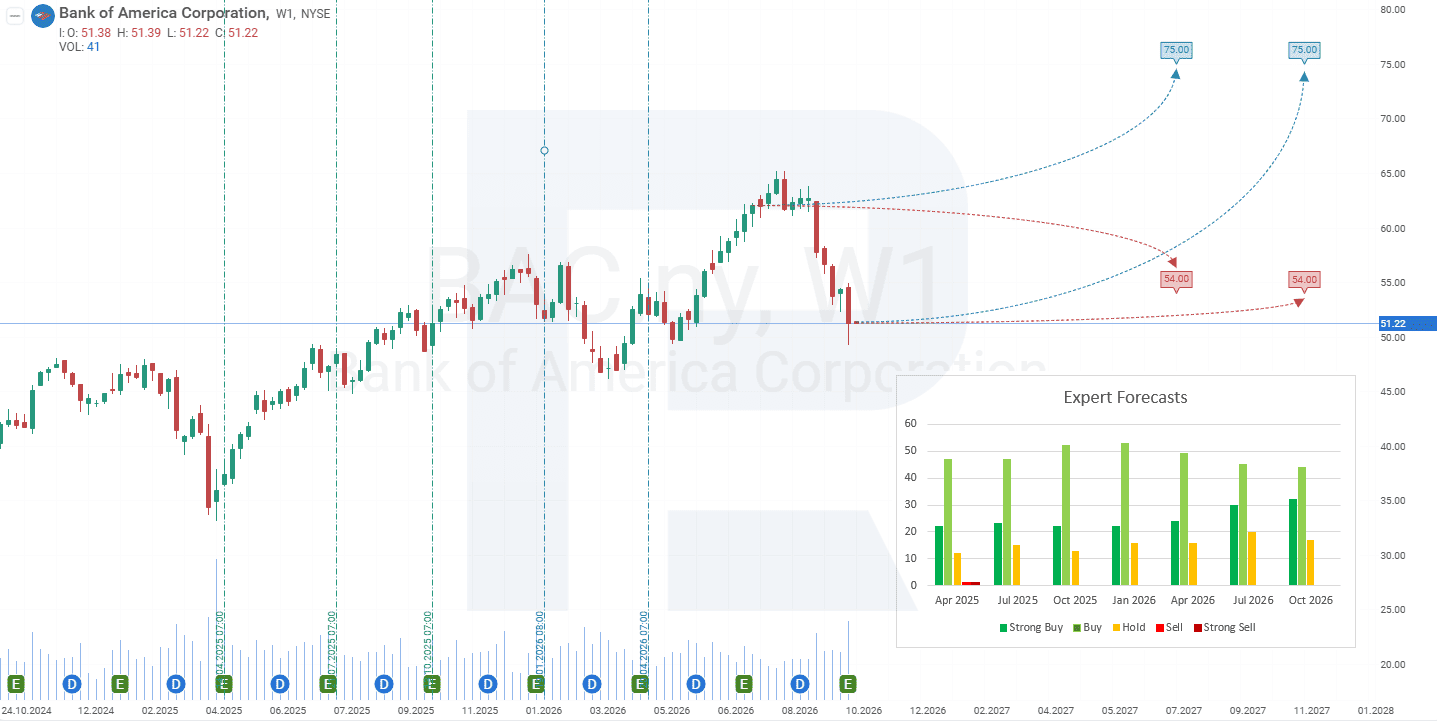
Barchart : 16 of 26 analysts rated Bank of America shares a Strong Buy, 4 a Moderate Buy, and 6 a Hold. The upper end of the forecast is 72 USD, and the lower end is 55 USD.
MarketBeat : 20 of 26 analysts rated the shares a Buy, while 6 recommended a Hold. The upper end of the forecast is 72 USD, and the lower end is 54 USD.
TipRanks : 14 of 16 analysts recommended a Buy, while 2 recommended a Hold. The upper end of the forecast is 75 USD, and the lower end is 56 USD.
Stock Analysis : 16 of 25 analysts rated the shares a Strong Buy, 6 a Buy, and 3 a Hold. The upper end of the forecast is 71 USD, and the lower end is 56 USD.
The analyst outlook for Bank of America shares remains predominantly positive. Importantly, even the lower price targets across all four platforms – 54–56 USD – are above the current share price of around 51.20 USD. This suggests analysts generally view the current decline in BAC shares as temporary price pressure rather than a sign of a significant deterioration in the bank’s long-term prospects.
Technical analysis of BAC and Bank of America stock forecast for 2026
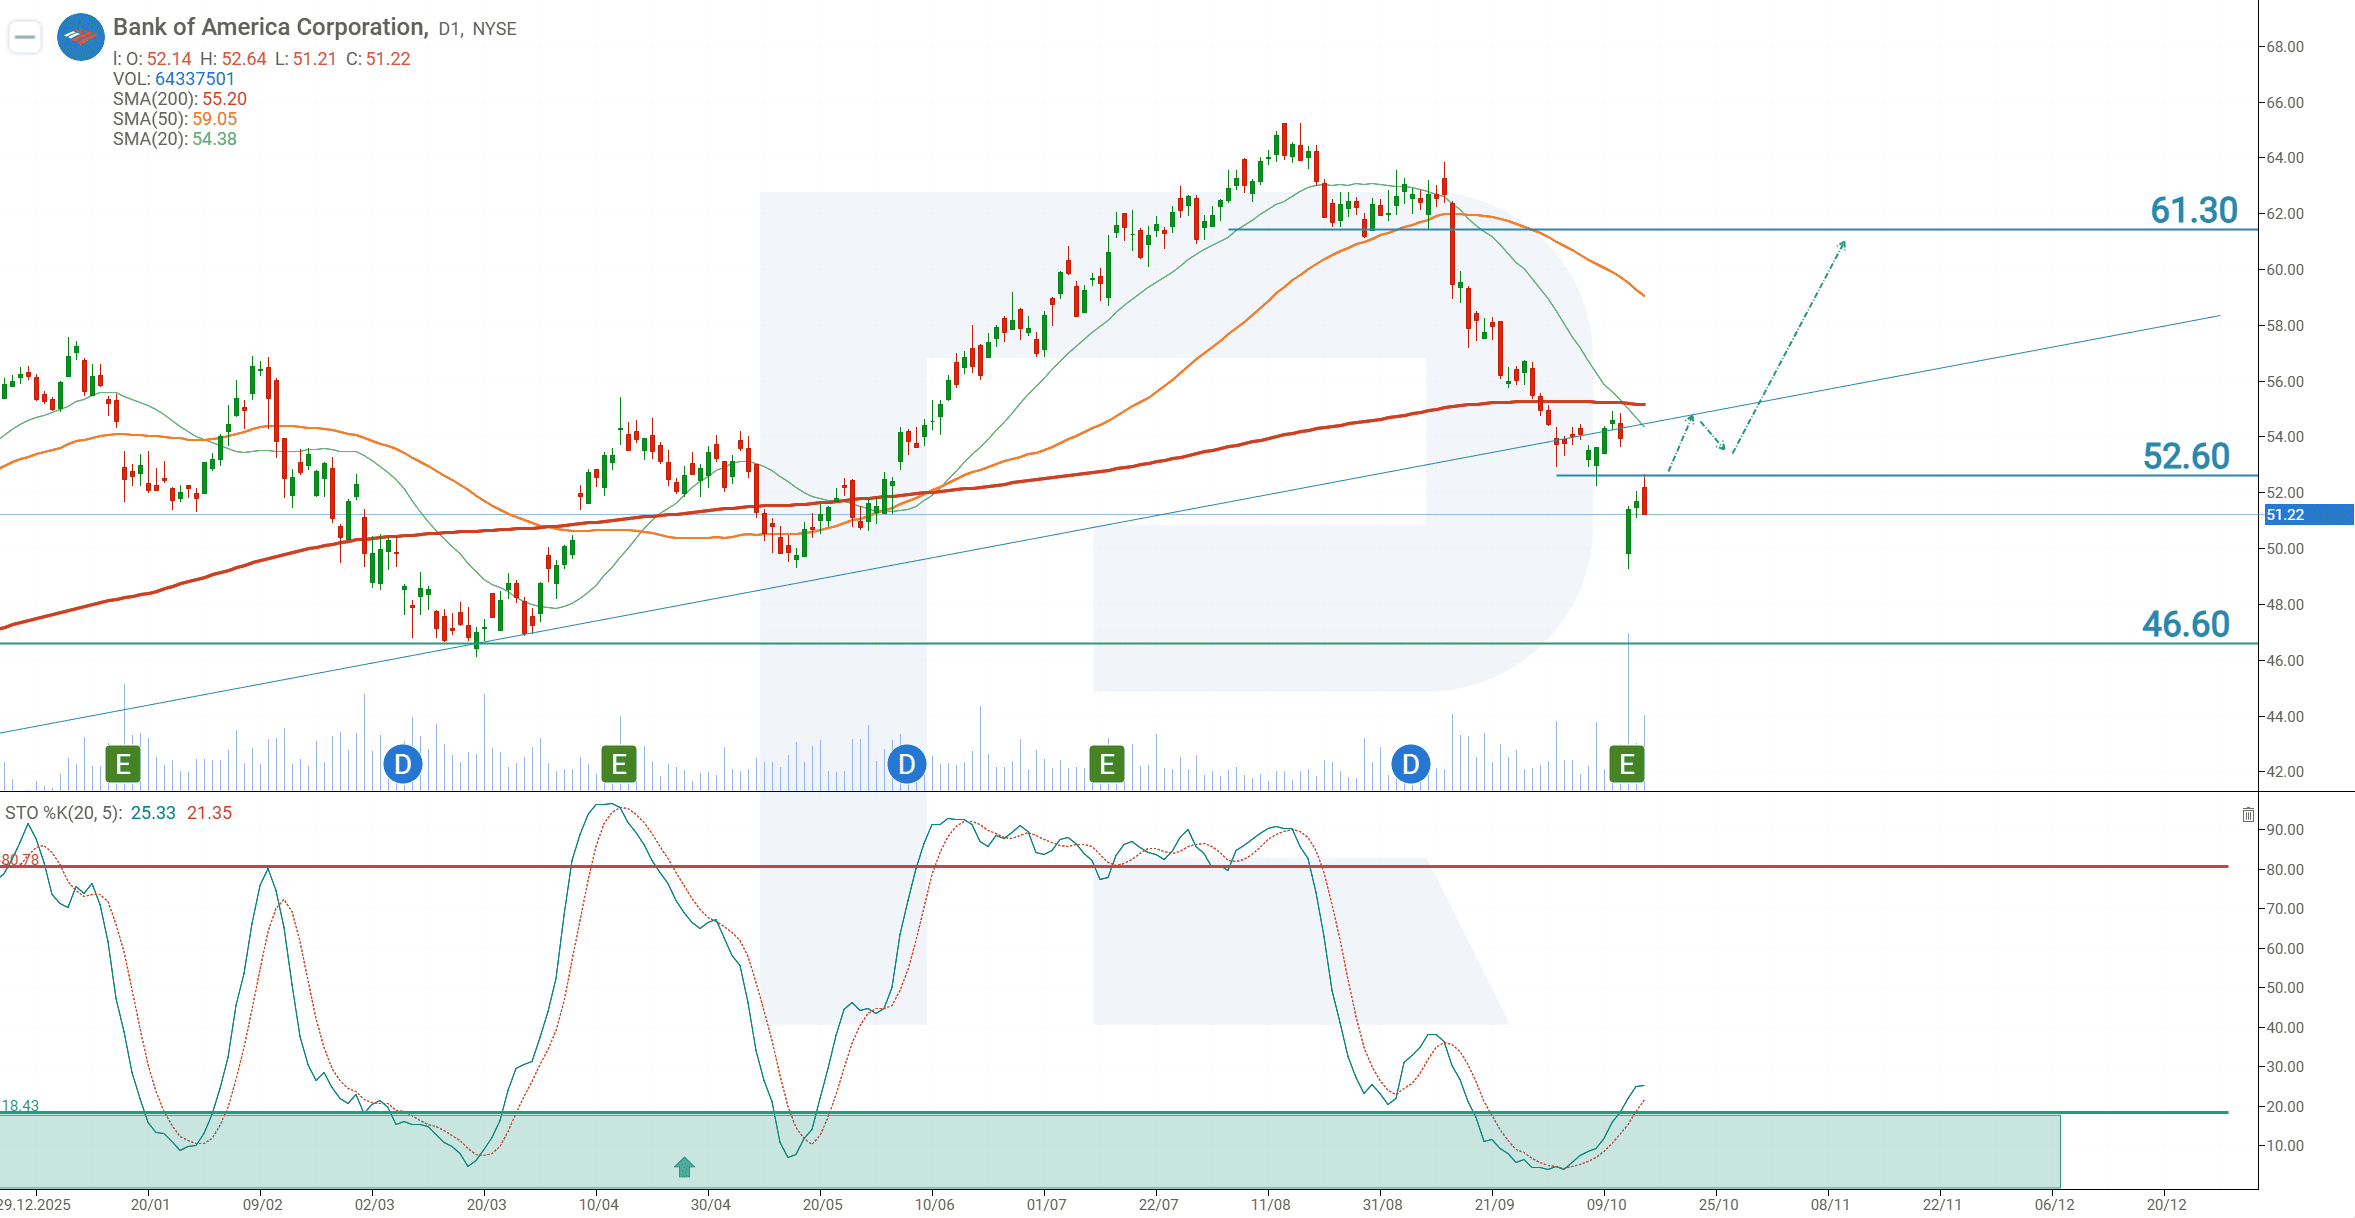
At the time of writing, BAC shares are trading at 51.20 USD.
The current performance of Bank of America shares points to a weakening uptrend. On the daily timeframe, BAC shares have broken below the 200-period Moving Average and consolidated below it, suggesting the market is entering a consolidation phase and may develop a downtrend. In this situation, the Stochastic oscillator is near the oversold zone. If the market enters consolidation, the oscillator’s current position suggests the decline may be ending, with a possible resumption of growth.
However, an analysis of historical data shows that over the past two years, BAC shares have broken below the Moving Average four times but subsequently resumed their advance. A similar pattern could occur again this time. In addition, the bank’s management expects profitability to improve as early as the next quarter, which is positive for the shares.
However, investors should not ignore the technical signals, as they reflect sentiment. This means that buying at the current price is not advisable. A technical signal is needed to confirm that demand for BAC shares has begun to increase, such as a break above resistance. The key resistance level in this case is 52.60 USD.
Therefore, the trading idea for BAC shares is to place a Buy Stop order at 52.80 USD. The Stop Loss should be set at 51.20 USD and the Take Profit at 60.80 USD.
Buy Stop – 52.80
Take Profit – 60.80
Stop Loss – 51.20
Position management rule. Once the price moves 70% of the total distance towards the forecast target, the Stop Loss is set at the entry level. The protective order is then adjusted as the price advances, maintaining a distance of 10%. Position management continues until the position is closed at either the Take Profit or Stop Loss, depending on which level is reached first.
Risks of investing in Bank of America Corporation
stock
Risks of investing in Bank of America Corporation shares include several factors:
Interest rate sensitivity: Bank of America’s profitability is closely tied to interest rates. Rate hikes boost asset returns but also increase the cost of raised deposits, potentially reducing net interest income. If the Federal Reserve begins to lower rates, as some analysts predict, this could negatively impact interest income and BAC stock valuation.
Economic and political uncertainty: a return to the tariff policy under the Trump administration caused market volatility, temporarily increasing trading revenues but also raising uncertainty. Issues in international relations, particularly with China, may affect global markets and reduce BAC’s revenues from international operations.
Lower investment banking revenues: amid uncertainty, market activity in the mergers and acquisitions sector and IPOs has slowed, leading to lower fee income.
Credit risks: increased loan loss provisions suggest the bank expects a possible rise in defaults, particularly on commercial loans. The share of overdue loans is increasing, which could result in write-offs and lower fee income.
Although the Bank of America shows resilience across several areas, investors should consider the above risks as they may exert pressure on the company’s future financial performance.
Ang mga pagtataya na ipinakita sa seksyong ito ay nagpapakita lamang ng pribadong opinyon ng may-akda at hindi dapat ituring bilang gabay para sa pagtetrade. Walang pananagutan ang RoboForex para sa mga resulta ng pagtetrade batay sa mga rekomendasyon sa pagtetrade na inilarawan sa mga analytical review na ito.