
PepsiCo’s international business supports PepsiCo – PEP stock forecast
Despite challenges in North America, PepsiCo’s international business continues to grow, while the company retains its status as a Dividend Aristocrat. PEP stock analysis suggests upside potential towards 145 USD following a break above resistance at 134 USD.
PepsiCo, Inc. (NASDAQ: PEP) ended Q3 2026 with revenue up 5.6% to 25.27 billion USD, exceeding analysts’ expectations. Adjusted earnings per share increased 2% to 2.34 USD, while organic revenue growth accelerated to 3.1% from 2.4% in the previous quarter. The international business remained the main growth driver, while both North American divisions recorded no organic revenue growth.
Despite higher sales, adjusted operating margin declined from 17.3% to 16.9%, indicating that cost pressures persist.
As a result, management lowered its 2026 Core EPS growth forecast to 2.5–3.5%, from its previous expectation of growth near the lower end of the 5–7% range. PepsiCo therefore continues to expand its business, but the recovery in profitability is taking longer than previously expected.
This article examines PepsiCo, Inc.’s business and revenue structure, reviews the company’s quarterly results, and provides a fundamental analysis of PEP. It also presents analysts’ forecasts for PepsiCo shares in 2026 and examines PepsiCo stock performance to provide a PepsiCo, Inc. stock forecast for 2026.
About PepsiCo, Inc.
PepsiCo, Inc. is an American multinational corporation that produces and sells a range of food, soft drinks, and snacks. Its portfolio includes well-known brands such as Cheetos, Gatorade, Lay’s, Mountain Dew, Pepsi, Quaker, and Tropicana. The company was founded in 1965 by merging Thе Pepsi-Сola Company and Frito-Lay. On 13 November 1972, PepsiCo, Inc. went public on the NYSE, and its shares have since traded under the PEP ticker symbol.
PepsiCo, Inc.’s main revenue streams
PepsiCo, Inc. is a US multinational company that produces food, snacks, and non-alcoholic beverages. Its portfolio includes Pepsi, Lay’s, Doritos, Cheetos, Gatorade, Mountain Dew, Quaker, and other well-known brands. The company was formed in 1965 through the merger of Pepsi-Cola and Frito-Lay. PepsiCo shares are traded on the NASDAQ under the ticker PEP.
Since 2025, PepsiCo has reported six main business segments:
- PepsiCo Foods North America (PFNA) – produces and sells snacks, cereals, and other food products in the US and Canada.
- PepsiCo Beverages North America (PBNA) – produces and sells non-alcoholic beverages in North America.
- International Beverages Franchise – the company’s international beverage franchise business, including SodaStream.
- Europe, Middle East and Africa (EMEA) – produces and sells food and beverages across Europe, the Middle East, and Africa.
- Latin America Foods – the company’s food business in Latin American markets.
- Asia Pacific Foods – the company’s food business in the Asia-Pacific region, including India and China.
This structure allows PepsiCo to generate revenue across different markets and reduce its dependence on individual regions. This advantage became particularly evident in 2026, when international divisions continued to increase sales as demand in North America weakened.
PepsiCo, Inc. Q3 2024 financial results
PepsiCo reported its Q3 2024 financial results on 8 October. Below are the key figures from the report:
- Revenue: 23.32 billion USD (−0.6%)
- Net income: 2.93 billion USD (−5.0%)
- Earnings per Share: 2.13 USD (−4.9%)
- Operating profit: 3.87 billion USD (−3.6%)
Revenue by segment:
- Frito-Lay North America: 5.89 billion USD (−1.2%)
- PepsiCo Beverages North America: 7.17 billion USD (+0.1%)
- Quaker Foods North America: 648.00 million USD (−13.2%)
Revenue by region:
- Latin America: 2.91 billion USD (−4.6%)
- Europe: 3.94 billion USD (+6.4%)
- Africa, Middle East, and East Asia: 1.55 billion USD (−6.2%)
- Asia-Pacific: 1.19 billion USD (−1.4%)
PepsiCo’s management noted that the company demonstrates resilience despite challenging conditions. The crucial issues in Q3 were the recall of Quaker products over potential Salmonella contamination and geopolitical tensions in certain international markets.
CEO Ramon Laguarta emphasised that the company has remained profitable thanks to strict cost control and continued investment in its competitiveness. However, considering these challenges, PepsiCo has revised its Q4 and full-year 2024 revenue outlook. Revenue growth is now expected to fall below the previous projection of 4%, while the forecast for EPS growth remains at a minimum of 8%. Nonetheless, PepsiCo retains a positive outlook for the full year 2024.
Although its financial performance declined year-on-year, its stock price rose following the earnings release.
PepsiCo, Inc. Q4 2024 financial results
On 3 February 2025, PepsiCo published its Q4 2024 financial results. The key figures are presented below:
- Revenue: 27.78 billion USD (–0.2%)
- Net income: 1.52 billion USD (+15.4%)
- Earnings per share: 1.11 USD (+18.1%)
- Operating profit: 2.25 billion USD (+33.7%)
Revenue by segment:
- Frito-Lay North America: 7.31 billion USD (–2.1%)
- PepsiCo Beverages North America: 7.91 billion USD (–2.1%)
- Quaker Foods North America: 874.00 million USD (–0.1%)
Revenue by region:
- Latin America: 3.69 billion USD (–6.9%)
- Europe: 4.47 billion USD (+6.2%)
- Africa, Middle East, and East Asia: 2.03 billion USD (+4.9%)
- Asia-Pacific region: 1.48 billion USD (+2.1%)
One of the main factors weighing on the financial results was a shift in consumer preferences, particularly in North America. Lower demand for savoury snacks and beverages affected revenue in these segments. However, management emphasised that the company was actively adapting its product portfolio to emerging trends, including growing consumer interest in healthier food options. In this context, PepsiCo highlighted the successful launch of products such as Pepsi Zero Sugar and SunChips, which reflect changing consumer preferences.
PepsiCo’s 2025 outlook included low-single-digit organic revenue growth and mid-single-digit growth in adjusted earnings per share, reflecting moderate optimism about the company’s future performance. The company also announced a 5% dividend increase and share buybacks, with around 8.6 billion USD in total planned shareholder returns.
PepsiCo, Inc. Q1 2025 financial results
On 24 April 2025, PepsiCo published its Q1 2025 financial results. The key figures are presented below:
- Revenue: 17.92 billion USD (–1.8%)
- Net income: 1.84 billion USD (–10%)
- Earnings per share: 1.33 USD (–10%)
- Operating profit: 2.58 billion USD (–5%)
Revenue by segment:
- International Beverages Franchise: 0.76 billion USD (+3%)
- PepsiCo Beverages North America: 5.87 billion USD (unchanged)
- PepsiCo Foods North America: 6.21 billion USD (–1%)
Revenue by region:
- Europe, Middle East and Africa: 2.39 billion USD (–2%)
- Latin America Foods: 1.67 billion USD (–12%)
- Asia Pacific Foods: 1.02 billion USD (–2%)
PepsiCo’s Q1 2025 results showed how the company was navigating a challenging environment marked by global trade disputes, shifting consumer preferences, and volatile market conditions. Revenue declined 1.8% year-on-year, while earnings per share came in at 1.33 USD, slightly below analysts’ expectations.
A key factor behind the results was the introduction of tariffs, specifically a 10% tariff on imports of soft drink concentrate from Ireland and a 25% tariff on aluminium imports. This increased production costs, putting pressure on margins and prompting the company to revise its 2025 outlook.
For the full 2025 financial year, PepsiCo’s management expected low-single-digit organic revenue growth and approximately flat adjusted earnings per share on a constant-currency basis.
PepsiCo, Inc. Q2 2025 financial results
On 17 July 2025, PepsiCo published its Q2 2025 financial results for the quarter ended 14 June. The key figures are presented below:
- Net revenue: 22.73 billion USD (+1.0%)
- Organic revenue growth: +2.1%
- Net income: 1.26 billion USD (–59%)
- Earnings per share: 0.92 USD (–58%)
- Operating profit: 1.79 billion USD (–56%)
Revenue by segment:
- International Beverages Franchise: 1.39 billion USD (+5%)
- PepsiCo Beverages North America: 6.87 billion USD (+1%)
- PepsiCo Foods North America: 6.32 billion USD (–2%)
Revenue by region:
- Europe, Middle East and Africa: 4.47 billion USD (+7%)
- Latin America Foods: 2.92 billion USD (+6%)
- Asia Pacific Foods: 1.00 billion USD (unchanged)
PepsiCo’s Q2 2025 results came in ahead of market expectations. Organic revenue grew 2% year-on-year, while GAAP EPS fell to 0.92 USD due to a one-off 1.86 billion USD impairment of intangible assets related to the Rockstar and Be & Cheery brands. In terms of the growth mix, pricing remained the main contributor, while overall volumes remained weak.
In North America, the previously expected improvement did not materialise. The food business recorded a 2% year-on-year organic revenue decline due to weak volumes. North American beverages grew 1%, with sequential volume improvement and market share gains for Pepsi and Pepsi Zero Sugar. Performance was stronger outside the US. International Beverages Franchise grew 5%, while the overall international beverage business grew 9%, supported by resilient demand in Mexico, Brazil, Germany, Poland, France, Egypt, Türkiye, Saudi Arabia, Pakistan, and Thailand.
The company reaffirmed its 2025 outlook, expecting low-single-digit organic revenue growth and approximately flat Core EPS on a constant-currency basis. With currency headwinds easing, the expected negative foreign exchange impact for the year was reduced to –1.5 percentage points from the previously expected –3 percentage points, improving the outlook for Core EPS in USD. Capital return plans remained unchanged at 8.6 billion USD for the year, comprising 7.6 billion USD in dividends and 1.0 billion USD in share buybacks. Management remained focused on restoring growth in North America by emphasising value propositions, simplifying the portfolio, and advancing the One North America initiative, while also accounting for potential additional supply chain costs and tariff risks, which it expected to offset through productivity improvements and revenue management.
PepsiCo, Inc. Q3 2025 financial results
On 9 October, PepsiCo published its Q3 2025 financial results for the quarter ended 6 September, which came in ahead of expectations. The key figures are presented below:
- Net revenue: 23.94 billion USD (+2.6%)
- Organic revenue growth: +1.3%
- Net income: 2.60 billion USD (–11%)
- Earnings per share: 1.90 USD (–11%)
- Operating profit: 3.57 billion USD (–8%)
Revenue by segment:
- International Beverages Franchise: 1.29 billion USD (unchanged)
- PepsiCo Beverages North America: 7.32 billion USD (+2%)
- PepsiCo Foods North America: 6.53 billion USD (unchanged)
Revenue by region:
- Europe, Middle East and Africa: 5.02 billion USD (+9%)
- Latin America Foods: 2.66 billion USD (+2%)
- Asia Pacific Foods: 1.12 billion USD (+2%)
In Q3 2025, PepsiCo’s revenue rose 2.6% year-on-year to 23.94 billion USD, while adjusted earnings per share reached 2.29 USD, exceeding analysts’ expectations. However, organic revenue growth was just 1.3%, indicating that the company continued to face challenges in growing sales in its core business. International divisions remained the main growth driver, offsetting weak performance in North America.
Performance across segments was mixed. Sales volumes declined at Frito-Lay North America, while price increases only partially offset weak demand. PepsiCo Beverages North America performed better, supported by sales growth in Gatorade, Mountain Dew, and Zero Sugar.
The international business remained the main growth driver. Revenue in Latin America increased 2%, while Europe remained at the previous year’s level. AMEA delivered strong growth, particularly in India, Saudi Arabia, and China.
PepsiCo maintained its cautious full-year outlook, expecting low-single-digit organic revenue growth and approximately flat earnings per share on a constant-currency basis. At the same time, the expected negative foreign exchange impact narrowed from –1.5 to –0.5 percentage points, meaning Core EPS for 2025 could decline by just 0.5%, an improvement on previous expectations.
PepsiCo, Inc. Q4 2025 financial results
On 3 February, PepsiCo published its Q4 2025 financial results for the quarter ended 27 December, which came in ahead of expectations. The key figures are presented below:
- Net revenue: 29.34 billion USD (+5.6%)
- Organic revenue growth: +2.1%
- Net income: 2.54 billion USD (+67%)
- Earnings per share: 1.85 USD (+68%)
- Operating profit: 3.56 billion USD (+58%)
Revenue by segment:
- International Beverages Franchise: 1.58 billion USD (+2%)
- PepsiCo Beverages North America: 8.20 billion USD (+2%)
- PepsiCo Foods North America: 8.31 billion USD (–1%)
Revenue by region:
- Europe, Middle East and Africa: 6.08 billion USD (+5%)
- Latin America Foods: 3.68 billion USD (+5%)
- Asia Pacific Foods: 1.49 billion USD (+4%)
PepsiCo’s results came in ahead of analysts’ expectations and showed moderately strong performance. Revenue reached 29.34 billion USD, above the forecast of 28.96 billion USD, while adjusted earnings per share (Core EPS ) came in at 2.26 USD, above the expected 2.24 USD. Revenue growth accelerated, supported by improved sales across key divisions, favourable foreign exchange movements, and acquired brands, including Siete and Poppi. Organic revenue increased 2.1%, indicating a moderate recovery in sales.
In 2026, management planned to increase advertising spending to stimulate demand. For the year, management forecast organic revenue growth of 2–4%, Core EPS growth of 4–6% on a constant-currency basis, and Core EPS growth of 5–7% including the impact of foreign exchange movements. The company also announced a 4% increase in its annual dividend, marking its 54th consecutive year of dividend increases.
PepsiCo, Inc. Q1 2026 financial results
On 16 April, PepsiCo published its Q1 2026 financial results for the quarter ended 21 March. The key figures are presented below:
- Net revenue: 19.44 billion USD (+8.5%)
- Organic revenue growth: +2.6%
- Net income: 2.33 billion USD (+27%)
- Earnings per share: 1.70 USD (+27%)
- Operating profit: 3.21 billion USD (+24%)
Revenue by segment:
- International Beverages Franchise: 0.82 billion USD (+9%)
- PepsiCo Beverages North America: 6.39 billion USD (+9%)
- PepsiCo Foods North America: 6.33 billion USD (+2%)
Revenue by region:
- Europe, Middle East and Africa: 2.82 billion USD (+18%)
- Latin America Foods: 1.93 billion USD (+16%)
- Asia Pacific Foods: 1.14 billion USD (+11%)
PepsiCo’s Q1 2026 results exceeded market expectations. Revenue reached 19.44 billion USD, up from the 18.94 billion USD forecast, while adjusted earnings per share came in at 1.61 USD, above the consensus estimate of 1.55 USD.
Organic revenue grew 2.6%, confirming resilient demand.
Management reaffirmed its full-year outlook, expecting organic revenue growth of 2–4% and net revenue growth of 4–6%. Core EPS growth, including the impact of foreign exchange movements, was forecast at 5–7%. The company also planned to return 8.9 billion USD to shareholders, comprising 7.9 billion USD in dividends and 1 billion USD in share buybacks.
PepsiCo, Inc. Q2 2026 financial results
On 9 July, PepsiCo published its Q2 2026 financial results for the quarter ended 13 June. The key figures are presented below:
- Net revenue: 24.18 billion USD (+6.4%)
- Organic revenue growth: +2.4%
- Net income: 2.98 billion USD (+136%)
- Earnings per share: 2.18 USD (+137%)
- Operating profit: 4.02 billion USD (+125%)
Revenue by segment:
- International Beverages Franchise: 1.52 billion USD (+11%)
- PepsiCo Beverages North America: 7.24 billion USD (+7%)
- PepsiCo Foods North America: 6.37 billion USD (–2%)
Revenue by region:
- Europe, Middle East and Africa: 4.98 billion USD (+10%)
- Latin America Foods: 2.94 billion USD (+15%)
- Asia Pacific Foods: 1.12 billion USD (+12%)
PepsiCo’s Q2 2026 results were mixed. Revenue rose 6.4% to 24.18 billion USD, exceeding the market forecast of around 23.97 billion USD. Adjusted earnings came in at 2.20 USD per share, compared with the consensus estimate of 2.21 USD. Organic revenue grew 2.4%, while foreign exchange movements contributed about 2.2 percentage points to total revenue growth, and acquisitions and divestitures added another 1.8 percentage points.
The international business remained the main growth driver, with particularly strong performance in Asia, where food sales volumes increased 10%. Performance in North America remained weaker: Foods North America revenue declined 2%, while sales volumes were virtually unchanged. In Beverages North America, organic revenue grew just 1%, while beverage sales volumes declined 4%.
PepsiCo, Inc. Q3 2026 financial results
On 8 October, PepsiCo published its Q3 2026 financial results for the quarter ended 5 September. The key figures are presented below:
- Net revenue: 25.27 billion USD (+5.6%)
- Organic revenue growth: +3.1%
- Net income: 3.07 billion USD (+17%)
- Earnings per share: 2.23 USD (+17%)
- Operating profit: 4.26 billion USD (+19%)
Revenue by segment:
- International Beverages Franchise: 1.40 billion USD (+8%)
- PepsiCo Beverages North America: 7.71 billion USD (+5%)
- PepsiCo Foods North America: 6.50 billion USD (0%)
Revenue by region:
- Europe, Middle East and Africa: 5.41 billion USD (+8%)
- Latin America Foods: 3.02 billion USD (+14%)
- Asia Pacific Foods: 1.23 billion USD (+10%)
PepsiCo’s Q3 2026 results showed improving sales but also confirmed that profitability was recovering more slowly than expected. Revenue rose 5.6% year-on-year to 25.27 billion USD, exceeding analysts’ forecasts. Adjusted earnings per share came in at 2.34 USD, up just 2%. Organic revenue, which excludes the impact of foreign exchange movements and acquisitions, grew 3.1%, compared with 2.4% in the previous quarter. This indicates a gradual acceleration in the core business.
International markets remained the main growth driver. Demand was particularly strong in Asia, where food sales volumes increased 11%. The international business therefore continued to expand, helping PepsiCo offset weak performance in North America.
Conditions in the US market were considerably more challenging. PepsiCo Foods North America revenue was virtually unchanged at 6.50 billion USD. Sales volumes remained at the previous year’s level, even though the company had lowered prices on some popular products, including Lay’s and Doritos, to win back customers. PepsiCo Beverages North America revenue increased 5% to 7.71 billion USD, although this was driven primarily by acquisitions. Organic revenue was virtually unchanged, while beverage sales volumes declined 2%. This indicates that the problem of weak consumer demand has not yet been resolved.
Declining profitability remained another challenge. Despite higher revenue, PepsiCo’s adjusted operating margin fell from 17.3% to 16.9%. Rising raw material, production, logistics, and advertising costs continued to put pressure on the business. The company was already implementing a cost-cutting program, but the savings were not yet sufficient to fully offset the increase in costs. As a result, adjusted operating profit grew just 3%, significantly slower than revenue. GAAP operating profit, meanwhile, increased 19%, primarily due to the favourable impact of certain one-off factors.
Management acknowledged that the North American business recovery would take longer than previously expected. PepsiCo planned further cost reductions and optimisation of its production and product portfolio, while increasing investment in brand promotion and new product development. However, the report’s main negative development was the downgrade to the company’s 2026 earnings outlook. PepsiCo now expected Core EPS growth of 2.5–3.5%, compared with its previous forecast of growth near the lower end of the 5–7% range. On a constant-currency basis, the Core EPS growth forecast was lowered to 1–2% from the lower end of the 4–6% range. The company also forecast organic revenue growth of around 3% and total revenue growth of around 6%.
Overall, PepsiCo’s results show that the company can still grow sales but has yet to translate that growth into a comparable increase in profit. International business continues to perform strongly, while North American sales volumes remain weak and costs continue to weigh on margins.
Fundamental analysis of PEP and key drivers of PepsiCo, Inc. stock
In 2026, the outlook for PepsiCo shares largely depends on a recovery in North American sales and the company’s ability to improve profitability. Despite sustained growth in its international divisions, the US market remains the main source of challenges. Three key indicators can be used to assess how successfully PepsiCo is addressing these issues:
- PepsiCo Foods North America Organic Revenue Growth
- PepsiCo Beverages North America Organic Revenue Growth
- Core Operating Margin
PepsiCo Foods North America Organic Revenue Growth shows the sales performance of snacks and other food products in North America, excluding the impact of foreign exchange movements and acquisitions. This helps assess whether PepsiCo’s core business is recovering after a prolonged demand slowdown.
PepsiCo Beverages North America Organic Revenue Growth shows the sales performance of beverages in North America, excluding the impact of acquisitions and foreign exchange movements. This indicator is particularly important for PepsiCo because the division’s total revenue may increase as a result of new brand acquisitions even if sales in the existing business show little growth.
Core Operating Margin shows the proportion of revenue PepsiCo retains as operating profit after excluding certain one-off factors. This indicator helps assess the effectiveness of the company’s cost-cutting program.
The most favourable scenario for PepsiCo shares therefore involves a simultaneous recovery in food and beverage sales in North America and an improvement in operating margin. In this case, the company could not only increase revenue but also accelerate adjusted earnings growth, creating a stronger fundamental basis for PEP shares to rise.
If demand remains weak and margins continue to decline, even successful cost reductions may not be sufficient to support a sustained recovery in the shares.
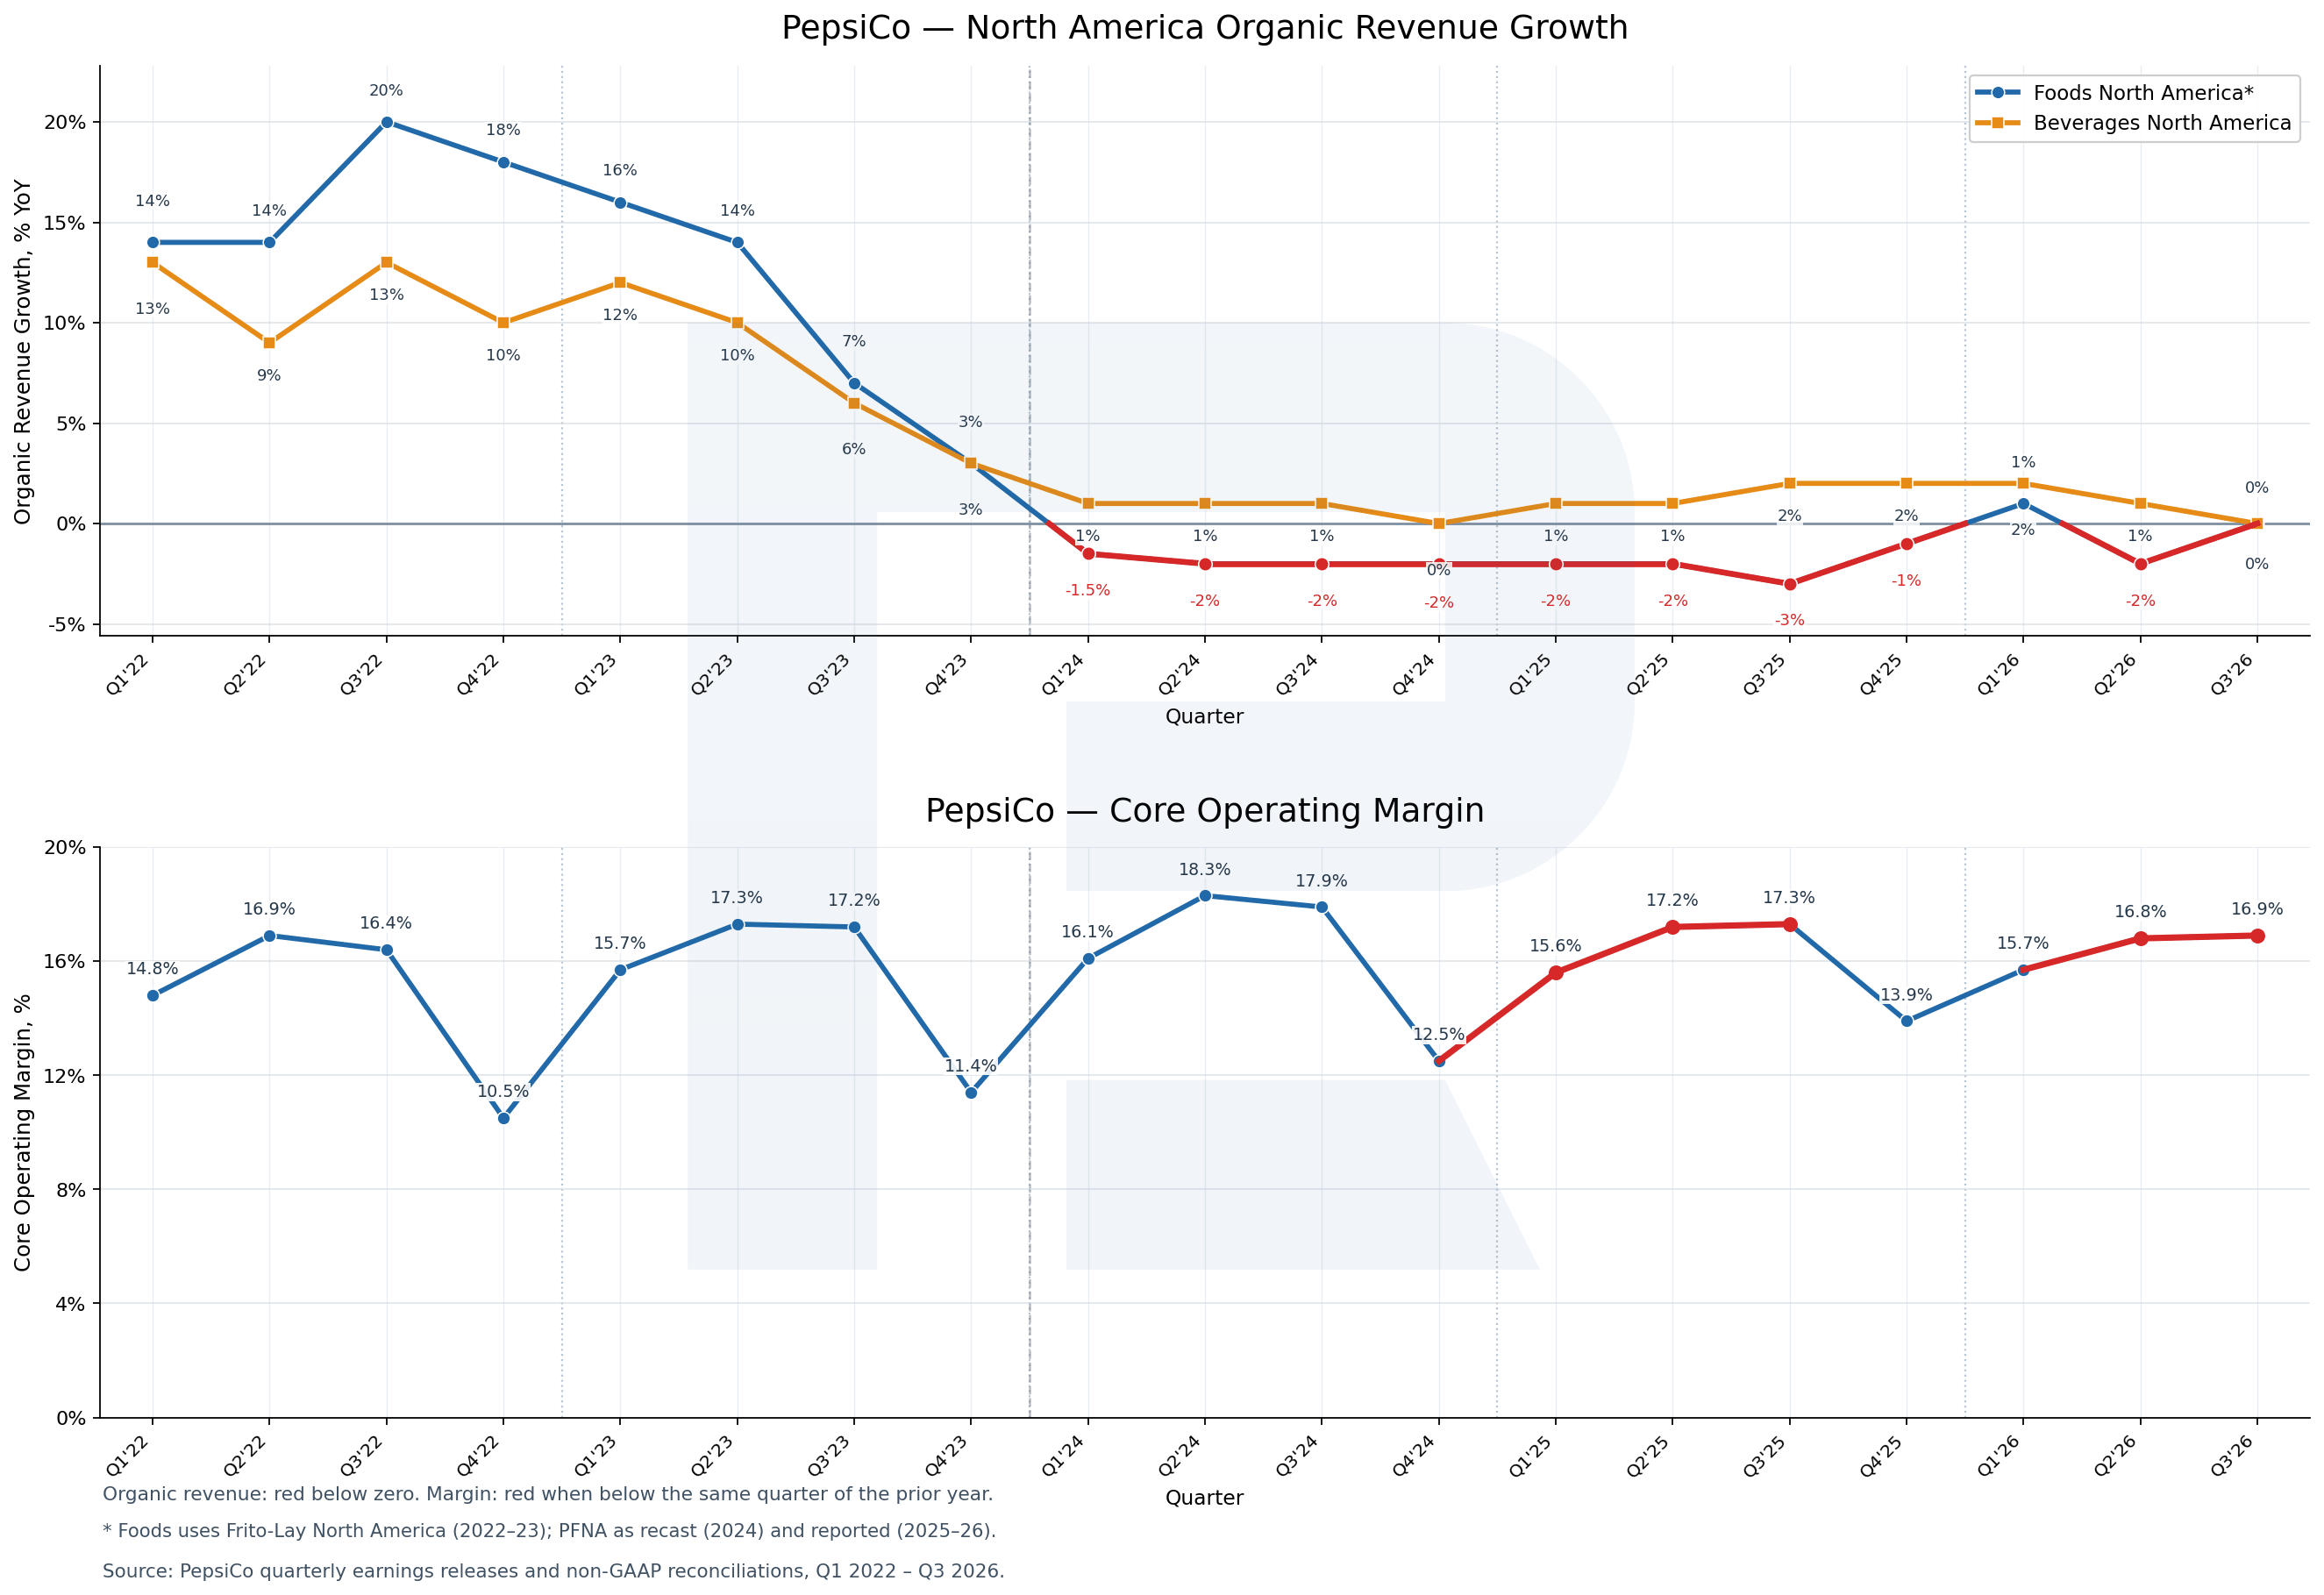
The charts show that PepsiCo has not yet achieved a sustained recovery in North American sales. Following strong growth in 2022–2023, revenue at PepsiCo Foods North America has virtually stopped growing. Early signs suggest improving demand for snacks, but price reductions on certain products have not yet helped the company return to revenue growth.
PepsiCo Beverages North America's performance looks better. However, a significant portion of the growth is related to acquisitions of new brands. Organic revenue was virtually unchanged in Q3, suggesting the core beverage business still faces demand challenges and that higher revenue does not yet signal a full sales recovery.
Profitability also raises additional concerns. After improving in early 2026, Core Operating Margin came under pressure again. The company is cutting costs and improving production efficiency, but rising raw material, logistics, and marketing costs have so far prevented profitability from improving sustainably.
Overall, PepsiCo’s fundamentals suggest the company is still stabilising sales in North America. Organic revenue at its two largest divisions has virtually stopped growing, while operating margin remains under pressure. Early signs of improving demand have emerged, but have yet to translate into faster earnings growth.
However, weak performance in North America does not mean PepsiCo faces a company-wide crisis. Its international divisions continue to expand, supporting overall revenue growth. The company also continues to generate positive free cash flow and can maintain dividend payments. In 2026, PepsiCo increased its dividend for the 54th consecutive year, reaffirming its status as a Dividend Aristocrat.
The most favourable scenario for PEP shares therefore remains a recovery in organic sales growth in North America alongside an improvement in Core Operating Margin. In this case, the international business would continue to support the company’s financial performance. At the same time, improved performance in its North American divisions could accelerate earnings growth and provide a fundamental basis for the shares to rise.
Expert forecasts for PepsiCo, Inc. stock for 2026
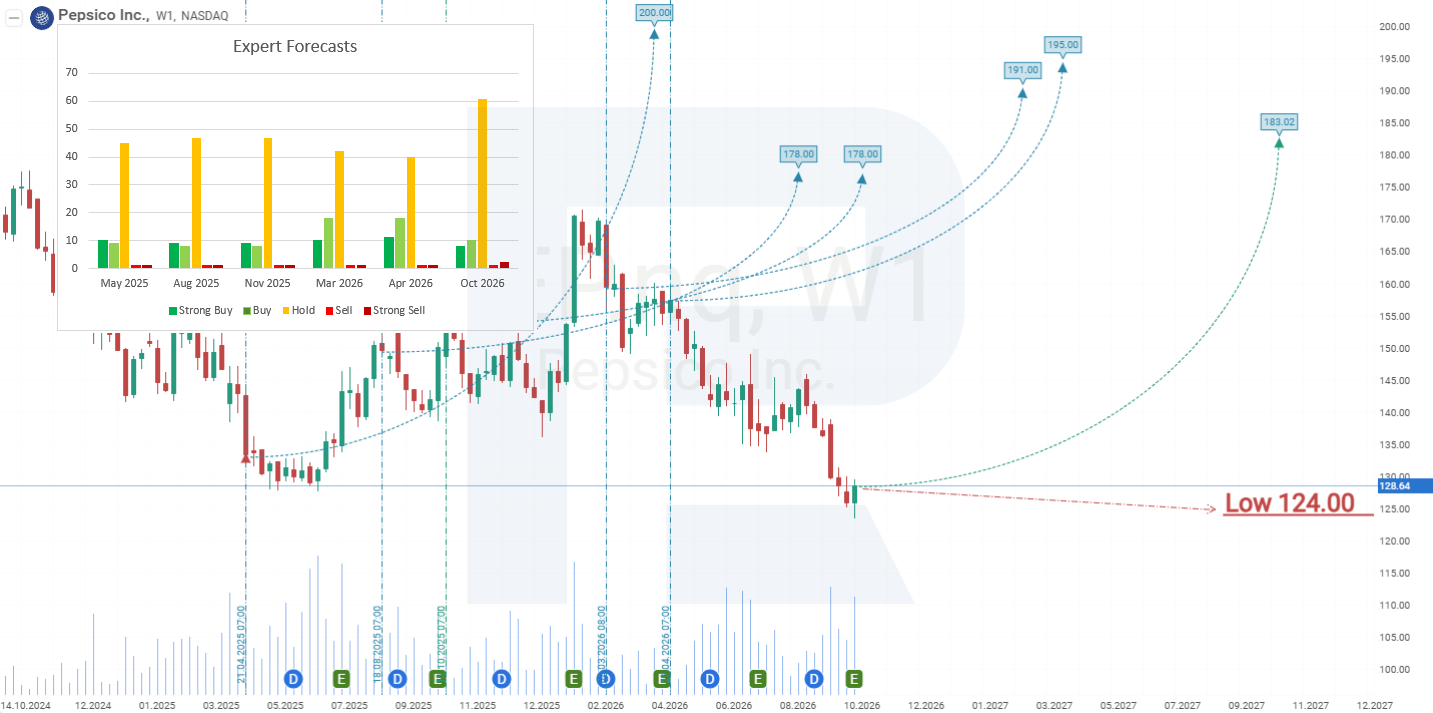
The analyst forecasts below are for the next 12 months. The upper and lower limits represent the most optimistic and pessimistic forecasts, respectively. These estimates may change following the release of the company’s new financial results.
- Barchart : 5 of 23 analysts rated PepsiCo shares as Strong Buy, 17 as Hold, and 1 as Strong Sell. The highest price target is 180 USD, while the lowest is 124 USD.
- MarketBeat : 5 of 20 analysts rated the shares as Buy, 14 as Hold, and 1 as Sell. The highest price target is 183 USD, while the lowest is 132 USD.
- TipRanks : 3 of 15 analysts rated the shares as Buy and 12 as Hold. The highest price target is 176 USD, while the lowest is 133 USD.
- Stock Analysis : 3 of 24 analysts rated the shares as Strong Buy, 2 as Buy, 18 as Hold, and 1 as Strong Sell. The highest price target is 169 USD, while the lowest is 124 USD.
PepsiCo, Inc. stock price forecast for 2026
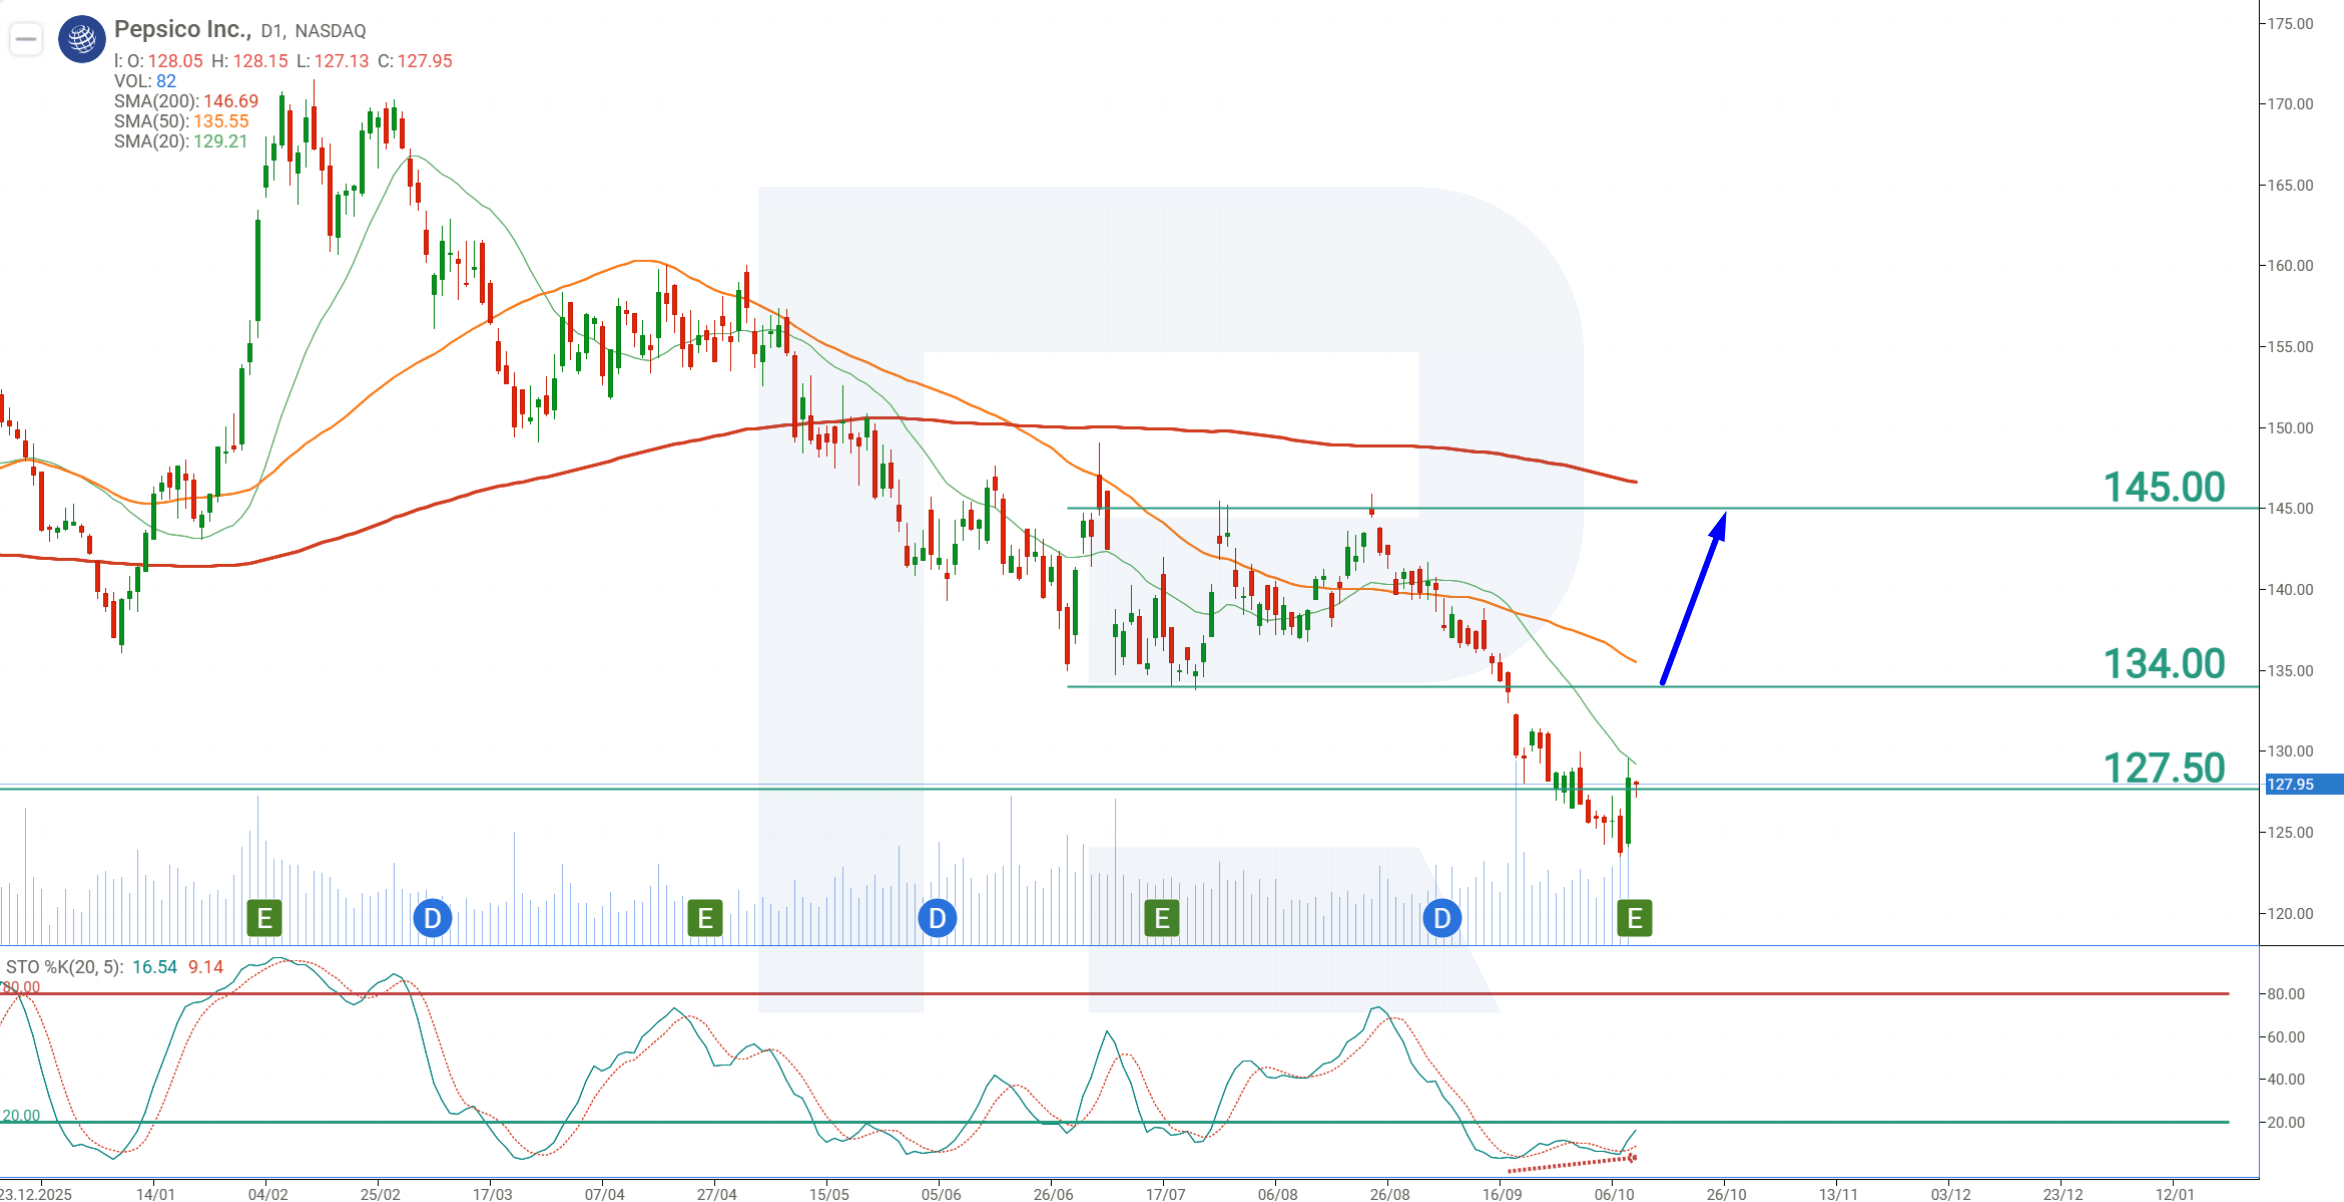
At the time of writing, PEP shares are trading at 128 USD.
On the daily timeframe, PEP shares are trading below the 200-period moving average, indicating that the downtrend remains dominant. However, the Stochastic oscillator is deep in oversold territory, while the bullish convergence that has formed signals the potential for a corrective rise. Further support for a recovery comes from the false break of support at 127.50 USD, which was accompanied by an increase in trading volumes. This indicates the presence of buyers when the price falls below 127 USD.
Fundamental analysis of PepsiCo shares shows that the company is struggling to restore sales growth in North America, while its international business continues to expand. At the same time, PepsiCo continues to generate positive free cash flow, allowing it to fund business development and maintain dividend payments. This is particularly important for investors focused on dividend income. Some shareholders may therefore view the current decline in the share price as an opportunity to increase their positions at a more attractive price.
The combination of PepsiCo’s fundamental resilience, oversold Stochastic readings, and signs of buying interest near support therefore creates the conditions for a corrective rise in PEP shares. However, given the prevailing downtrend, opening a long position before confirmation of a reversal would be premature. A break above resistance at 134 USD could provide such a signal, indicating strengthening buying activity.
The PEP trading idea involves placing a Buy Stop order at 135 USD following a break above resistance. The target for the corrective rise is 145 USD, where the Take Profit is set. The Stop Loss is placed at 126 USD. A move back below 126.50 USD would indicate weakening buying interest and increase the likelihood of the downtrend continuing.
Buy Stop – 135.00
Take Profit – 145.00
Stop Loss – 126.00
Position management rule. Once the price moves 70% of the total distance towards the forecast target, the Stop Loss is set at the entry level. The protective order is then adjusted as the price advances, maintaining a distance of 5%. Position management continues until the position is closed at either the Take Profit or Stop Loss, whichever is reached first.
Ang mga pagtataya na ipinakita sa seksyong ito ay nagpapakita lamang ng pribadong opinyon ng may-akda at hindi dapat ituring bilang gabay para sa pagtetrade. Walang pananagutan ang RoboForex para sa mga resulta ng pagtetrade batay sa mga rekomendasyon sa pagtetrade na inilarawan sa mga analytical review na ito.