
Daily technical analysis and forecast for 14 September 2026
Daily technical analysis and forecast for EURUSD, USDJPY, GBPUSD, AUDUSD, USDCAD, XAUUSD, US 500, and BTCUSD for 14 September 2026.
Each scenario on this page reflects the market structure on the H4 chart as of 10:00 UTC+3 on 14 September 2026. The assessment considers the current H4 chart structure, key support and resistance levels, the direction of the medium-term movement, and the prevailing fundamental backdrop.
EURUSD forecast
As of 14 September 2026, EURUSD is trading under the influence of two opposing factors: a more hawkish European Central Bank stance and, at the same time, stronger expectations of a Federal Reserve rate hike. The ECB raised its policy rate by 25 basis points on 10 September and indicated that further tightening remains possible because of accelerating inflation and rising energy costs. Eurozone inflation above 3% in August is providing additional support to the euro, although the effect is being limited by weaker risk appetite and a strong dollar. In the US, the Consumer Price Index rose by 0.4% month-on-month and 3.4% year-on-year in August, increasing the probability of a Fed rate hike as early as this week’s meeting. The yield on 10-year US Treasuries remains near 5%, while a surge in Brent prices above 107 USD per barrel is supporting inflation risks and demand for the dollar.
Geopolitics also remains in focus: risks to oil supplies through the Strait of Hormuz and the Bab el-Mandeb area are raising fuel costs and supporting global bond yields. For the euro, this is a mixed factor: higher inflation increases the likelihood of further ECB action, but at the same time worsens the growth outlook for the energy-importing eurozone. Volatility also remains high. Overall, the fundamental backdrop for EURUSD at the start of the week remains mixed, but the US currency retains the advantage, particularly ahead of the Fed decision.
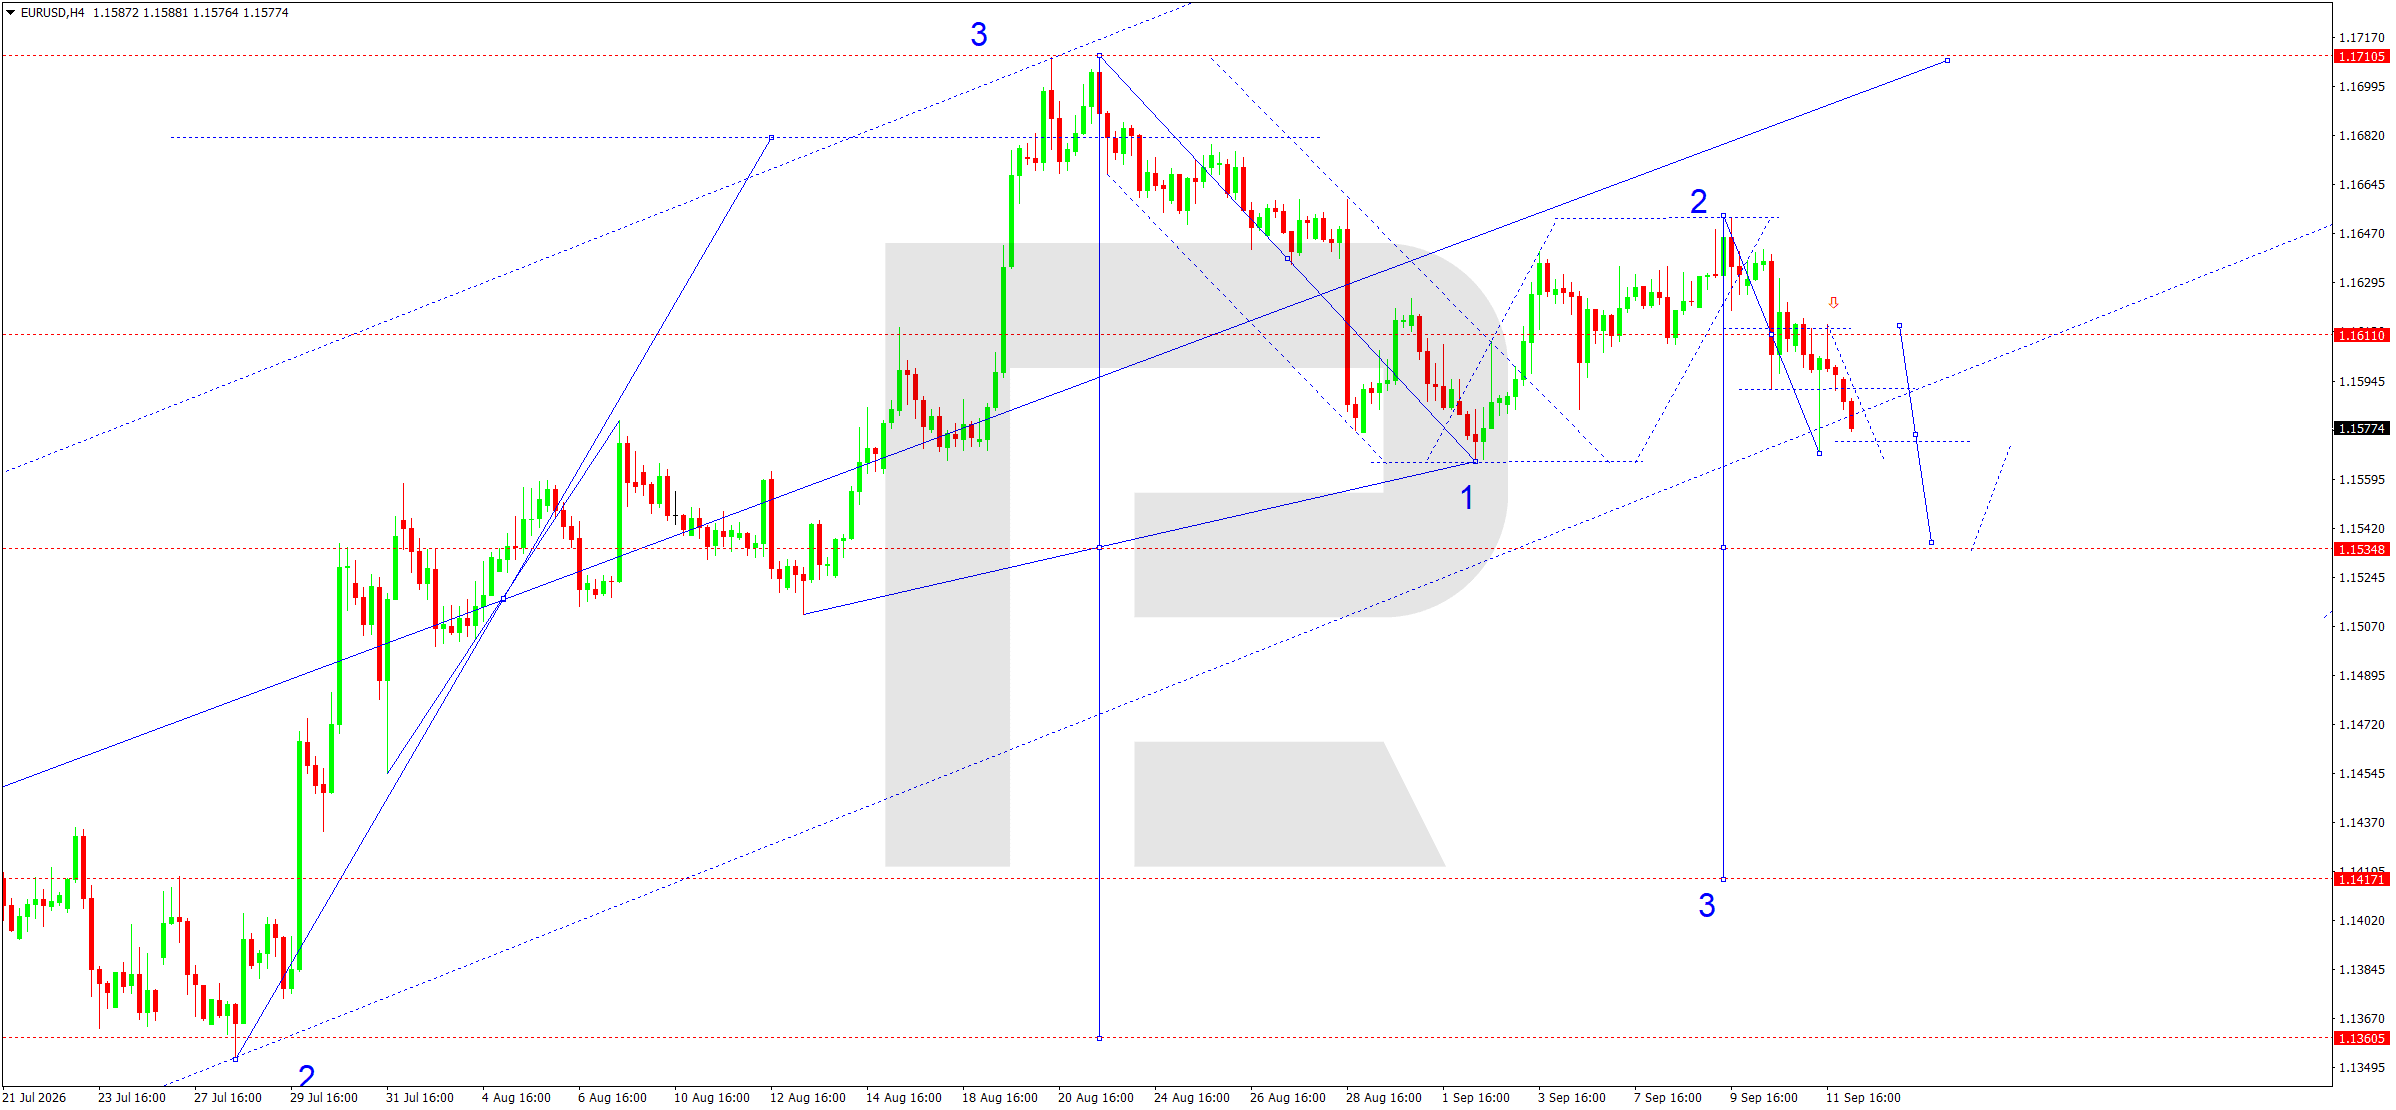
On the H4 chart, after a correction towards 1.1610, the market formed a downward impulse and set a new local low around 1.1564. The current structure is consistent with the development of the third downward wave, so the main scenario for 14 September is a continued decline after a possible brief return towards the 1.1590–1.1610 area. The nearest target is 1.1538, where a crucial support zone and the lower part of the current Price Envelope are located. A breakout below 1.1538 would create room for a move towards 1.1420 and, in the longer term, towards 1.1360.
The wave matrix, with a pivot around 1.1648, confirms this structure. While the price remains below this level and below the local descending resistance line, selling remains the priority. A return above 1.1610 could temporarily slow the decline, but only consolidation above 1.1648 would indicate a weakening of the current bearish scenario. For the next session, the market is expected to attempt to stabilise within the 1.1560–1.1600 range before breaking lower. From a wave perspective, the completion of the second corrective wave around 1.1640–1.1650 increases the probability of an acceleration in the third wave once the nearest support level is broken. The SMA and channel slope also indicate persistent selling pressure. The main H4 trend remains bearish, with 1.1538 viewed as the first target and 1.1420 as the next target of the third wave.
EURUSD forecast scenario
Trading scenario: SELL
- Price at the time of writing: 1.1535
- Entry price: 1.1530
- Stop loss: 1.1615
- Take profit: 1.1420
- Risk-to-reward ratio: 1:1.3
The trade idea is valid until 8:00 AM on 15 September 2026 (server time, UTC+3).
USDJPY forecast
As of 14 September 2026, the fundamental backdrop for USDJPY is being shaped by expectations surrounding decisions from two central banks. The Federal Reserve will hold its meeting in the middle of the week, and after August inflation accelerated, the market is pricing in a roughly 86–87% probability of a rate hike. The US Consumer Price Index rose by 0.4% month-on-month and 3.4% year-on-year, while the yield on 10-year US Treasuries remains close to 5%. These factors support the dollar. At the same time, the Bank of Japan will conclude its meeting on Friday, and the market expects a 25-basis-point rate increase. The yen has already strengthened by around 4% since the start of the month and is trading near seven-month highs against the dollar. Imported inflation risks from expensive oil and the yen’s weakness in previous months remain another argument in favour of a more hawkish BoJ stance. Brent above 107 USD per barrel is increasing inflationary pressure and weakening global risk appetite at the same time, which traditionally can support the Japanese currency.
Following the yen’s recent appreciation, market participants are also sensitive to the risk of FX intervention and capital repatriation by Japanese investors. At the same time, even high US bond yields are no longer providing the same persistent support to USDJPY, as expectations of Japanese monetary-policy normalisation have strengthened significantly. As a result, the fundamental balance for the pair remains two-sided, but expectations of BoJ tightening and safe-haven demand are giving the yen a local advantage.
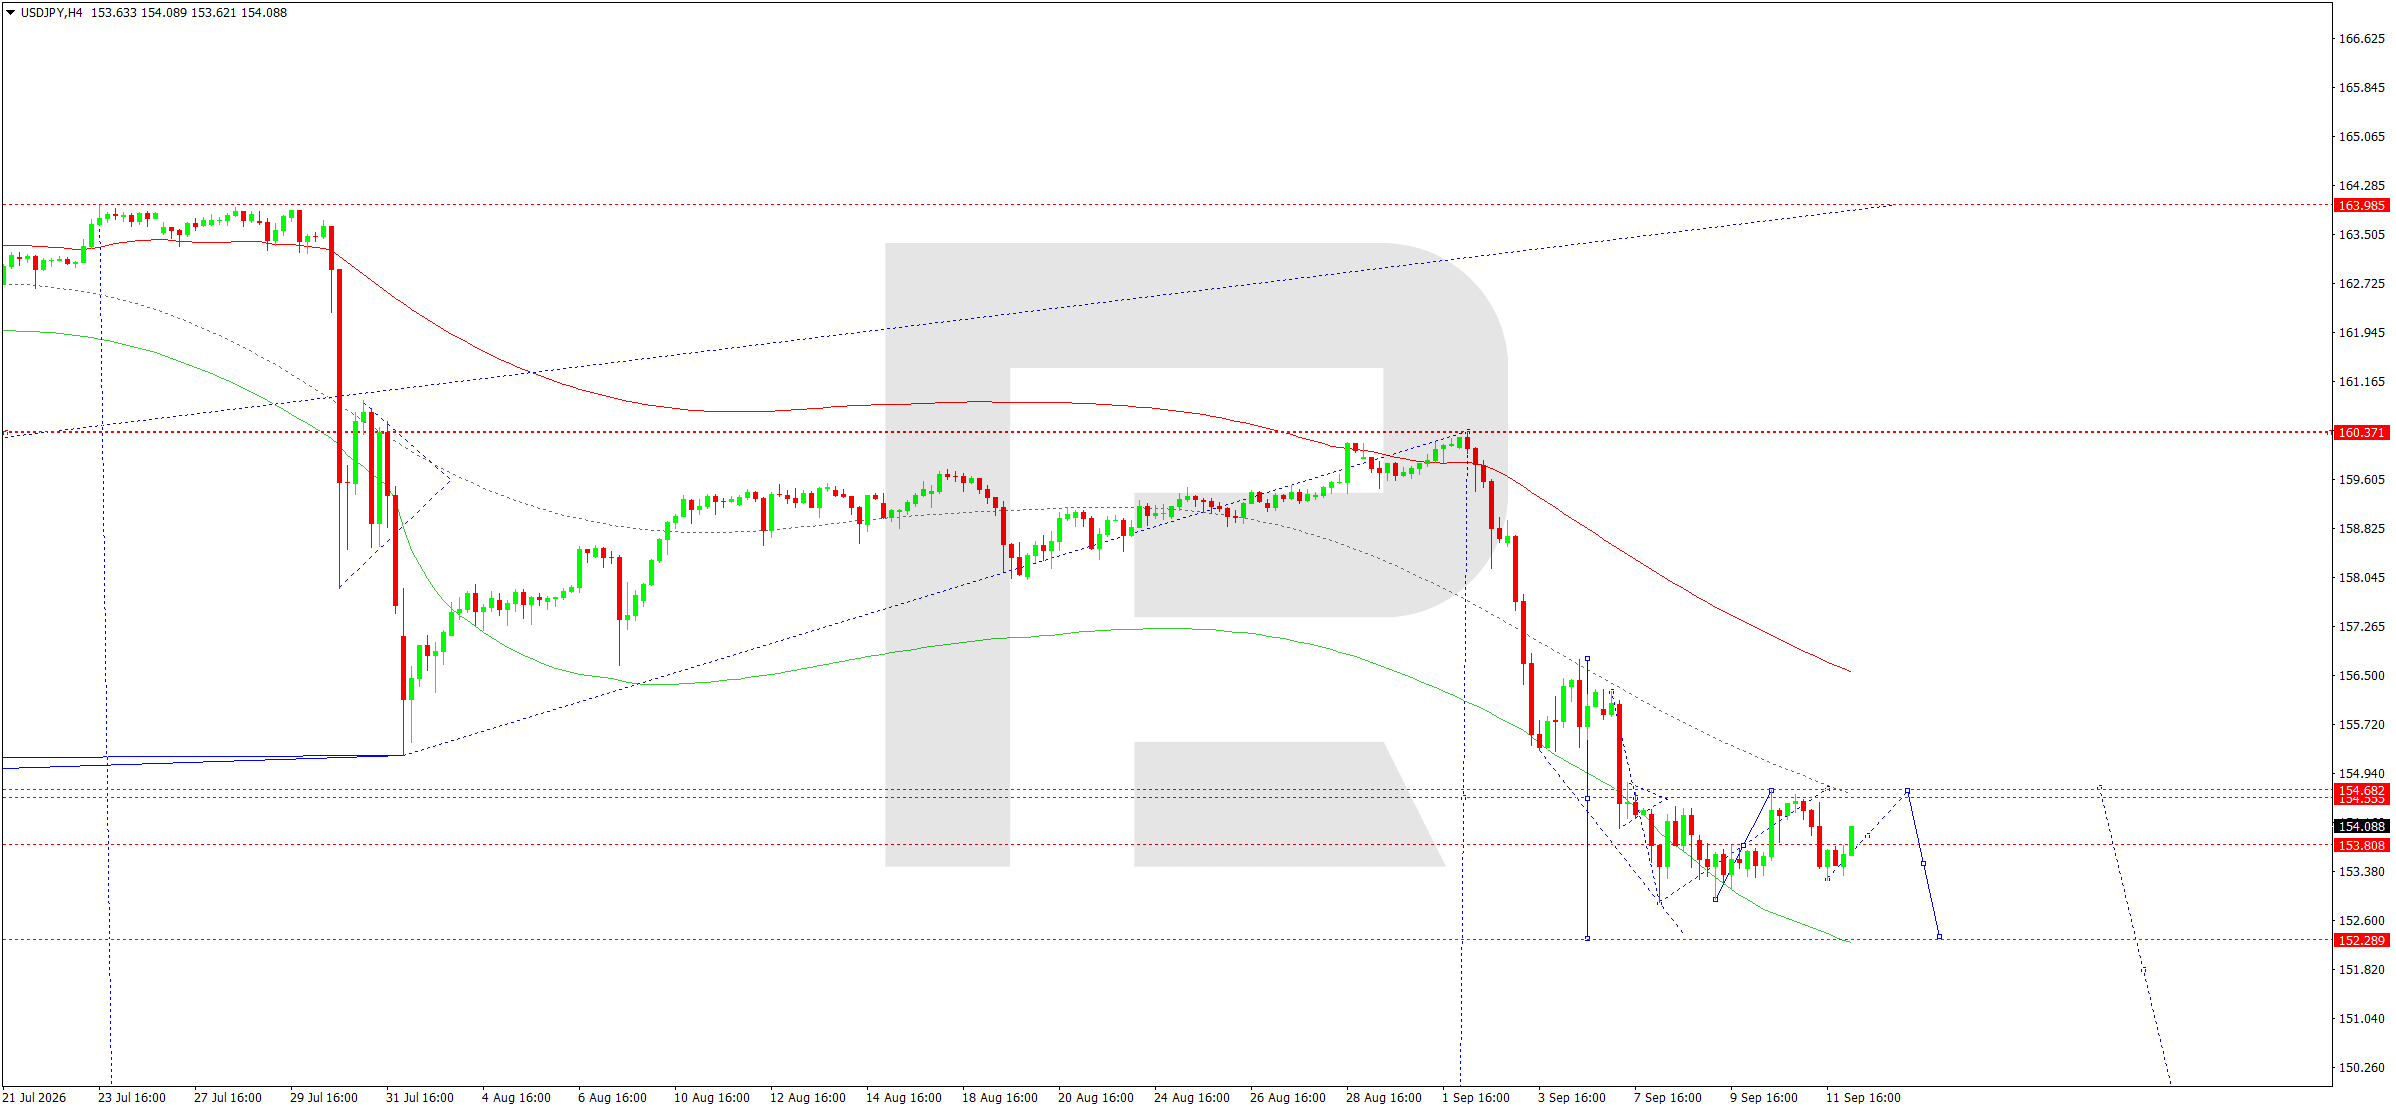
On the H4 chart, the pair found support around 153.25 and formed a corrective recovery towards 154.05–154.72. The main scenario for 14 September suggests a compact consolidation below 154.55–154.72, followed by a renewed decline. The matrix pivot is around 154.55, so a return to this area is primarily viewed as a correction within a broader bearish structure. While the price remains below 154.72, sellers retain the advantage.
The nearest downside target is at 152.30, corresponding to the lower part of the current Price Envelope and a local support area. A breakout below this support level would strengthen the momentum and open the way towards 150.00 and then 148.50. In the wave structure, the current rise looks like a corrective move after a strong downward impulse rather than the start of a new uptrend. A return above 154.72 and consolidation above 155.00 would temporarily invalidate the immediate downside scenario and enable a deeper correction. Additional confirmation comes from the price remaining below declining moving averages and beneath the upper boundary of the local channel. If the market retests the 154.55–154.72 area during the day and fails to consolidate above it, the probability of a new bearish impulse will increase. The main H4 trend remains downward.
USDJPY forecast scenario
Trading scenario: SELL
- Price at the time of writing: 154.05
- Entry price: 154.00
- Stop loss: 154.85
- Take profit: 152.30
- Risk-to-reward ratio: 1:2.0
The trade idea is valid until 8:00 AM on 15 September 2026 (server time, UTC+3).
GBPUSD forecast
As of 14 September 2026, the pound is caught between relatively resilient UK data and stronger demand for the dollar ahead of the Federal Reserve meeting. The Bank of England will meet on Thursday. The baseline consensus is for the policy rate to remain at 3.75%, although higher oil prices and inflation risks are increasing the probability of a more hawkish vote within the Monetary Policy Committee. BoE Governor Andrew Bailey stressed last week that a rate increase was not a foregone conclusion and that decisions would depend on the data. At the same time, UK GDP rose by 0.4% month-on-month in July, with annual growth reaching 1.6%, stronger than expected and reducing concerns about a sharp economic slowdown. Inflation remains above target, while expensive oil increases the risk of another acceleration in prices over the coming months.
For the dollar, the fundamental picture is clearer. The Fed is approaching its meeting after CPI accelerated to 3.4% year-on-year and expectations of a rate hike strengthened. Treasury yields remain high, while Brent above 107 USD per barrel is reinforcing the inflation impulse and supporting safe-haven demand for the dollar. The broader global risk-off factor also remains in place: tensions around oil supplies through the Middle East are raising import costs for the UK while supporting the dollar as a safe-haven currency. The market will also assess new signals from UK inflation and labour-market data ahead of Thursday’s BoE decision. Therefore, even with resilient UK data, the short-term fundamental balance for GBPUSD remains moderately negative for the pair.
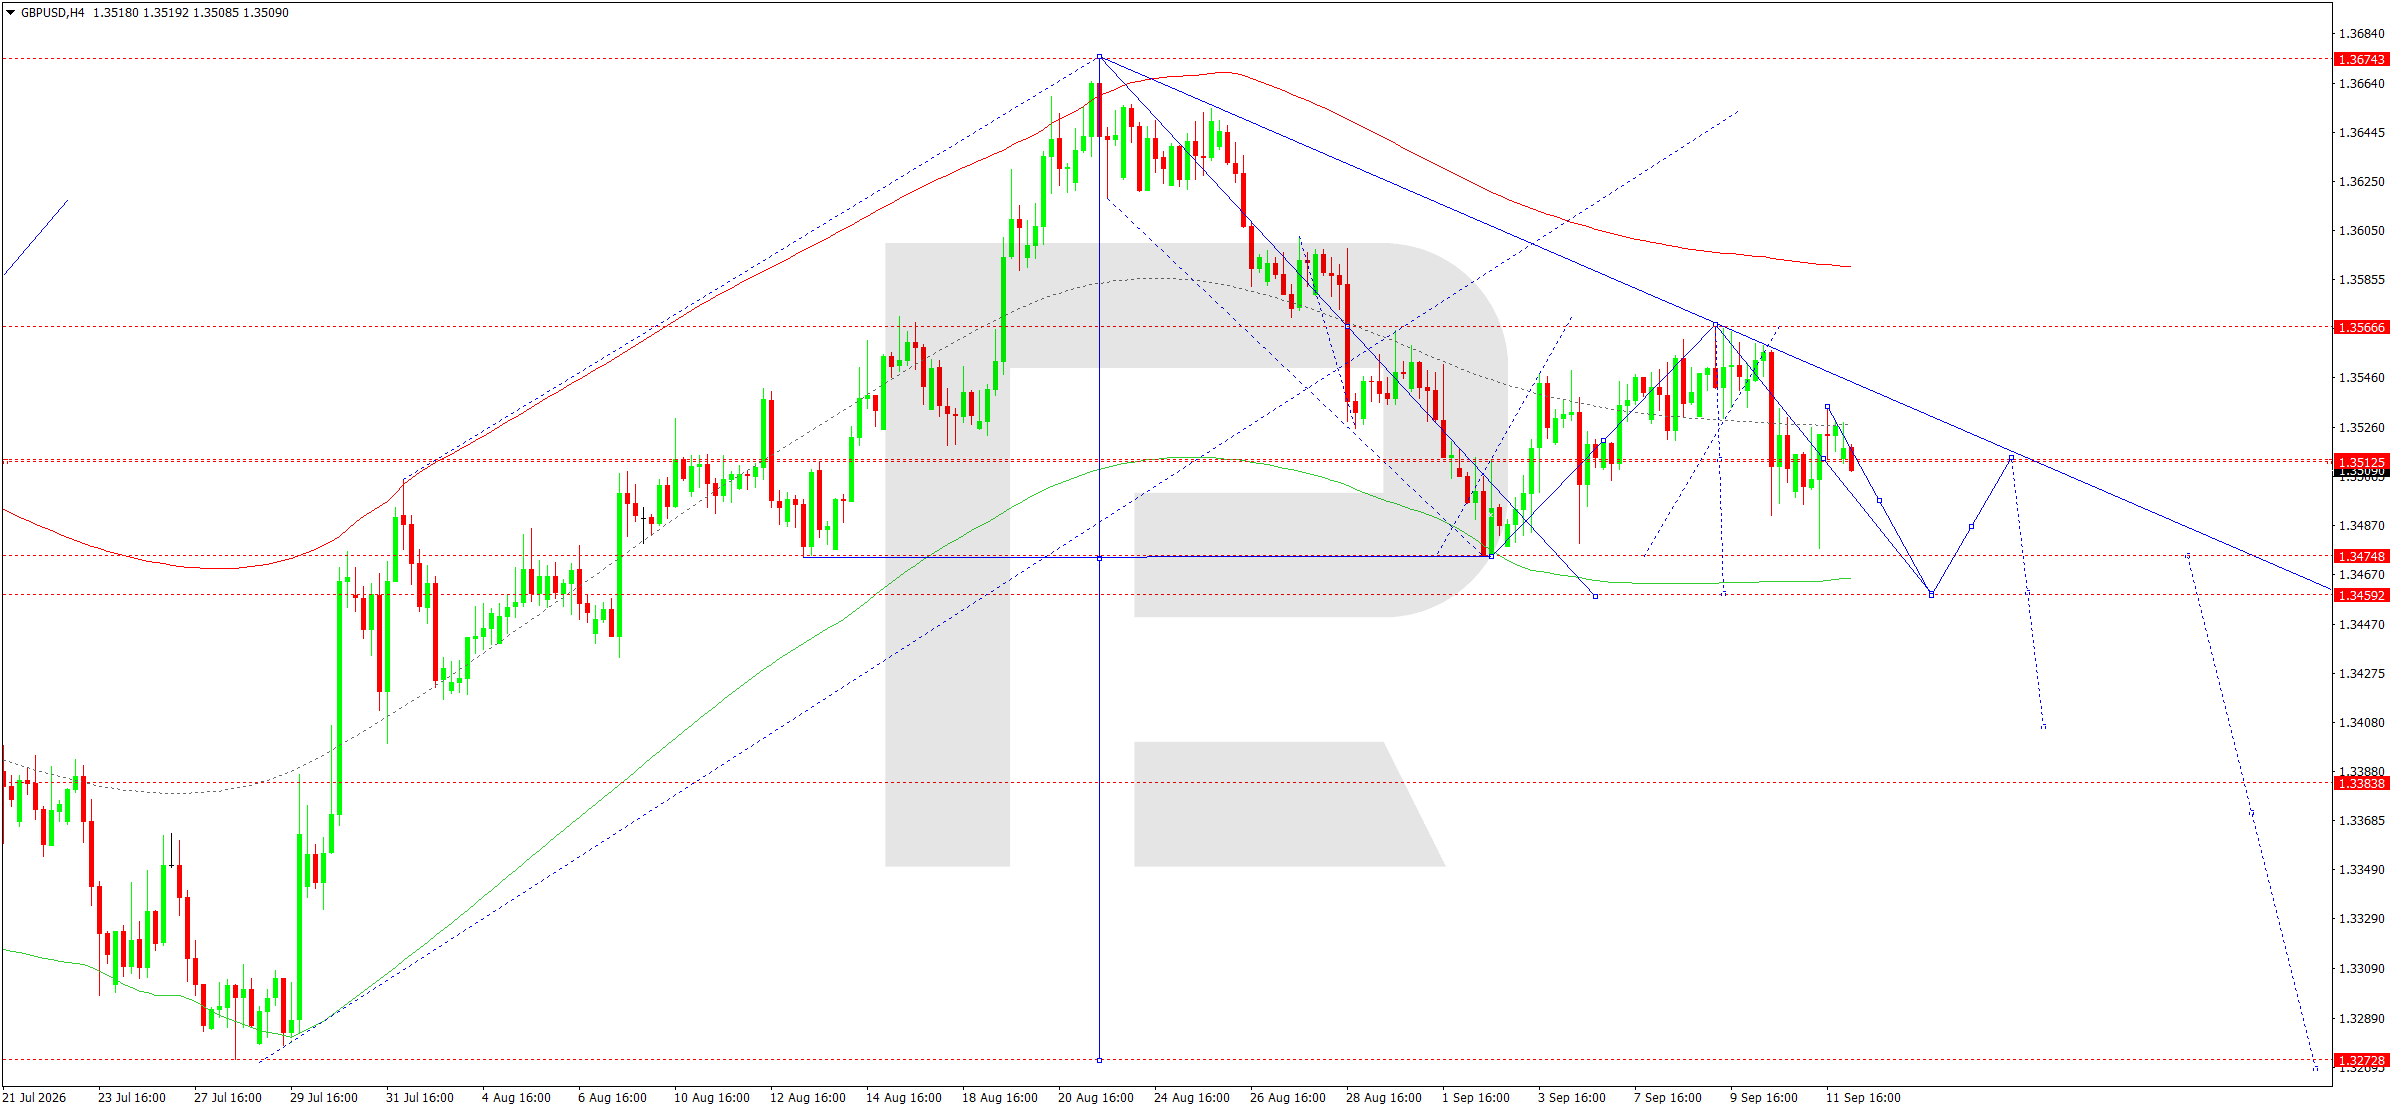
On the H4 chart, the market completed a corrective recovery around 1.3534 and moved into a new downward wave. A compact range is now forming around 1.3515, while the structure of local highs remains descending. The matrix pivot is at 1.3566, and while the price trades below this level, the main scenario points to continued downside.
The nearest target is in the 1.3475–1.3455 area, where the lower boundary of the current Price Envelope and a significant support zone are located. A breakout below 1.3455 would confirm the next impulse towards 1.3383. The Elliott wave structure suggests the current consolidation could be an intermediate pause before the third downward wave expands. A return above 1.3535 could lead to a retest of the 1.3566 level, but only consolidation above the matrix pivot would weaken the bearish scenario. Until then, selling on corrective rallies appears preferable. Another technical argument is the descending trendline from the August high: recent corrections have ended below previous peaks. If the price remains below 1.3515 during the session, a breakout below 1.3475 and an acceleration towards 1.3455 will become more likely. The main H4 trend remains bearish.
GBPUSD forecast scenario
Trading scenario: SELL
- Price at the time of writing: 1.3503
- Entry price: 1.3498
- Stop loss: 1.3568
- Take profit: 1.3383
- Risk-to-reward ratio: 1:1.6
The trade idea is valid until 8:00 AM on 15 September 2026 (server time, UTC+3).
AUDUSD forecast
As of 14 September 2026, the Australian dollar remains sensitive to a combination of tight global financial conditions, high oil prices and expectations of further action by the Reserve Bank of Australia. The RBA is keeping its policy rate at 4.35% after a series of earlier increases, but a recent acceleration in underlying inflation has again strengthened expectations of another hike. RBA officials have stressed that further tightening is possible if inflation risks materialise. At the same time, the Westpac Consumer Sentiment Index fell by 5.2% to 84.4 in September, reflecting pressure on households from high interest rates, fuel costs and a weaker housing market.
The external backdrop for the AUD also remains challenging. Oil prices above 107 USD, tensions in the Middle East and declines in Asian equity indices are weakening risk appetite. In China, consumer and producer inflation accelerated in August, mainly because of energy, providing mixed signals for Australian exports. The Federal Reserve is approaching its meeting with a high probability of a rate hike after US inflation accelerated. High Treasury yields and a stronger dollar are adding further pressure to AUDUSD. Higher global bond yields are another constraint for the Australian currency: investors are reducing positions in high-beta assets, which traditionally weakens demand for the AUD. At the same time, high commodity prices partly offset the pressure through Australia’s export revenues, so price action may remain uneven. Therefore, even with a more hawkish RBA, the fundamental backdrop remains moderately bearish for the pair.
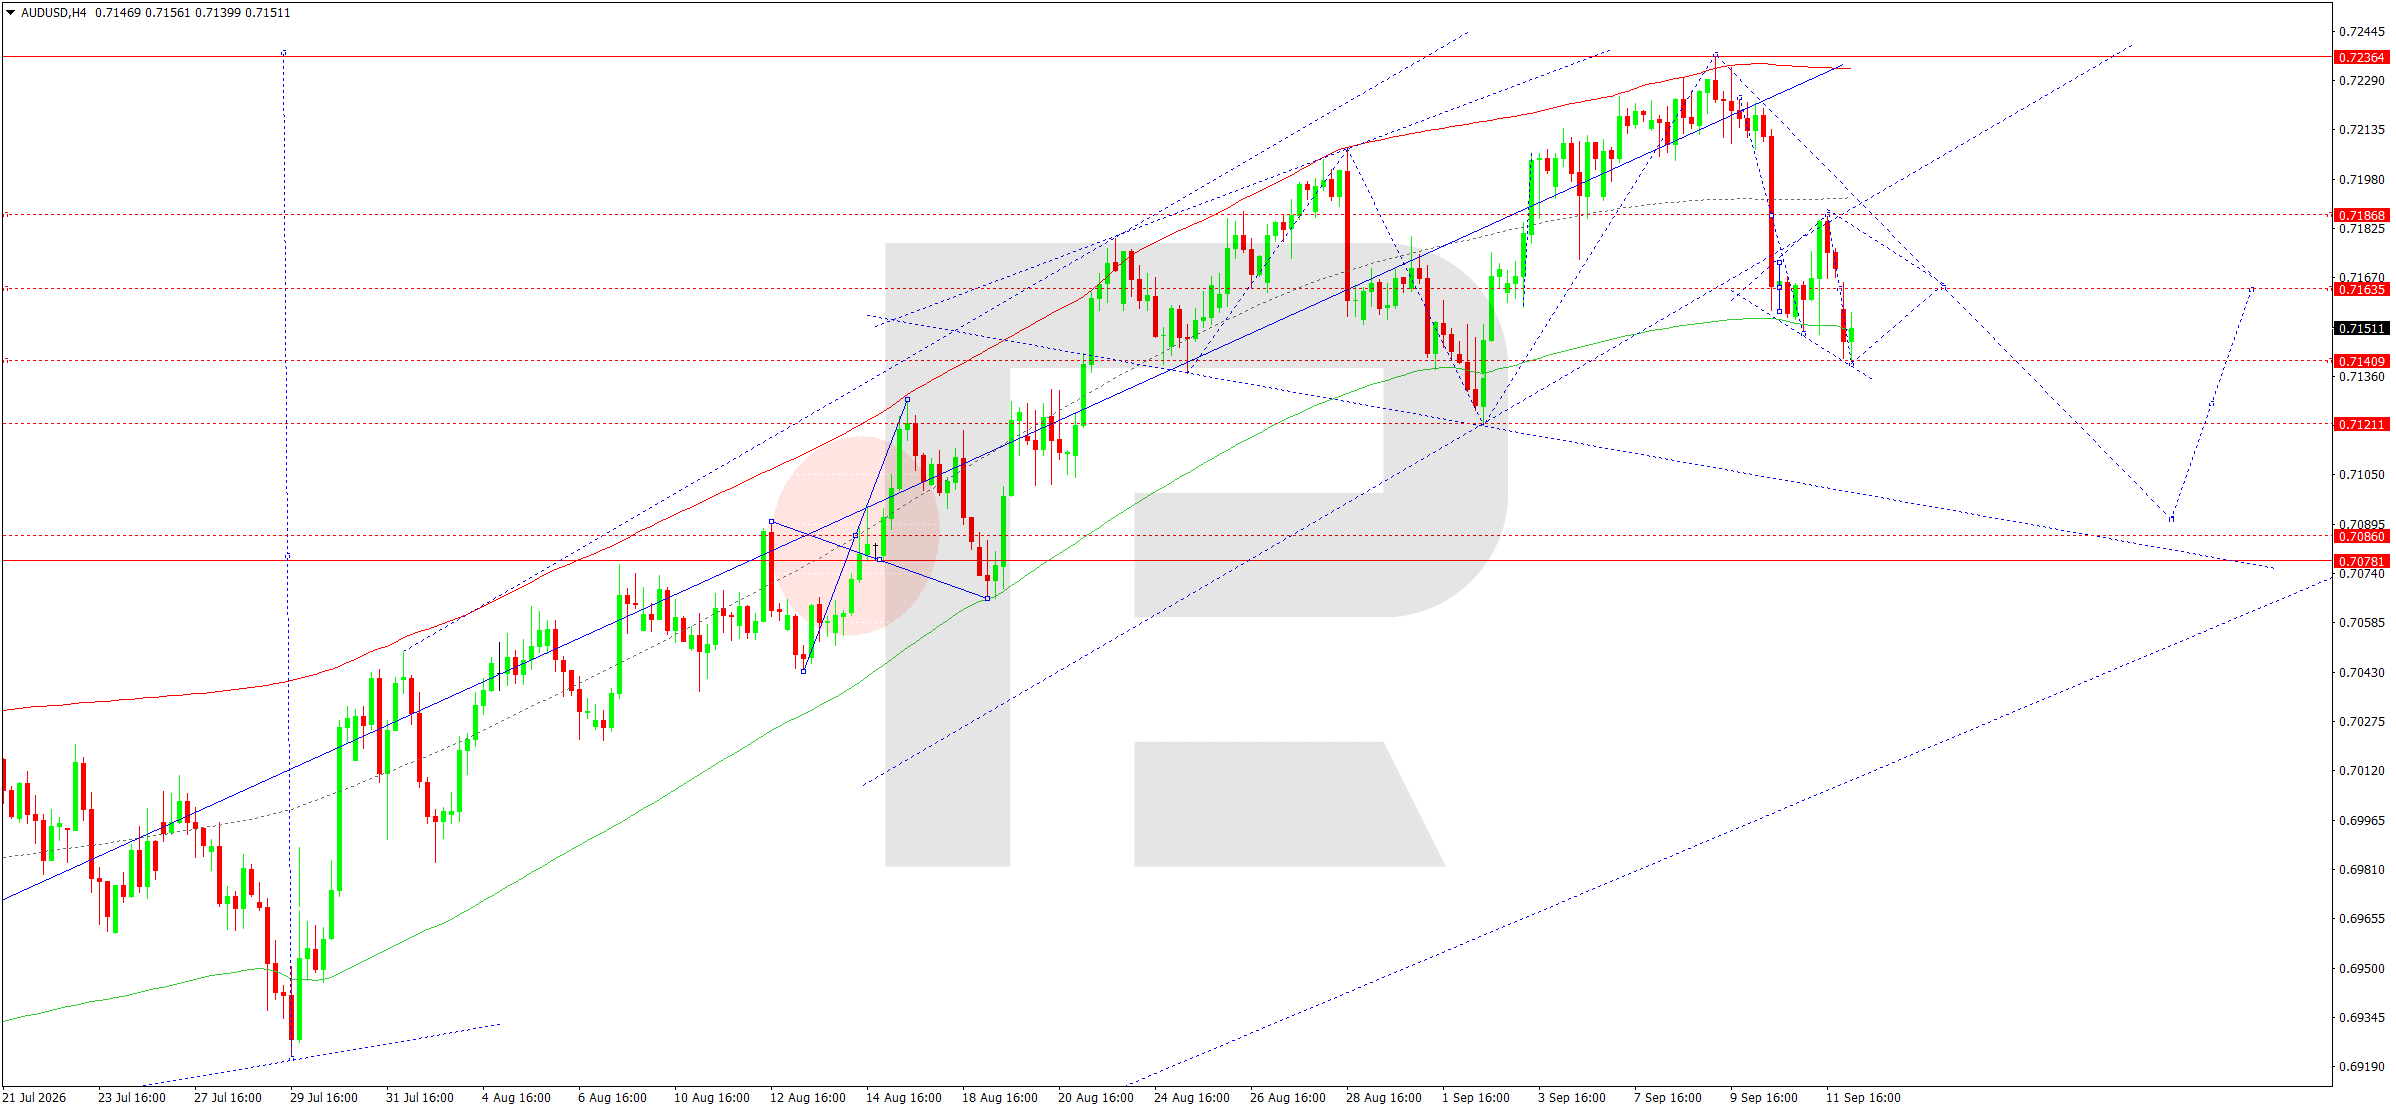
On the H4 chart, after peaking around 0.7236, the market formed a sharp downward impulse towards 0.7140 and is now attempting to stabilise above this support level. The nearest corrective target is in the 0.7163 area, where a significant resistance level and the central part of the local structure are located. The main scenario suggests a limited return towards this area, followed by a renewed decline.
The matrix pivot is around 0.7161. While the price remains below 0.7163–0.7180, sellers retain the advantage. A breakout below 0.7140 would open the way towards 0.7120 and then 0.7090. If the wave extends further, the next significant area would be 0.7080–0.7078. The Elliott wave structure indicates continued downward momentum after the correction ends. A return above 0.7180 would temporarily postpone the main scenario and allow the price to retest the 0.7210 level, but until such consolidation occurs, the downside remains the priority. The technical outlook is further supported by the price breaking out of the previous ascending channel and forming a series of lower local highs. If quotes remain below 0.7163 during the first half of the day, the likelihood of a retest of the 0.7140 mark and a breakout below the support level will increase. The main short-term H4 trend remains bearish.
AUDUSD forecast scenario
Trading scenario: SELL
- Price at the time of writing: 0.7149
- Entry price: 0.7144
- Stop loss: 0.7180
- Take profit: 0.7090
- Risk-to-reward ratio: 1:1.5
The trade idea is valid until 8:00 AM on 15 September 2026 (server time, UTC+3).
USDCAD forecast
As of 14 September 2026, the Canadian dollar is being influenced by several opposing factors. The Bank of Canada kept its policy rate at 2.25% on 2 September, but Governor Tiff Macklem said the regulator was prepared to raise borrowing costs repeatedly if inflation remained too high. Annual inflation in Canada has approached 3%, while the economy grew by 3.3% year-on-year in the second quarter, leaving the BoC room for tighter policy. A sharp rise in oil is providing additional support to the Canadian dollar: Brent climbed above 107 USD per barrel amid attacks on Saudi Arabia’s energy infrastructure and risks to shipping through the Strait of Hormuz and Bab el-Mandeb.
At the same time, the US dollar is supported by expectations of a Federal Reserve rate hike following the acceleration of August CPI to 3.4% and persistently high Treasury yields. Another negative factor for the Canadian currency is the deterioration in US-Canada trade relations. Uncertainty around North American trade remains elevated: mutual tariff risks are increasing the volatility of Canadian assets and may periodically weaken demand for the CAD. However, the energy factor is currently offsetting some of the trade pressure because more expensive oil improves Canada’s terms of trade. Overall, the fundamental balance remains mixed: a strong dollar limits downside in USDCAD, while expensive oil and the BoC’s more hawkish tone create conditions for CAD strength if external demand for the dollar weakens.
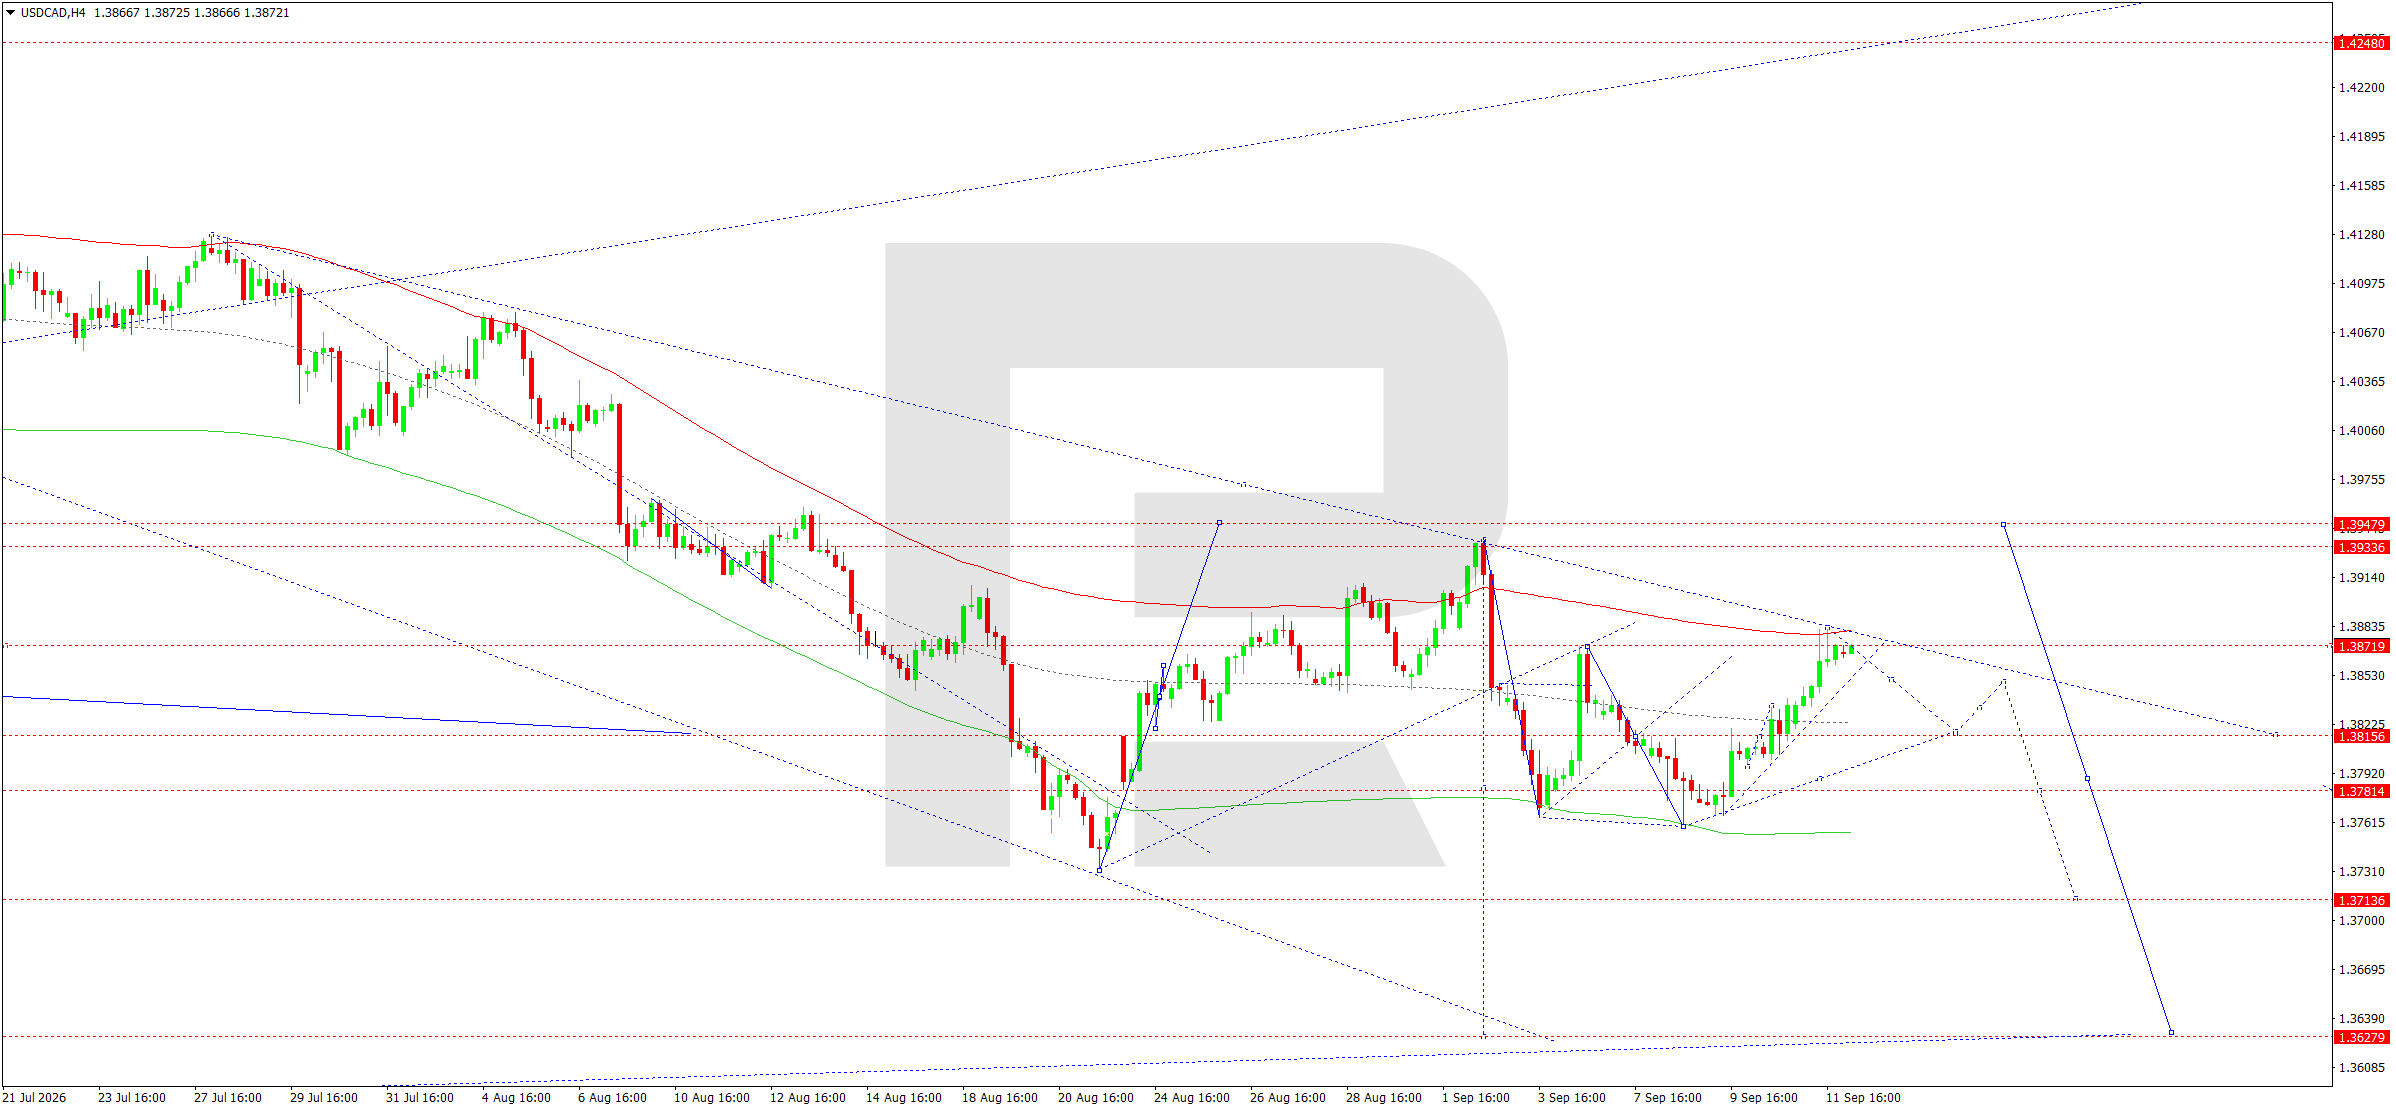
On the H4 chart, the pair completed a corrective rise towards 1.3880 and approached the upper boundary of the local Price Envelope. The market is forming a compact range in this area, while the structure still shows signs that the correction is ending within a broader bearish pattern. The matrix pivot is around 1.3814, so a return below this level would confirm renewed selling pressure.
The main scenario suggests limited holding below 1.3880, followed by a decline towards 1.3815 and 1.3781. A breakout below 1.3781 would open the way towards 1.3720, while an extension of the wave could bring the price to 1.3714 and below. An alternative scenario would require consolidation above 1.3880; in this case, the market could develop a final upward move towards 1.3940–1.3950. However, while the price remains below this area, such a rise is considered corrective. The Elliott wave structure and the price position near the upper boundary of the Envelope support expectations of a decline. Additional technical confirmation comes from the price approaching the descending trendline through the August highs. A failed attempt to consolidate above 1.3880 would keep this line as resistance and increase the probability of an acceleration towards 1.3815 during the current session. The short-term priority is SELL.
USDCAD forecast scenario
Trading scenario: SELL
- Price at the time of writing: 1.3875
- Entry price: 1.3870
- Stop loss: 1.3950
- Take profit: 1.3720
- Risk-to-reward ratio: 1:1.9
The trade idea is valid until 8:00 AM on 15 September 2026 (server time, UTC+3).
XAUUSD forecast
As of 14 September 2026, gold is under pressure from a combination of high bond yields and stronger expectations of tighter monetary policy in the US. Following the release of August CPI, the probability of a Federal Reserve rate hike at the meeting rose to around 87%. Consumer inflation accelerated to 3.4% year-on-year, while the yield on 10-year US Treasuries remains near 5%. This is negative for gold because higher real and nominal yields increase the opportunity cost of holding a non-yielding asset.
At the same time, the geopolitical backdrop remains tense. Brent climbed above 107 USD per barrel after new attacks on Saudi Arabia’s infrastructure and risks to shipping through the Strait of Hormuz and Bab el-Mandeb. This supports demand for safe-haven assets and limits the depth of gold’s decline. However, at the start of the week, the market is reacting more strongly to the prospect of a Fed rate hike and a stronger dollar. Spot gold had already fallen towards 4,327 in the morning, in line with the current technical picture. The strong inflation impulse has not yet triggered immediate demand for gold as an inflation hedge: investors are primarily reassessing the Fed’s rate path. A deterioration in the geopolitical situation could quickly revive demand for gold, so the decline may be accompanied by sharp corrective rebounds. Overall, the fundamental backdrop remains conflicting, but sellers hold the short-term advantage while bond yields stay elevated.
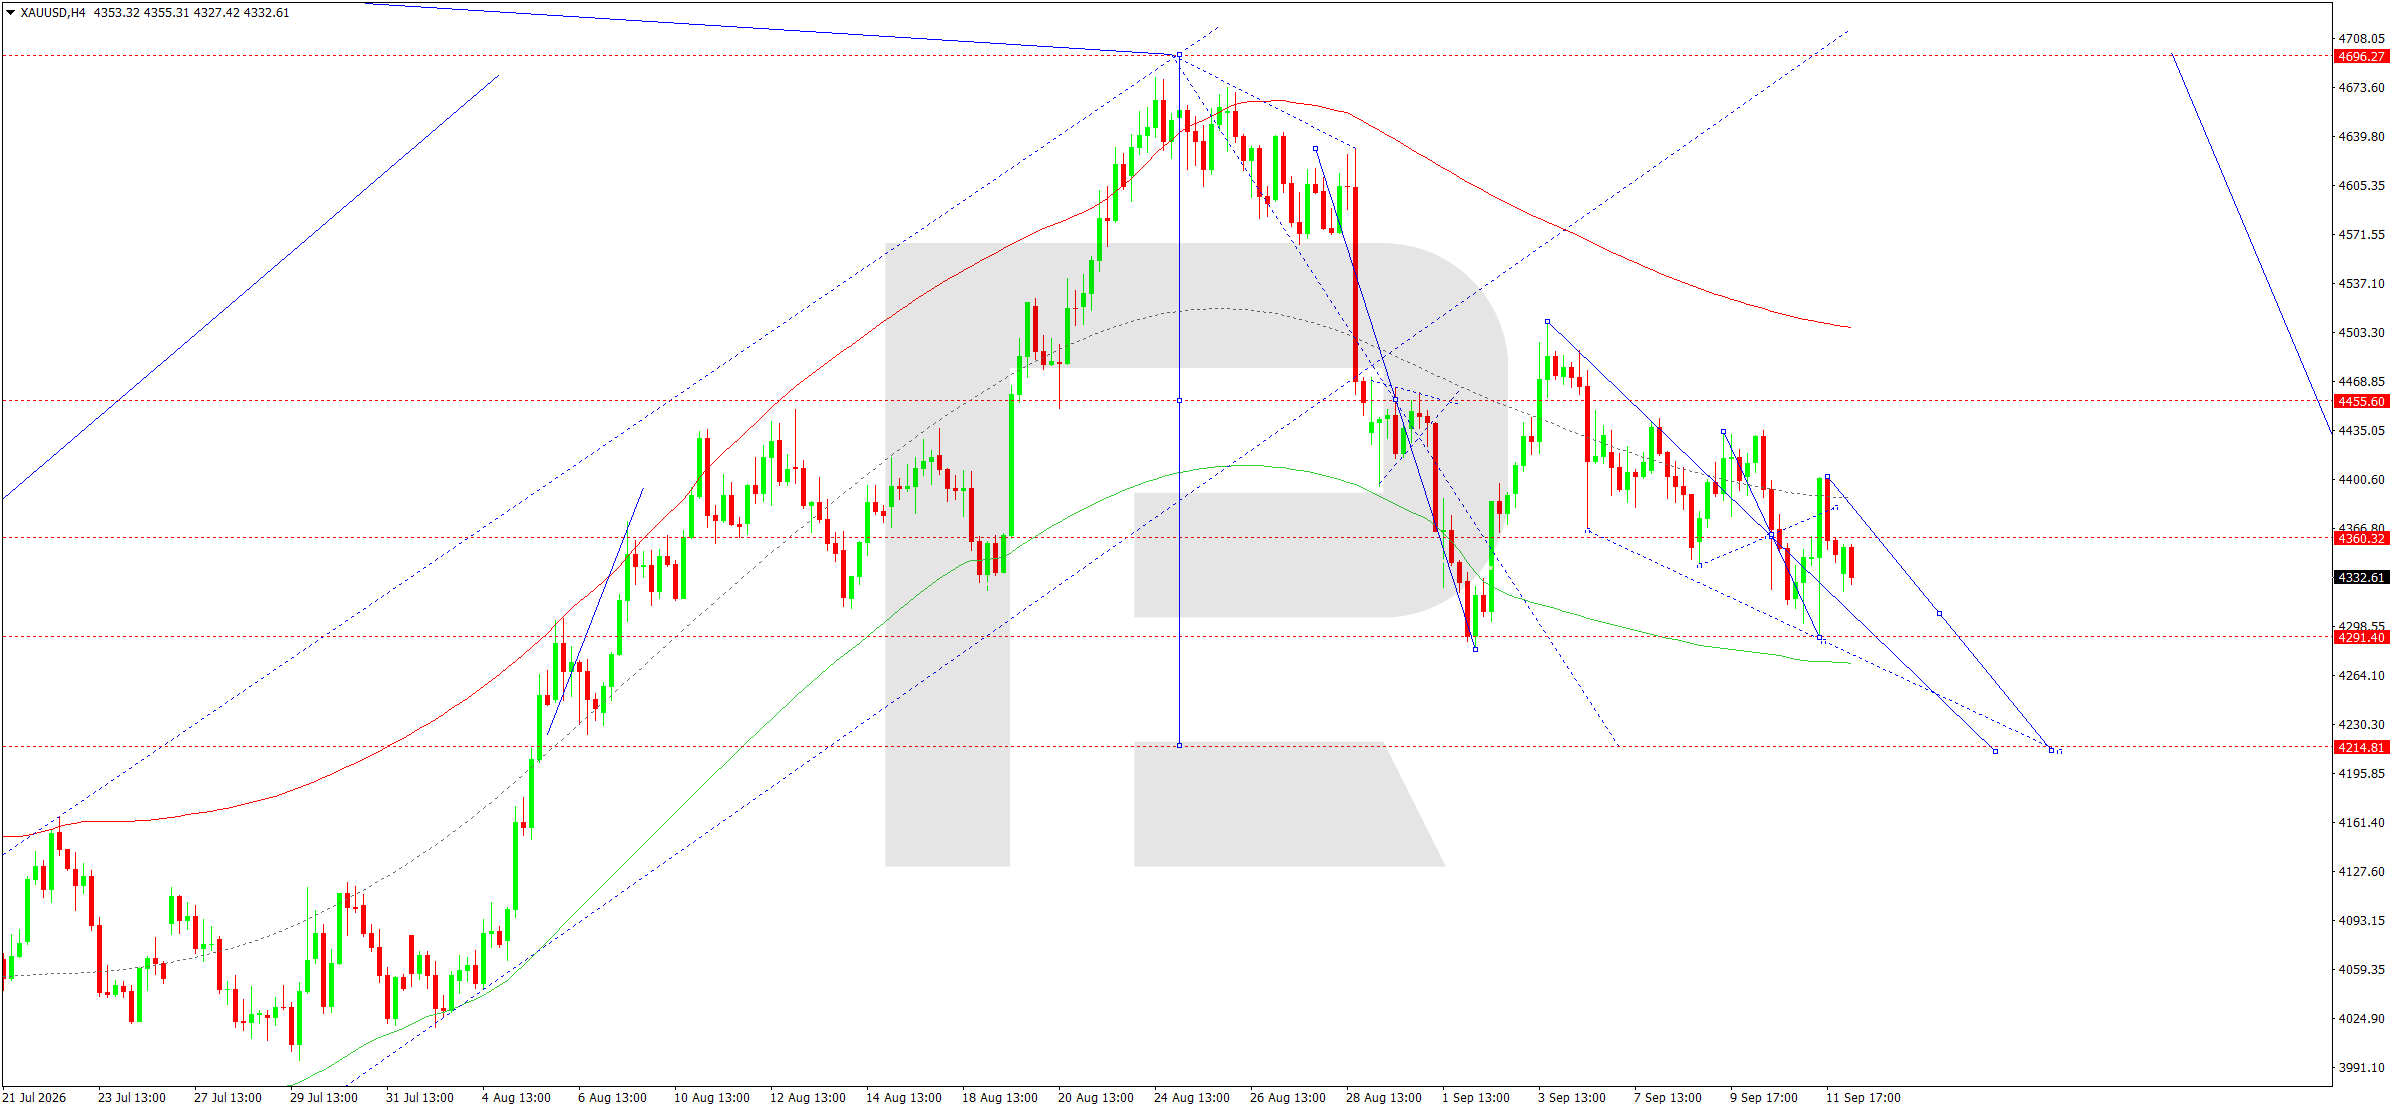
On the H4 chart, XAUUSD continues to form a bearish structure after the strong upward momentum ended in August. The price has formed a sequence of lower highs and returned to the 4,321–4,330 area. The consolidation range lies below the central zone of the Price Envelope, keeping pressure on the support level.
The matrix pivot is around 4,455, while the central line of the Price Envelope is near 4,363. While the market remains below these levels, the main scenario is for the decline to continue. The nearest target is 4,300, followed by key support around 4,220. A breakout below 4,220 would confirm a deeper downward wave. A local correction towards 4,363 is possible, but without consolidation above 4,455 it would be treated as a technical rebound within the bearish structure. The Elliott wave model and descending channel also confirm the sellers’ advantage. Additional confirmation comes from the price remaining below the declining moving average and the upper boundary of the short-term channel. If the market fails to return above 4,363, prices are likely to test the 4,300 level during the current session. A firm breakout below 4,300 would strengthen the momentum and increase the probability of an acceleration towards 4,260–4,220. Only consolidation above 4,455 would materially shift the balance in favour of buyers. The main H4 trend remains bearish.
XAUUSD forecast scenario
Trading scenario: SELL
- Price at the time of writing: 4,327
- Entry price: 4,322
- Stop loss: 4,365
- Take profit: 4,220
- Risk-to-reward ratio: 1:2.4
The trade idea is valid until 8:00 AM on 15 September 2026 (server time, UTC+3).
US 500 forecast
As of 14 September 2026, the US stock market is starting the week under pressure from rising yields, expensive oil and expectations of tighter Federal Reserve policy. The US Consumer Price Index rose by 0.4% month-on-month and 3.4% year-on-year in August, sharply increasing the probability of a Fed rate hike at this week’s meeting. The market estimates that probability at around 86–87%, while major banks have revised their forecasts towards a 25-basis-point increase. The yield on 10-year US Treasuries is holding near 4.97%, raising the discount rate for equities and having a particularly strong impact on growth companies.
Oil is adding further pressure. Brent climbed above 107 USD per barrel after new attacks on Saudi Arabia’s energy infrastructure and rising risks to supplies through key maritime routes. More expensive energy is raising inflation expectations and worsening companies’ margin outlooks. Asian equity indices fell, and US index futures were also under pressure. At the same time, Friday’s rise in the S&P 500 showed that some investors are still willing to buy dips, but the risk of another decline remains elevated ahead of the Fed decision. The technology sector is another source of risk: renewed concerns around AI regulation and security have increased pressure on Asian equities and could raise volatility in US megacaps. Ahead of the Fed meeting, investors are likely to avoid aggressively increasing risk exposure. The fundamental backdrop for the US 500 at the start of the week remains moderately negative.
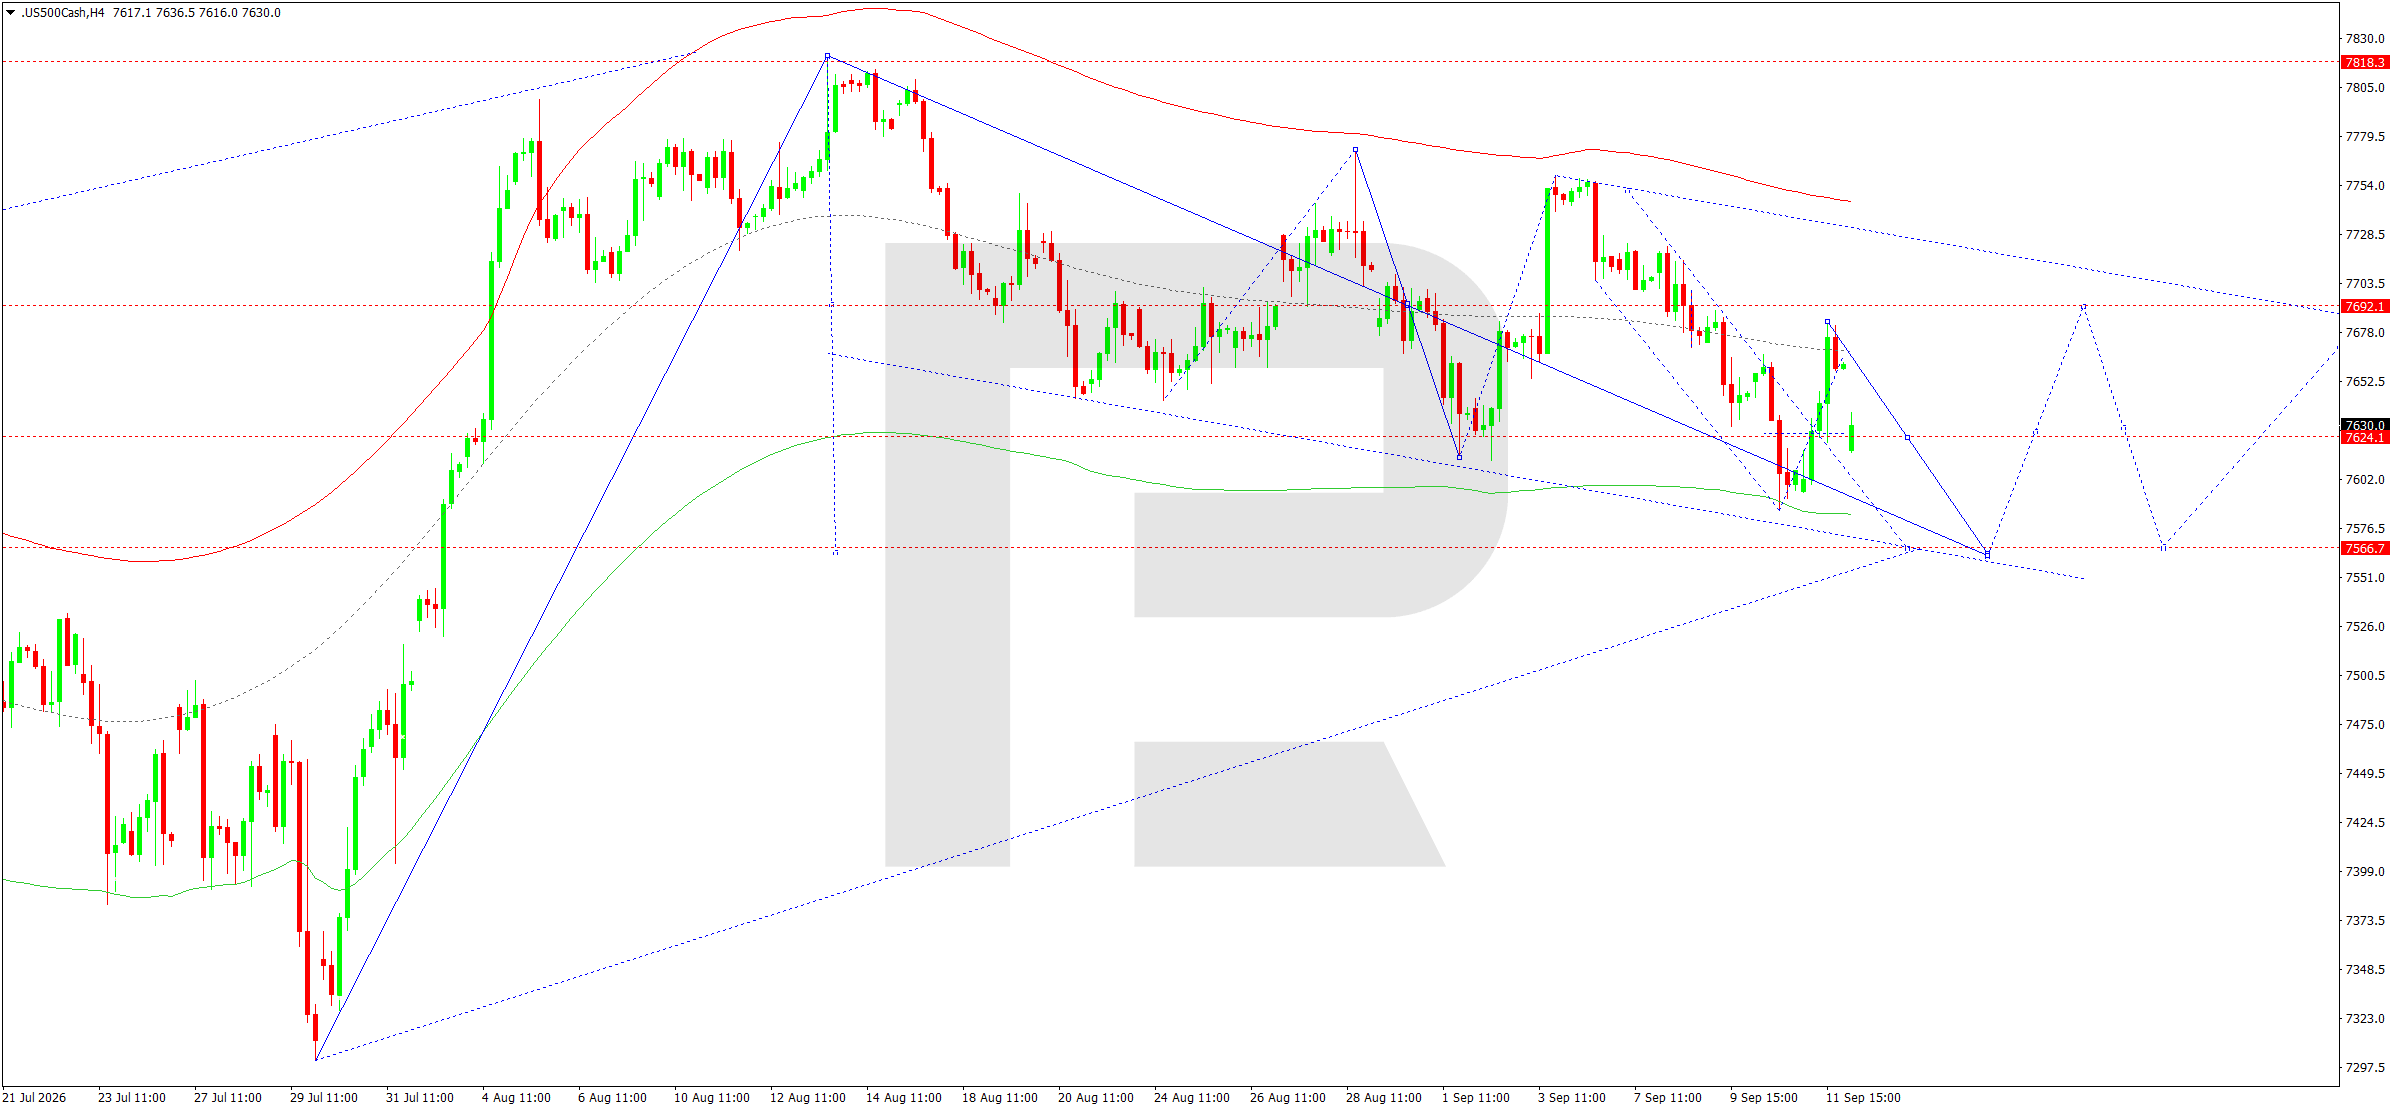
On the H4 chart, after a corrective rise towards 7,683, the index moved into a new downward wave and returned to the 7,615–7,624 area. The price remains within a bearish structure and below the central zone of the Price Envelope. The matrix pivot is around 7,690, so all rises below this level are still considered corrective.
The scenario suggests a range forming below 7,624, followed by a decline towards 7,566. This level coincides with important local support and the lower boundary of the nearest technical structure. A breakout below 7,566 would create room for the downward wave to extend towards 7,520 and beyond. A return above 7,666 could trigger another test of 7,690, but only consolidation above the matrix pivot would weaken the current bearish scenario. The Elliott wave structure, descending channel and sequence of lower highs all confirm the sellers’ advantage. Another confirmation comes from the price failing to consolidate above 7,683 after the latest rebound. While this area remains resistance, another test of 7,566 looks more likely than a return to the early-September highs. The main H4 trend remains bearish, with 7,566 acting as today’s first key technical target.
US 500 forecast scenario
Trading scenario: SELL
- Price at the time of writing: 7,621
- Entry price: 7,616
- Stop loss: 7,641
- Take profit: 7,566
- Risk-to-reward ratio: 1:2.0
The trade idea is valid until 8:00 AM on 15 September 2026 (server time, UTC+3).
BTCUSD forecast
As of 14 September 2026, Bitcoin is starting the week amid deteriorating global risk appetite and rising expectations of tighter US policy. After a strong rally in August, the cryptocurrency moved into a correction, while accelerating US inflation increased pressure on high-risk assets. The Federal Reserve will meet this week, and after CPI rose to 3.4% year-on-year, the market is pricing in a roughly 86–87% probability of a rate hike. At the same time, the yield on 10-year US Treasuries is near 5%, increasing the appeal of risk-free dollar assets and reducing demand for cryptocurrencies.
Another negative factor is a fresh rise in oil prices. Brent climbed above 107 USD per barrel amid attacks on Saudi Arabia’s infrastructure and risks to shipping through the Strait of Hormuz and Bab el-Mandeb. This is raising inflation expectations, weakening global risk appetite and supporting the dollar. Bitcoin already showed weakness last week amid a similar combination of expensive oil and expectations of a Fed rate hike. Long-term interest in digital assets remains intact, but the macroeconomic factor is dominant over the short term. Bitcoin also remains highly correlated with the technology sector: weaker Nasdaq futures and investor caution ahead of the Fed meeting increase the likelihood of reduced speculative positioning. Flows into cryptocurrency funds after the August rally remain another source of volatility. While the dollar and yields rise simultaneously, conditions for a BTC recovery remain limited. Ahead of the Fed decision, the fundamental backdrop for BTCUSD is assessed as moderately negative.
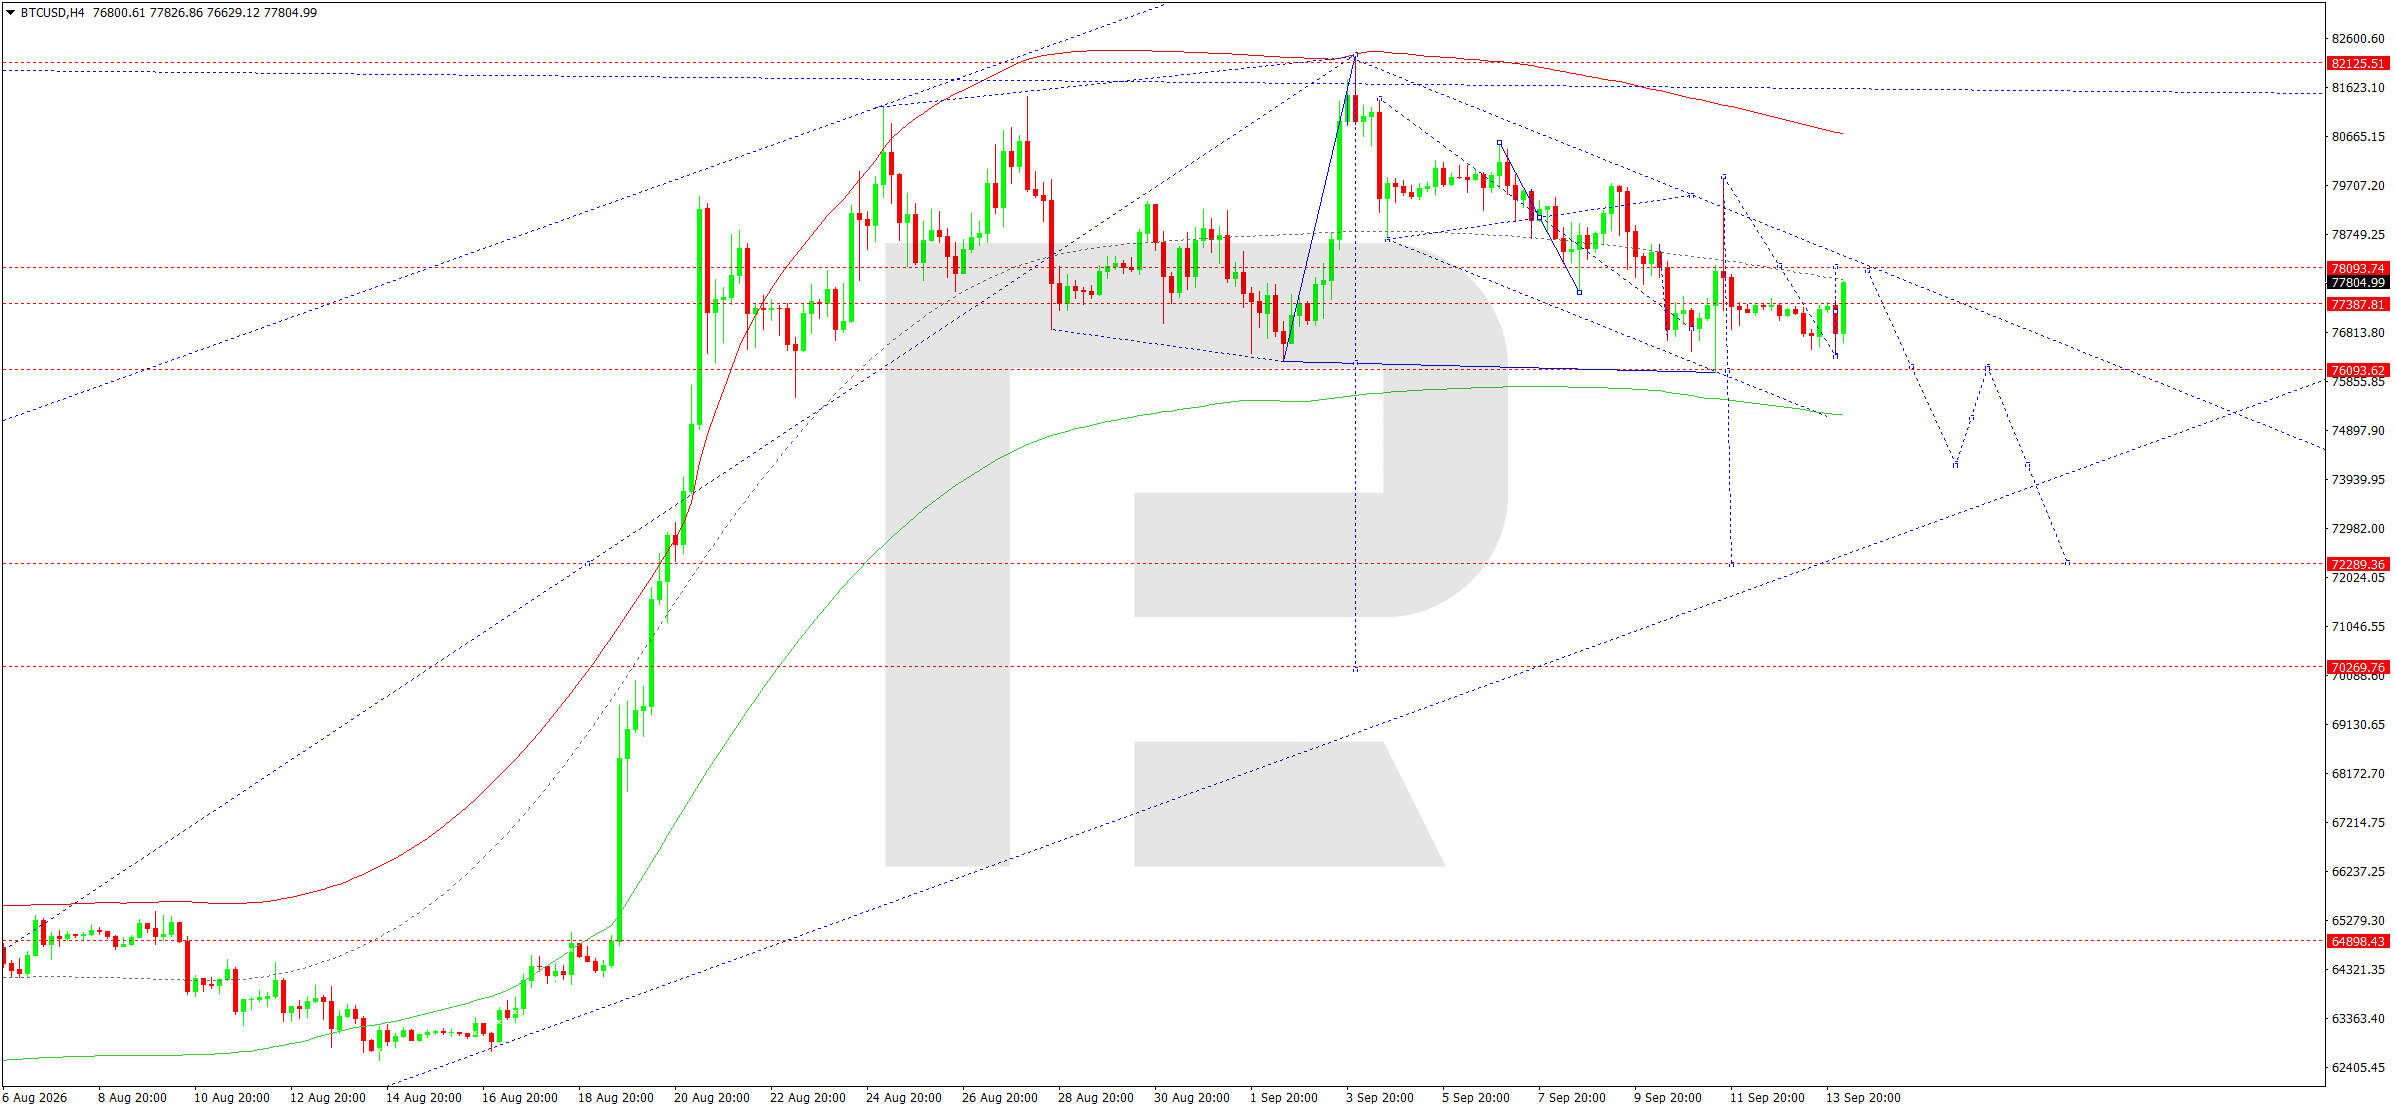
On the H4 chart, the market formed a downward wave from the 82,000 area and reached the 76,400–76,100 zone. The price then moved into consolidation around 77,800–78,000, but the structure of local highs remains descending. The matrix pivot is around 79,090, and while Bitcoin trades below this level, the main scenario points to continued downside.
A significant support level lies at 76,094–75,565. A breakout below this area would confirm the next impulse towards 74,000 and then 72,260, where the lower boundary of the structure is located. A corrective return towards 78,000 is possible, but without consolidation above 79,090 it would be viewed as a resistance retest from below. The Elliott wave structure suggests the downward wave could continue once the current range is complete. A descending line from the September high is also adding to pressure. If the price retests the 78,000 level and rebounds, this would provide additional confirmation for sellers. Firm consolidation below 75,565 would accelerate the third downward wave and make 72,260 the main medium-term target. Only a return above 79,090 and then 80,000 would shift the balance in favour of buyers. Until then, selling on corrective rallies remains the priority. The main H4 trend remains bearish.
BTCUSD forecast scenario
Trading scenario: SELL
- Price at the time of writing: 77,530
- Entry price: 77,525
- Stop loss: 79,095
- Take profit: 72,260
- Risk-to-reward ratio: 1:3.4
The trade idea is valid until 8:00 AM on 15 September 2026 (server time, UTC+3).
Editors’ picks
 EURUSD forecast 2026–2027: technical analysis, price levels & predictions
EURUSD has recovered from the July lows and is trading near 1.1545 — back in bullish territory. The pair has reclaimed EMA65 on the daily, formed a bullish EMA crossover on H4, and the US-eurozone GDP gap has narrowed sharply (US 1.5% vs eurozone 1.0%). Goldman Sachs and Deutsche Bank both now target 1.2500 by year-end. A confirmed close above 1.1700 opens the path to 1.1805. We break down the key levels, three trading scenarios, and what the unprecedented 9-3 FOMC dissent vote means for EURUSD.
 Gold (XAUUSD) forecast 2026: technical analysis, price levels & predictions
Gold has reversed its downtrend and is trading near 4,360 USD, back above both EMA65 and EMA200. ETF flows turned positive in July with 3 billion USD of net inflows, and central banks bought 288.9 tonnes in Q2 — up 62% year-on-year. A breakout above 4,500 USD opens the path to 4,855 USD and the 5,597 USD all-time high. We break down the key levels, three trading scenarios with entry triggers, and what J.P. Morgan, Deutsche Bank and Goldman Sachs are forecasting for gold in 2026.
Forecasts presented in this section only reflect the author’s private opinion and should not be considered as guidance for trading. RoboForex bears no responsibility for trading results based on trading recommendations described in these analytical reviews.