
Netflix stock falls despite profit growth – NFLX stock forecast
Netflix continues to increase its profit, but revenue growth is slowing, while the advertising outlook fell short of expectations. After the decline, NFLX shares have become significantly cheaper based on valuation multiples and are now near the lower end of analysts’ forecast ranges, creating conditions for a potential local bottom.
Netflix, Inc. (NASDAQ: NFLX) ended Q3 2026 with revenue up 12%, net income up 44%, and an operating margin of 34.6%. However, these strong results failed to shift negative investor sentiment. The main concerns were the continued slowdown in revenue growth and a lower forecast for the advertising business.
For Q4, management expects revenue of around 13.44 billion USD, earnings per share of 0.67 USD, and an operating margin of around 26%, pointing to weaker performance compared with Q3.
Internal changes at Netflix are creating additional uncertainty. The company announced plans to cut 1,000 jobs, or around 6% of its workforce, and began restructuring its content division leadership. These measures could reduce costs and improve efficiency, but they also suggest Netflix is adapting its corporate structure to slower growth.
This article analyses Netflix shares after the Q3 2026 report, examining the company’s financial results, main revenue sources, and the reasons behind the share price decline. It also provides a fundamental analysis of NFLX, analyst forecasts, and key technical levels that form the basis for a Netflix stock forecast.
About Netflix, Inc.
Netflix, Inc. was founded on 29 August 1997 by Reed Hastings and Mark Randolph. The company initially delivered DVDs on a subscription basis. Clients could order a film through the website and receive it by post. In 2007, Netflix launched a streaming service, allowing users to watch movies and TV shows online.
The transition to live streaming was pivotal in the company’s history. Netflix began actively expanding its content library to include licensed films, series and original projects. By July 2024, Netflix had 277 million subscribers worldwide, making it the largest streaming platform.
Netflix, Inc.’s key financial flows
Netflix’s revenue mainly comes from streaming services, advertising, and other sources. The main components are outlined below:
- Subscription fees: Netflix’s primary revenue stream, derived from ad-supported and ad-free subscriptions.
- Advertising revenue: payments from companies for placing advertisements.
- Content licensing and distribution: revenue is generated from providing paid licences for Netflix’s original and purchased content to other platforms and TV channels. This segment also includes income from partnerships with telecommunication providers, cable companies, and other distributors that offer Netflix as part of their packages.
- Other revenue streams: sales of merchandise related to Netflix series and films (e.g. toys, apparel, and collectables). The company has also started investing in the gaming industry by offering mobile games based on its intellectual property, creating additional opportunities for revenue growth.
Most of Netflix’s revenue derives from streaming subscriptions, while advertising, licensing, and other business segments offer additional potential for income growth.
Netflix, Inc. Q2 2024 financial results
Netflix released its Q2 2024 financial results on 18 July. Below is a comparison of its results with the same period in 2023:
- Revenue: 9.56 billion USD (+17%)
- Net income: 2.15 billion USD (+44%)
- Earnings per share: 0.49 USD (+48%)
- Operating income: 2.60 billion USD (+44%)
- Operating margin: 27.2% (+490 basis points)
- Total subscribers: 277.65 million (+16%)
Although the company’s subscriber numbers continue to increase quarter over quarter, this growth is gradually slowing. The increase in memberships in Q4 2023 surpassed previous figures by 13.13 million, followed by 9.32 million in Q1 2024 and 8.05 million in Q2 2024. Netflix is facing challenges in identifying new catalysts for subscriber growth. The company is now attracting new subscribers by addressing password sharing and reducing the cost of ad-supported subscription plans. Market participants are sensitive to these statistics; a look at the stock behaviour when Netflix reported a loss of 200 thousand subscribers in Q1 2022 reflects this, dragging the share price down by over 30% and continuing its decline.
Netflix’s management plans to stop publishing subscriber statistics from 2025 onwards to mitigate these challenges and focus investors’ attention on revenue per user, total revenue, and operating margin.
Amid slowing membership growth, the company is exploring new growth drivers, with advertising viewed as a potential source. Netflix’s management has noted that advertising is becoming increasingly significant to the company’s operations. However, building this business from scratch will take time, meaning it is unlikely to become the primary driver of revenue growth in 2024 and 2025.
Netflix forecasts 14% year-on-year revenue growth in Q3 2024, although a lower increase in paying users is expected compared to the same period in 2023. At the same time, no changes are anticipated for the global average revenue per user.
Based on the 2024 results, revenue is projected to rise by 14−15%, compared with the earlier forecast of 13−15%, while the operating margin is expected to reach 26%, up from the earlier estimate of 25%. The company’s goal remains to increase operating profit.
Netflix, Inc. Q3 2024 financial results
Netflix released its Q3 2024 financial results on 17 October. Below is a comparison of its data with the corresponding period in 2023:
- Revenue: 9.82 billion USD (+15%)
- Net income: 2.36 billion USD (+41%)
- Earnings per share: 0.54 USD (+20%)
- Operating income: 2.94 billion USD (+25%)
- Operating margin: 29.6% (+720 basis points)
- Total subscribers: 282.7 million (+14%)
Co-CEO Theodore Sarandos noted that content production is recovering after last year’s strikes in Hollywood, with series rebounding more rapidly than films. The company’s advertising business showed significant growth, with the number of subscribers to ad-supported plans increasing by 35% from the previous quarter. More than half of new users in regions with ad services chose this package option. However, the company emphasised that effective ad monetisation will take time, and this segment will not become a primary revenue stream in the near term.
In Q4 2024, Netflix projected earnings per share of 4.20 USD, with revenue of 10.12 billion USD, representing annual revenue growth of 15%. The total number of subscribers was forecast to increase by 8.2 million to approximately 290.9 million.
The company anticipated that its advertising revenue would double in 2025, driven by a 150% increase in advertising commitments secured during 2024. Despite the upbeat forecast, Netflix noted that advertising was not expected to become a primary revenue driver in the near term. This guidance highlighted the company’s ongoing efforts to strengthen its position in the streaming market and diversify its revenue streams.
Netflix, Inc. Q4 2024 financial results
Netflix released strong Q4 2024 financial results on 21 January. Below is a comparison of its results with the corresponding period in 2023:
- Revenue: 10.24 billion USD (+16%)
- Net income: 1.87 billion USD (+99%)
- Earnings per share: 0.23 USD (+102%)
- Operating income: 2.27 billion USD (+51%)
- Operating margin: 22.2% (+530 basis points)
- Total subscribers: 301.6 million (+15%)
In its commentary on the Q4 2024 results, Netflix’s management expressed satisfaction with the company’s strong financial performance and strategic progress. They highlighted a 16% year-on-year increase in revenue and a 102% rise in EPS, both of which exceeded market expectations. The quarter also saw a significant increase in subscriber numbers, reaching 301.6 million, driven by compelling content, including major releases such as the Jake Paul vs Michael Tyson fight and NFL games.
Management emphasised the importance of continued investment in original content, which has helped boost user engagement and reduce subscriber churn. Additionally, plans were announced to expand Netflix’s proprietary advertising platform to twelve countries, aiming to improve margins and monetisation by reducing reliance on intermediaries. Netflix’s management reiterated its confidence in the company’s strategic direction, highlighting that investment in content and the development of advertising technologies are key drivers of growth and long-term success.
For 2025, Netflix provided guidance indicating continued optimism. The company raised its full-year revenue forecast to approximately 44.00 billion USD – a 0.50 billion USD increase from previous estimates. The operating margin was projected at 29%, one percentage point above earlier expectations. Management also referred to plans for further investment and expansion across gaming, advertising, and live streaming, aiming to enhance the platform’s appeal to subscribers.
Netflix, Inc. Q1 2025 financial results
On 17 April, Netflixreleased its Q1 2025 financial results, which continued to show strong financial performance. The key figures compared with the same period in 2024 are as follows:
- Revenue: 10.54 billion USD (+13%)
- Net income: 2.89 billion USD (+24%)
- Earnings per share: 0.66 USD (+25%)
- Operating income: 3.34 billion USD (+27%)
- Operating margin: 31.7% (+360 basis points)
Against a backdrop of economic challenges, including concerns over US tariff policy, Netflix demonstrated impressive resilience. The company reported a 13% year-on-year increase in revenue to 10.5 billion USD, while net income rose to 2.9 billion USD. Co-CEO Greg Peters noted that Netflix has historically remained resilient even during economic downturns, with no significant changes in customer behaviour.
A significant development was Netflix’s strategic shift towards advertising. The ad-supported plan accounted for 55% of new subscriptions in the regions where it was available, indicating progress in developing new revenue streams. The company planned to double advertising revenue in 2025 with its own advertising platform.
For Q2 2025, Netflix forecast revenue of 11.04 billion USD, reflecting continued growth driven by increased subscriptions and advertising revenue. The company maintained its full-year revenue forecast of 43.5–44.5 billion USD and raised its target operating margin to 29% from 28%. These forecasts underscored Netflix’s confidence in its strategy and its ability to navigate economic challenges.
Netflix, Inc. Q2 2025 financial results
On 17 July, Netflixreleased its Q2 2025 financial results, again exceeding expectations. The key figures compared with the same period in 2024 are as follows:
- Revenue: 11.08 billion USD (+16%)
- Net income: 3.13 billion USD (+46%)
- Earnings per share: 0.72 USD (+47%)
- Operating income: 3.77 billion USD (+45%)
- Operating margin: 34.1% (+690 basis points)
Netflix delivered excellent results for Q2 2025, with revenue rising 16% year-on-year to approximately 11.08 billion USD and net income and earnings per share surging 46–47% to 3.13 billion USD and 0.72 USD per share, respectively, exceeding analyst expectations.
Advertising emerged as a new growth driver for Netflix. The company continued developing its Ads Suite advertising platform, including targeting, programmatic buying, and interactive formats. Netflix confirmed that it expected to double advertising revenue in 2025. This business could significantly diversify the company’s revenue streams.
Content remained one of Netflix’s strengths. Although the company no longer discloses subscriber numbers, it reported high user engagement: the third season of Squid Game attracted 122 million views. At the same time, Stranger Things and other flagship releases were expected in the second half of the year. This supported growth in viewing time and subscriber retention.
In addition, AI adoption contributed to margin growth. Management expected the operating margin to reach around 30% for full-year 2025. AI in content production and personalised recommendations helped reduce costs and increase engagement.
For Q3 2025, management forecast revenue of 11.53 billion USD, above the consensus forecast of 11.31 billion USD. Content spending was expected to increase in Q3 and particularly in Q4, including spending on sports broadcasts. However, even with this in mind, the company expected margins to improve both quarter-on-quarter and year-on-year.
Netflix, Inc. Q3 2025 financial results
Netflix released its Q3 2025 results on 21 October. The key figures compared with the same period in 2024 are as follows:
- Revenue: 11.51 billion USD (+17%)
- Net income: 2.55 billion USD (+8%)
- Earnings per share: 0.59 USD (+9%)
- Operating income: 3.25 billion USD (+12%)
- Operating margin: 28.2% (–140 bps)
- Free cash flow: 2.66 billion USD (+21%)
Netflix delivered strong revenue growth in Q3 2025 – up 16% year-on-year – in line with the company’s forecasts. However, profit came in slightly below expectations due to one-off expenses of 619 million USD related to a tax dispute in Brazil. The company recognised these costs within cost of revenue, thereby reducing the operating margin by more than five percentage points. Without this factor, the margin would have exceeded the projected 31.5% level. Earnings per share were 0.59 USD – higher than a year earlier (0.54 USD) but approximately 1 USD below Netflix’s internal forecast due to the tax-related charge.
Despite this, the company’s underlying business metrics remained very strong. Netflix reported record advertising sales and a substantial increase in long-term contracts with US advertisers. Platform viewing share rose to its highest level since late 2022 in both the US and the UK. The company highlighted strong audience interest in content – with KPop Demon Hunters leading the way among films – while live streaming continued to expand, including popular broadcasts of sporting events such as the Canelo vs Crawford fight. Management reported that the advertising business continues to grow rapidly and, according to external estimates, could more than double in 2025.
For Q4 2025, Netflix expected revenue of about 11.96 billion USD, up 17% year-on-year. The operating margin was forecast at around 23.9%, two percentage points higher than in the same quarter of the previous year. For the full year 2025, the company anticipated revenue of approximately 45.1 billion USD, a 16% increase from 2024. The operating margin forecast was slightly lowered to around 29%, down from the earlier projection of 30%, due to the one-off tax-related costs in Brazil.
Netflix, Inc. Q4 2025 financial results
On 20 January, Netflixreleased its Q4 2025 financial results. The key figures compared with the same period in 2024 are as follows:
- Revenue: 12.05 billion USD (+18%)
- Net income: 2.42 billion USD (+29%)
- Earnings per share: 0.56 USD (+31%)
- Operating income: 2.95 billion USD (+30%)
- Operating margin: 24.5% (+220 basis points)
- Free cash flow: 1.87 billion USD (+35%)
Netflix delivered strong Q4 2025 results, exceeding market expectations for revenue and earnings per share. Revenue reached 12.05 billion USD, above the analyst consensus forecast of around 11.97 billion USD. This was driven by growth in paid subscriptions, which rose to 325 million worldwide from 301.6 million a year earlier. This supported subscription revenue, which continued to grow amid increased demand for content. Net income reached 2.42 billion USD, up 29% compared with the same period a year earlier. As a result, earnings per share (EPS) came in at 0.56 USD, also exceeding market expectations of around 0.55 USD.
Netflix’s main growth drivers during the quarter were an increase in paid subscriptions and higher advertising revenue. According to the company, advertising revenue increased to more than 2.5 times the previous year’s level, supporting its strategy of diversifying revenue streams.
Management also provided a positive outlook for Q1 2026, forecasting revenue of around 12.16 billion USD, corresponding to 15% growth compared with the same quarter a year earlier. The earnings per share forecast was 0.76 USD, which the market also viewed positively. Netflix expected the operating margin to reach 32.1% in the following quarter, indicating that the company would maintain high profitability. Compared with the same quarter a year earlier, this improvement showed that Netflix continued to keep costs under control despite rising content spending.
Netflix, Inc. Q1 2026 financial results
On 16 April, Netflixreleased its Q1 2026 financial results. The key figures compared with the same period in 2025 are as follows:
- Revenue: 12.25 billion USD (+16%)
- Net income: 5.28 billion USD (+83%)
- Earnings per share: 1.23 USD (+86%)
- Operating income: 3.96 billion USD (+18%)
- Operating margin: 32.3% (+60 basis points)
- Free cash flow: 5.09 billion USD (+91%)
Netflix delivered strong Q1 2026 results, exceeding market expectations for revenue and earnings. Revenue increased to 12.25 billion USD, while operating income rose to 3.96 billion USD. The main growth drivers were an expanding user base, higher subscription prices, and increased advertising revenue. The company also noted that revenue came in slightly above its own forecast.
At the same time, the sharp increases in net income and earnings per share were also supported by a one-off factor. Netflix explicitly stated that diluted EPS of 1.23 USD received an additional boost from a 2.8 billion USD breakup fee related to the Warner Bros. deal. For the same reason, free cash flow also rose significantly to 5.09 billion USD, up from 2.66 billion USD a year earlier. In other words, the quarter was strong, but overall profitability received an additional boost from the one-off payment.
For Q2 2026, Netflix expected revenue of 12.57 billion USD, an operating margin of 32.6%, and earnings per share of 0.78 USD. The company maintained its full-year 2026 outlook, expecting revenue of 50.7–51.7 billion USD and an operating margin of 31.5%. However, it raised its free cash flow forecast to 12.5 billion USD from 11 billion USD, mainly due to the same one-off payment related to the failed Warner Bros. deal.
Netflix, Inc. Q2 2026 financial results
On 16 July, Netflixreleased its Q2 2026 financial results. The key figures compared with the same period in 2025 are as follows:
- Revenue: 12.56 billion USD (+13%)
- Net income: 3.40 billion USD (+9%)
- Earnings per share: 0.80 USD (+11%)
- Operating income: 4.19 billion USD (+11%)
- Operating margin: 33.4% (–70 basis points)
- Free cash flow: 1.53 billion USD (–33%)
Netflix delivered steady growth in its key financial metrics in Q2 2026. Revenue rose to 12.56 billion USD, driven by an expanding user base, higher subscription prices, and advertising growth. All regions posted double-digit revenue growth, while operating income and earnings per share came in slightly above the company’s forecast.
The operating margin declined from 34.1% to 33.4% as content amortisation expenses grew faster than revenue. Netflix had previously warned that most of the increase in these expenses would occur in the first half of the year.
Free cash flow declined to 1.53 billion USD from 2.27 billion USD a year earlier. The main reason was higher tax payments, partly related to the compensation received from Warner Bros. in the previous quarter. As a result, the one-off income boosted earnings and cash flow in Q1 but led to additional tax payments in Q2.
The advertising business continued to develop and remained one of the key sources of future growth. Netflix still expects to generate around 3 billion USD in advertising revenue in 2026, approximately double the previous year’s level.
For Q3 2026, Netflix expects revenue of 12.86 billion USD, corresponding to around 12% year-on-year growth, earnings per share of 0.82 USD, and an operating margin of 33.2%, up from 28.2% a year earlier. The full-year 2026 revenue forecast was narrowed from 50.7–51.7 billion USD to 51.0–51.4 billion USD, although the midpoint remained effectively unchanged. The operating margin forecast also remained unchanged at 31.5%.
Netflix, Inc. Q3 2026 financial results
On 20 October, Netflixreleased its Q3 2026 financial results for the quarter ended 30 September. The key figures compared with the same period in 2025 are as follows:
- Revenue: 12.87 billion USD (+12%)
- Net income: 3.66 billion USD (+44%)
- Earnings per share: 0.87 USD (+49%)
- Operating income: 4.49 billion USD (+37%)
- Operating margin: 34.6% (+640 basis points)
- Free cash flow: 2.88 billion USD (+8%)
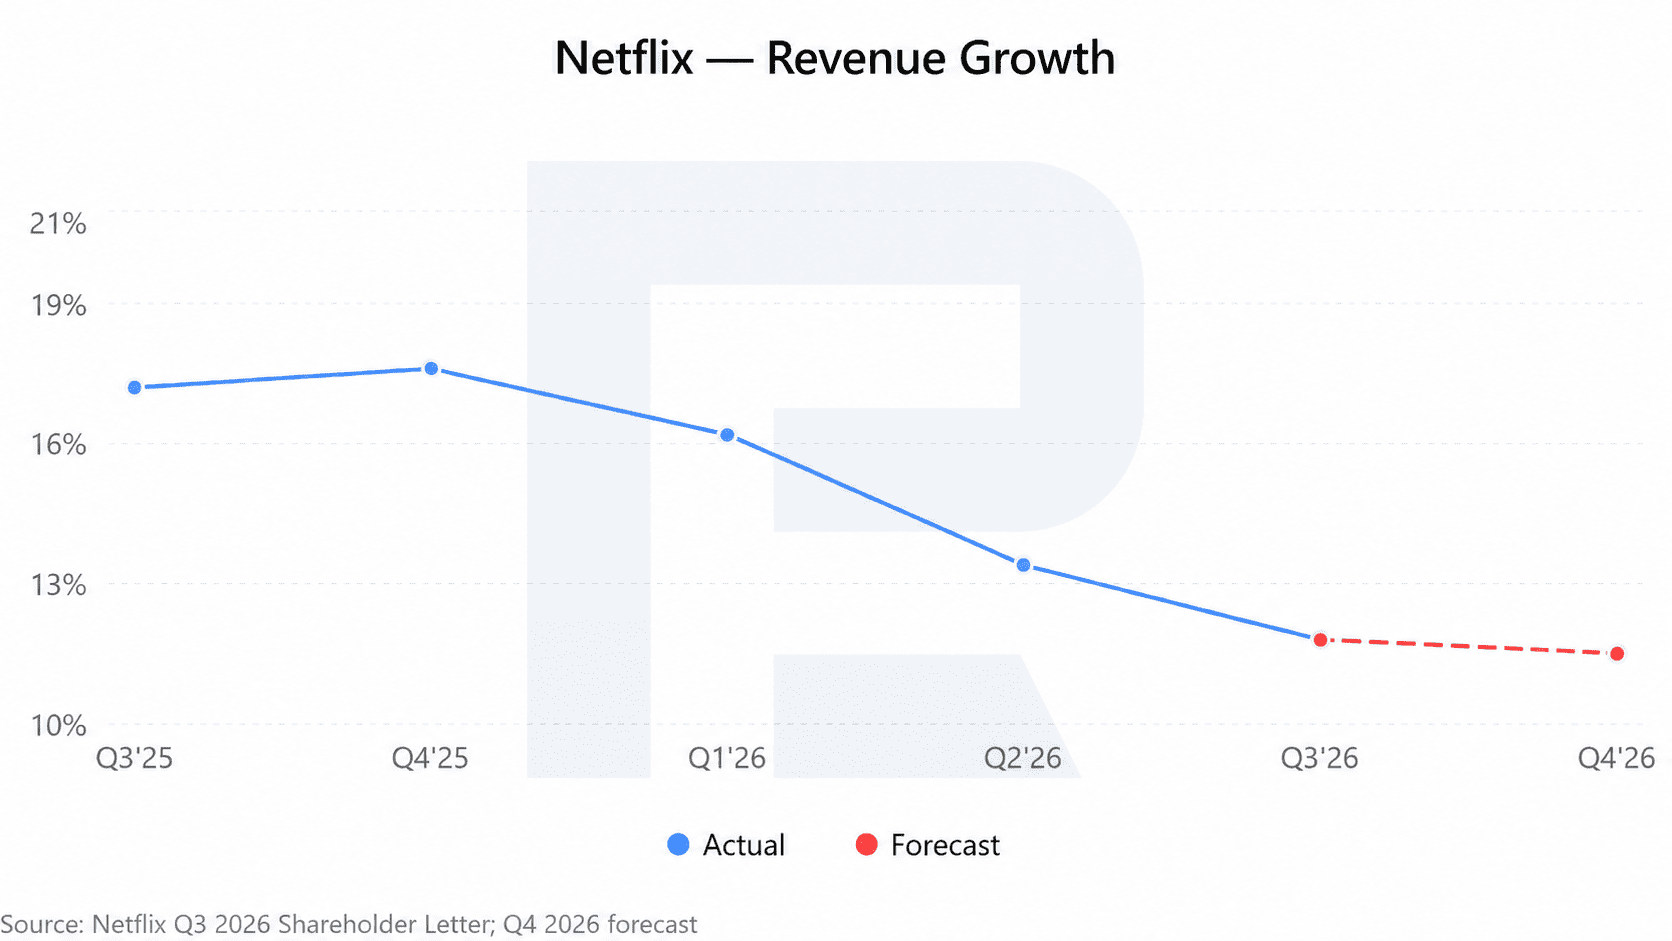
Netflix’s Q3 2026 results showed a significant improvement in financial performance but also confirmed a slowdown in business growth. Revenue rose 12% to 12.87 billion USD, net income rose 44% to 3.66 billion USD, and the operating margin reached 34.6%. Despite the positive performance, Netflix shares continued to decline after the report was released on 20 October.
The main concern for Netflix remains slowing revenue growth. At the end of 2025, the company was increasing revenue by more than 17% year-on-year, but the rate slowed to 12% in Q3 2026. Management forecasts a further slowdown to 11.5% in Q4. For a company whose shares have traditionally traded at a substantial premium based on expectations of strong growth, this trend represents a significant negative factor.
The advertising business, once seen as a key driver of future growth, was another source of disappointment. Netflix lowered its 2026 advertising revenue forecast from 3.0 billion USD to 2.7 billion USD due to delays in rolling out new advertising tools. Although advertising revenue is expected to grow by more than 80% for the year, the revised forecast suggests this business is developing more slowly than expected.
At first glance, Netflix’s profitability appears strong. Operating income rose 37%, while the operating margin improved from 28.2% to 34.6%. This is a strong result, particularly against the backdrop of slowing revenue growth. However, in Q3 2025, Netflix recognised an additional expense of 619 million USD related to a tax dispute in Brazil. This one-off factor reduced the previous year’s profit and created a favourable comparison base.
Excluding this expense from the Q3 2025 results, the previous year’s operating margin would have been 33.6%. Therefore, the comparable improvement in profitability in Q3 2026 was around 1 percentage point rather than the reported 6.4 percentage points.
Another concerning signal was the scale of internal changes at Netflix. In October, the company announced plans to cut around 1,000 jobs, or 6% of its workforce. This was its largest round of job cuts since 2022. At the same time, Netflix began restructuring the leadership responsible for film and television production. Peter Rice became the new head of content, replacing Bela Bajaria.
Free cash flow remains a positive factor, rising 8% to 2.88 billion USD. However, Netflix lowered its full-year 2026 forecast from 12.5 billion USD to 12.0 billion USD, mainly due to a planned real estate transaction. This reduction does not, by itself, indicate a deterioration in the core business, but it adds to the broader picture of more cautious management expectations.
The Q4 2026 outlook also came in below analyst expectations. Netflix expects revenue of 13.44 billion USD and earnings per share of 0.67 USD, compared with market forecasts of around 13.5 billion USD and 0.73 USD, respectively. The operating margin is expected to be 26%, significantly below the Q3 level.
Netflix’s Q3 2026 report confirmed that the company’s main challenge is the deteriorating outlook for future growth. Netflix continues to increase revenue, generate billions of dollars in earnings, and produce positive free cash flow. However, year-on-year revenue growth has been steadily slowing, the advertising business is developing more slowly than initially planned, and the outlook for the next quarter fell short of analyst expectations.
Additional concerns include declining viewer activity, intensifying competition, and extensive management changes. These factors raise questions about whether Netflix can maintain its previous revenue growth pace without continually raising subscription prices.
Netflix, Inc. key valuation multiples analysis
Below are Netflix’s key valuation multiples following its Q3 2026 financial results, calculated at a share price of 62 USD.
| Multiple | What it indicates | Value | Comment |
|---|---|---|---|
| P/E (TTM) | Price paid for 1 USD of earnings over the past 12 months | 17.34 | Attention! Forecasts presented in this section only reflect the author’s private opinion and should not be considered as guidance for trading. RoboForex bears no responsibility for trading results based on trading recommendations described in these analytical reviews. |